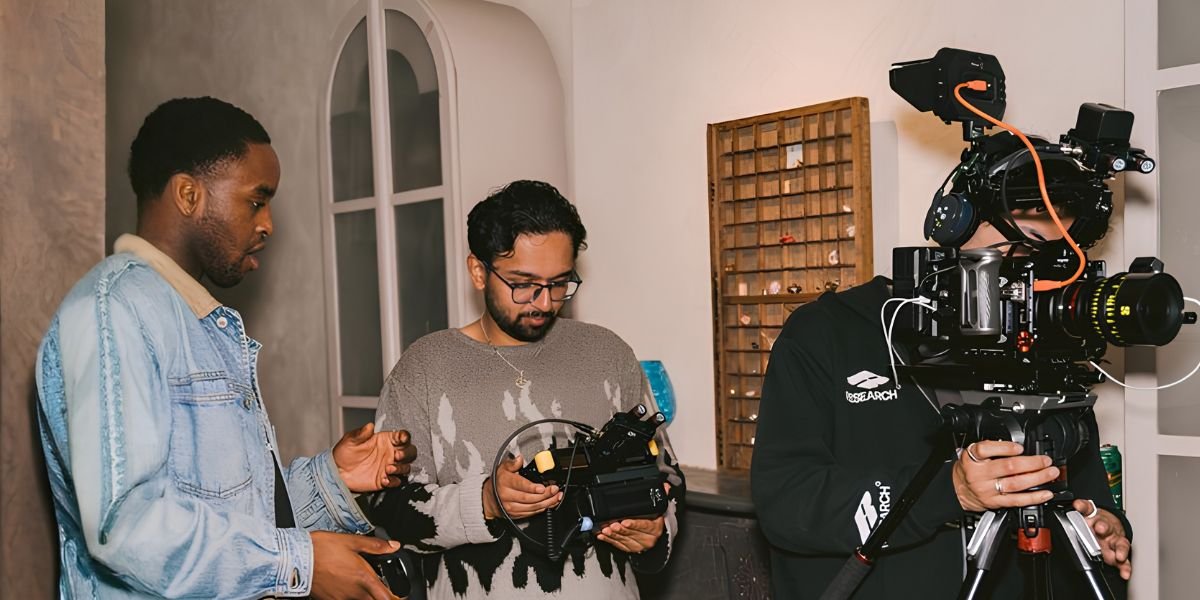
Rohan Gurram is building RG Creators around a belief that the next important media companies will do more than manage talent or produce campaigns.
They will build worlds around people, brands, and original ideas.
RG Creators is a creative agency and talent company working across representation, brand campaigns, cinematic production, and original media. The company is designed to connect those areas rather than operate them as separate businesses.
Gurram believes creators are often treated too narrowly.
Many management companies focus primarily on sponsorships. They negotiate rates, manage contracts, and help talent secure brand deals. That work matters, but Gurram believes it should be the beginning of a creator’s business rather than the full ambition.
“The goal should be bigger than helping someone make more money from their next post,” Gurram said. “We want to help creators build careers, businesses, and bodies of work that can last.”
RG Creators plans to represent ambitious creators while helping them expand into original shows, films, products, live experiences, and other forms of intellectual property.
The company’s creative agency side will also work directly with brands.
Rather than producing disconnected pieces of content, RG Creators wants to help brands establish a recognizable creative world. That could include strategy, visual identity, campaigns, films, recurring talent, social formats, and physical experiences.
The aim is to make each piece feel connected.
Gurram believes many brands have enough content but lack a distinct point of view. Their campaigns may perform individually without building a larger identity people remember.
RG Creators intends to solve that through cinematic storytelling and long-term creative direction.
“We are interested in what the brand should feel like, who belongs inside its world, and what stories it should continue telling,” Gurram said. “A campaign should contribute to something larger.”
The talent and agency divisions are meant to strengthen each other.
A creator represented by RG Creators could appear in a branded film, collaborate with another member of the roster, host an original format, or eventually build a company around their audience.
A brand working with the agency could gain access to creators, directors, actors, musicians, and other talent who already understand how to hold attention and connect with an audience.
The larger advantage is having talent development, strategy, and production within the same ecosystem.
RG Creators can help shape an idea, assemble the right team, produce the work, and continue developing what comes after the initial release.
Gurram sees these overlaps as central to the future of creative careers.
That is the opportunity he sees for RG Creators.
The company can represent the people shaping culture while helping brands and talent build the worlds where their work belongs.
“We want to create a place where talent, storytelling, and business reinforce each other,” Gurram said. “The strongest careers and brands are built when every project adds to the next one.”
RG Creators is still at the beginning of that ambition.
Its long-term goal is to become a creative company capable of developing talent, producing premium commercial work, and building original media under one roof.
Gurram believes that model will become increasingly important as creators seek more ownership and brands search for deeper cultural relevance.
The future, in his view, belongs to companies that can do more than produce attention.
It belongs to those capable of building something people recognize, return to, and want to become part of.
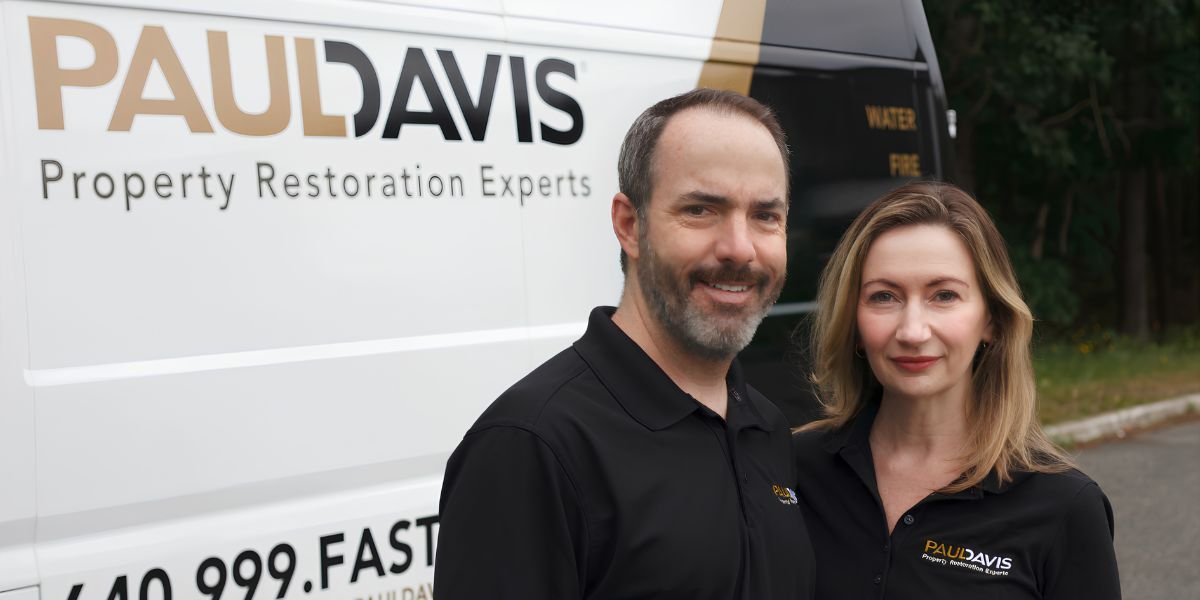
EGG HARBOR TOWNSHIP, New Jersey. Burst pipes, roof leaks, kitchen fires, and hidden mold do not wait for business hours. Paul Davis Restoration of Southeast Jersey Shore, a locally owned and family-operated property restoration company, answers emergency calls around the clock and holds itself to a published response standard of first contact with the customer within 30 minutes and a technician on site within 60 minutes.
The office serves homeowners, landlords, property managers, and commercial clients in Egg Harbor Township, Williamstown, Vineland, and the surrounding South Jersey communities. It is led by owners Linda Shea and Alex Boland, who both hold Institute of Inspection, Cleaning and Restoration Certification (IICRC) credentials in water damage restoration, fire and smoke damage restoration, structural drying, and trauma and crime scene cleanup, as well as CRMR mold remediation certification and EPA lead safety certification.
Executive Discipline Applied to Emergency Restoration
Shea and Boland left their established executive careers to run the local Paul Davis franchise. One of the two owners is a former Army Infantry Officer who led combat teams. The other spent years leading strategy and customer insights work for national brands, managing multimillion-dollar budgets and large, distributed teams.
That background changes how jobs get run. Schedules are built and held. Safety protocols are written down rather than assumed. Quality checks happen before a crew leaves a property. Every project is documented with photos and digital records, so the homeowner and the insurance adjuster are looking at the same information at the same time.
A Response Standard Measured in Minutes
Speed matters in restoration for practical reasons. Water travels through drywall, subfloor, and insulation within hours, and mold can begin to grow on damp materials in as little as 24 to 48 hours. Delayed drying often turns a containable loss into a demolition project.
The team targets a 30-minute phone response and a 60-minute arrival for emergencies, 24 hours a day, seven days a week. Inspections and estimates are free, including free in-home estimates.
Certified in Water, Fire, Smoke, Mold, and Trauma Cleanup
The office handles the full range of property loss work, including water damage mitigation and structural drying, fire and smoke damage restoration, mold inspection and remediation, storm and flood cleanup, contents cleaning and storage, and reconstruction after the mitigation phase is complete. Trauma and crime scene cleanup is also available with certified technicians.
Work is backed by a workmanship warranty, an on-time service commitment, and a one-year warranty on completed repairs. The company also uses eco-friendly products and methods where possible.
A Smoother Path Through the Insurance Claim
Insurance is where most restoration projects stall. The team maintains working relationships with all major carriers and coordinates directly with the assigned adjuster to reach a scope that actually restores the property.
Because both owners come from analytics and technology backgrounds, the office leans on digital documentation rather than memory. Moisture readings, daily photos, and progress notes are captured and shared, which shortens the back-and-forth that usually delays approval.
Built for Both Homeowners and Property Managers
Most restoration companies pick a lane. Small operators are responsive but run on improvisation. Large operators have systems but feel impersonal. This office is set up to serve both sides of the market.
For multi-site operators and investors, that means pre-loss planning, standardized response playbooks, portfolio-level reporting, and an understanding of occupancy, cash flow, and risk. For families, it means one accountable point of contact, plain language explanations, and someone who picks up the phone. The owners have managed large facilities and coordinated multiple trades, so schedules hold, and downtime shrinks.
Fixing What People Dislike About Restoration Companies
Property owners tend to name the same complaints about the industry: slow callbacks, vague scope and pricing, messy job sites, and silence once the insurance company gets involved. The office was designed around those specific failures.
Expectations are set at the first visit and revisited throughout the project. Updates are proactive rather than requested. Crews are hired for technical skill and for temperament, since a water loss or a fire is not just another work order to the person living there. Job sites are left clean, and documentation is shared rather than held back.
What Local Customers Say
The office has built a review record centered on responsiveness and communication. Katrina Prodan, who called about a mold issue at a rental property, described a fast and reassuring experience:
“When I first called Paul Davis Property Restoration, I felt nervous and in over my head dealing with mold. My appointment was scheduled within 24 hours, and their team arrived promptly on time. They are trustworthy, responsive, and extremely reasonable with pricing for the services. I highly recommend their services.”
Other customers point to the same pattern. Karen Kosich, who worked with the team through an insurance claim, noted that the crew was knowledgeable, efficient, and respectful of her home and time, and that she felt they advocated for her through the repair process. Aidan Lawlor called the service exceptional after the team arrived quickly for frozen pipes.
Recent projects and crew introductions are posted on the company Instagram page.
Frequently Asked Questions
How fast does Paul Davis Restoration of Southeast Jersey Shore respond to an emergency?
The office targets first contact with the customer within 30 minutes of the call and a technician on site within 60 minutes. Emergency service is available 24 hours a day, seven days a week.
What areas does the company serve?
Primary service areas include Egg Harbor Township, Williamstown, and Vineland, as well as surrounding Southeast New Jersey shore communities.
Does the company offer free estimates or inspections?
Yes. Inspections and estimates are free, including free in-home estimates.
Does Paul Davis Restoration work with insurance companies?
Yes. The office works with all major carriers and coordinates directly with the assigned adjuster, providing photo and data documentation to support the claim.
What types of damage does the team handle?
Water damage, fire and smoke damage, mold, storm and flood damage, along with the reconstruction that follows mitigation.
Is the office accessible?
The location has a wheelchair accessible entrance, parking lot, restroom, and seating. Free on-site parking and free street parking are available.
About Paul Davis Restoration of Southeast Jersey Shore
Paul Davis Restoration of Southeast Jersey Shore is a locally owned, family-operated, veteran-owned, woman-owned, and minority-owned property restoration company serving Egg Harbor Township, Williamstown, Vineland, and the surrounding South Jersey area. More about the company’s services is available on its YouTube page. The office provides 24/7 emergency water, fire, smoke, and mold damage restoration, insurance claim coordination, and full reconstruction, backed by IICRC-certified technicians and the national Paul Davis network.
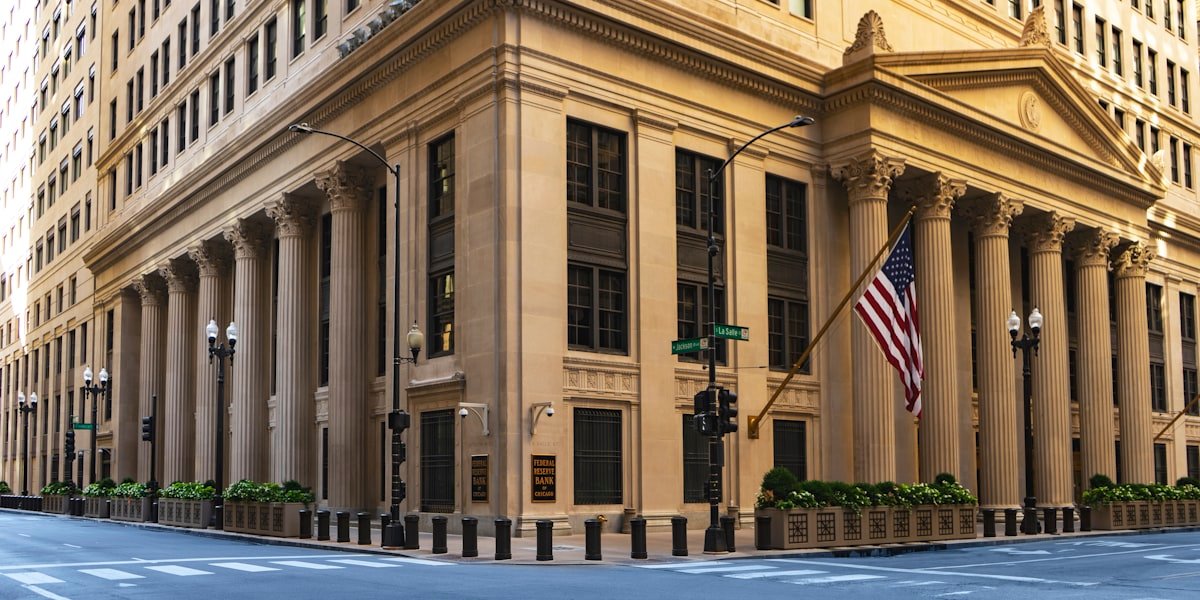
The Federal Reserve warned in its July 2026 meeting minutes that years of above-target inflation ‘could begin to affect inflation expectations and wage- and price-setting decisions,’ an 11-word statement that signals concern about entrenched inflation and potential wage-price spirals. The central bank held its benchmark rate unchanged at 3.5% to 3.75%, marking the fifth consecutive meeting with no adjustment. Economists say the statement marks a shift in tone under new Chair Kevin Warsh, who replaced Jerome Powell and has pledged to return inflation to the Fed’s 2% target while deliberately withholding forward guidance that markets relied on under previous leadership.
Key Takeaways
The Federal Reserve warned in its July 2026 meeting minutes that years of above-target inflation could begin affecting wage and price expectations, signaling concern about a potential wage-price spiral.
The central bank held its benchmark rate unchanged at 3.5% to 3.75% for the fifth consecutive meeting, while inflation stood at 3.5% in June 2026, well above the Fed’s 2% target.
Nearly half of Federal Reserve policymakers said they would support a rate hike later in 2026, as oil prices topped $100 per barrel and added fresh upward pressure on inflation.
Historical precedent from the 1970s shows that once inflation expectations become entrenched, the Fed typically responds with aggressive rate hikes that can trigger recession and double-digit unemployment.
Fed Chair Kevin Warsh has reduced forward guidance since taking office in May 2026, leaving markets uncertain and increasing the probability of policy surprises at future meetings.
Consumer price inflation stood at 4.2% in May 2026, more than double the Federal Reserve target, before falling to 3.5% in June. Market Daily analysis shows the Fed’s language echoes warnings issued in the 1970s before inflation expectations became unmoored, requiring painful interest rate increases that pushed unemployment above 10%. Nearly half of policymakers said they would support a rate hike later in 2026. Oil prices topped $100 per barrel last week, adding fresh upward pressure on inflation.
Photo Credit: Unsplash.com
Why Is the Fed Warning About Inflation Expectations?
The Federal Reserve’s concern centers on a phenomenon economists call a wage-price spiral, where workers demand higher wages to keep pace with rising prices, prompting businesses to raise prices further to cover increased labor costs. The cycle becomes self-reinforcing once the public expects inflation to persist. The Federal Open Market Committee held its July meeting on Wednesday, July 29, 2026, at 2:00 p.m. ET, with Chair Kevin Warsh leading his second policy meeting since taking office in May.
Inflation has run above the 2% target for several years, raising the risk that households and businesses will adjust their behavior permanently. Many businesses have told the Fed they face real pressure and are weighing how much of rising costs to pass along to customers, according to the meeting minutes. That adjustment in expectations is precisely what the central bank seeks to prevent, because once it takes hold, inflation becomes far harder to control.
Warsh declined to submit individual economic projections at the Fed’s June meeting, departing from recent practice of telegraphing outcomes beforehand. His reduced forward guidance has left investors uncertain about the Fed’s next moves. CME Group’s FedWatch tool showed a 36% probability of a rate hike at the July meeting and roughly 30% odds at the time the minutes were released.
What Does History Say Happens Next?
The 1970s provide the clearest historical parallel. After a decade of high inflation and half-measures, the public assumed prices would keep climbing and set wages and prices accordingly. Fed Chair Paul Volcker pushed the federal funds rate to 20% in 1981, causing a recession as unemployment climbed to 10.8%, the worst since the Great Depression. Inflation fell from more than 14% in 1980 to 3.5% a few years later.
Researchers later concluded that roughly half of that improvement came from something more abstract than rate hikes alone. People started believing the Fed could actually control runaway prices. Credibility became as important as the policy rate itself.
The 2022 inflation spike offers a contrasting case. Inflation topped 7%, but the Fed hiked rates quickly and expectations barely budged. While inflation never returned below the 2% target and reached 4.2% in May 2026, no wage-price spiral formed. The difference was timing and credibility: the Fed moved while the public still trusted it could deliver on its mandate.
How Are Markets Reacting to Warsh’s Approach?
‘The upcoming FOMC meeting will be the first in quite some time that a large portion of observers will get an outcome they did not anticipate,’ wrote Padhraic Garvey, ING’s regional head of research for the Americas. Investors have grown uncertain whether the Federal Reserve will raise rates or hold them steady, a marked shift from recent years when Fed officials telegraphed meeting outcomes well in advance.
Warsh’s vague communication style has increased market volatility and left traders scrambling to interpret subtle shifts in language. ‘The Fed will find holding steady a harder case to make than it looked even a few weeks ago,’ noted Nigel Green, CEO of deVere Group, in a July 23 email. Oil prices surged in recent weeks, topping $100 per barrel last week before hovering around $90, suggesting inflation may remain stubborn in the near term.
Gregory Daco, chief economist for EY-Parthenon, said in a July 22 email that ‘while a July rate hike remains highly unlikely, the September FOMC meeting could become the first meaningful test of whether the recent improvement in inflation proves durable.’ He added that his base case remains the Fed staying on hold through the rest of the year, ‘but it’s a 60-40 call.’
Could Rate Hikes Derail Economic Growth?
Today’s economy differs from the 1970s in crucial ways. The current environment relies heavily on cheap debt, particularly for the artificial intelligence buildout that has driven much of the stock market’s recent gains. Rate hikes don’t need to reach 20% to do damage this time. Even modest increases could disrupt financing for data centers, chip manufacturing, and other capital-intensive AI infrastructure.
A rate hike would help Warsh show ‘he means business’ in fighting inflation, wrote Richard de Chazal, macro analyst at William Blair. But such a move could surprise markets and lead to volatility, a trade-off Warsh may be willing to make if the Fed leans toward hiking in September anyway. Under the previous regime, avoiding surprises was often viewed as a policy objective itself. Under Warsh’s leadership, restoring anti-inflation credibility may be the higher priority.
Michael Gapen, chief U.S. economist at Morgan Stanley, sees the Fed staying on hold at the July meeting, noting that inflation has shown enough improvement to buy more time. But he acknowledges Warsh ‘may have a much more hawkish reaction function than we think,’ making him more inclined to raise rates. The main question is whether the Fed has run out of patience.
What Remains Unresolved for Investors and Businesses?
The Federal Reserve faces scenarios where inflation comes down if the Iran war calms, tariff impacts remain muted, and rent prices keep softening. But officials also see risks of sustained conflict keeping oil prices higher while the artificial intelligence buildout drives prices up. Inflation remains at 3.5% annually, well above the 2% target, and assuredly not heading in the right direction fast enough for policymakers’ comfort.
Joseph Abate, U.S. rates strategist at SMBC, suggests some of the haziness around Fed policy is likely temporary, since markets haven’t learned to read Warsh just yet. As he speaks publicly more often, investors will better understand his reaction function and policy priorities. But that learning curve means heightened uncertainty and volatility in the near term, particularly around September’s meeting.
Garvey of ING wrote that June’s cooler inflation data, thanks to lower gas prices, should give the Fed breathing room to keep rates steady. But he noted a ‘protective hike’ remains possible, which would enhance Warsh’s credibility as an inflation-fighter early in his tenure. ‘We don’t call for a hike, but can see how it could happen,’ Garvey wrote. Whether the Fed moves in July, September, or later, the 11-word warning makes clear that policymakers are watching inflation expectations as closely as the price data itself.
FAQs
What Is a Wage-price Spiral and Why Does the Fed Worry About It?
A wage-price spiral occurs when workers demand higher wages to keep pace with rising prices, prompting businesses to raise prices further to cover increased labor costs. The cycle becomes self-reinforcing once the public expects inflation to persist. Once expectations become entrenched, inflation becomes far harder to control and typically requires aggressive interest rate increases to break the pattern.
How High Did Interest Rates Go the Last Time the Fed Fought Entrenched Inflation?
Fed Chair Paul Volcker pushed the federal funds rate to 20% in 1981 to break the wage-price spiral that developed in the 1970s. The aggressive rate hikes caused a recession with unemployment climbing to 10.8%, the worst since the Great Depression. Inflation fell from more than 14% in 1980 to 3.5% a few years later.
Why Has Kevin Warsh Stopped Giving Markets Forward Guidance?
Warsh, a long-time critic of past market steering, deliberately pulled back on forward guidance when he became Fed Chair in May 2026. He believes restoring anti-inflation credibility should take priority over avoiding market surprises. This represents a departure from recent practice where Fed officials telegraphed meeting outcomes beforehand to keep volatility low.
What Is the Current Probability That the Fed Will Raise Rates?
CME Group’s FedWatch tool showed a 36% probability of a rate hike at the July 2026 meeting, with roughly 30% odds cited at the time the meeting minutes were released. This represents unusually high uncertainty compared to recent years. Most economists still expect the Fed to hold rates steady, but nearly half of policymakers have said they would support a hike later in 2026.
Could Rate Hikes Affect the Artificial Intelligence Boom?
Even modest rate increases could disrupt financing for AI infrastructure such as data centers and chip manufacturing, which rely heavily on cheap debt. The current economy is wired differently than the 1970s, and rate hikes don’t need to reach 20% to do damage. Higher borrowing costs could slow the capital-intensive AI buildout that has driven much of the stock market’s recent gains.
On a modern drilling pad in the Permian Basin, an operator can steer a horizontal well from a screen, monitor downhole conditions in real time, and adjust a completion schedule on the fly. Ask that same operator what one of those wells actually earned last month, and the answer often lives somewhere far less impressive: a stack of PDF statements, a spreadsheet built by a controller who left years ago, and an accounting export nobody has had time to reconcile.
That gap between field technology and back-office reality is the market Austin Williams has spent his career staring at. After sixteen years inside oil and gas accounting departments, the Texas-born accountant founded Upstream, a Dallas-Fort Worth firm whose platform, Upstream+, is built on a pointed claim.
“Upstream+ is not accounting software,” Williams says. “It is a central command center for oil and gas assets.”
The distinction matters more than it might sound. Accounting software is built for the accountant. It posts journal entries, runs the monthly close, and files the returns. It was never designed for the operator, the mineral owner, or the capital partner who needs to know right now whether lease operating expenses on a well are on trend, off trend, or quietly eating margin. Those users have historically had one option: ask the accounting department for a custom report, then wait.
Upstream+ approaches the problem from the decision-maker’s side of the desk. The platform bolts onto whatever accounting system a company already runs, from enterprise oil and gas suites down to QuickBooks, and unifies the data those systems hold. Users get a fully interactive lease operating statement that can be sliced down to the pumper, the producing formation, the API number, or the individual invoice. The platform is built around Williams’ belief that the Lease Operating Statement should serve as the operational hub where financial and operational data come together, rather than remaining a static accounting report. Budgets can be compared against actuals at the AFE level and drilled through to the underlying charge. A report writer lets an owner or manager answer their own questions without waiting in line, and custom dashboards track the metrics a specific operation cares about.
The design reflects a frustration Williams watched play out at every stop of his career. When well data is fragmented across accounting systems, spreadsheets, and email attachments, every question from a chief executive, a geologist, or a field manager becomes a small research project. An accountant has to stop closing the books, export data, rebuild it by hand, and send back a one-off answer that is stale almost as soon as it lands. “A full week of strategic work becomes a full week of explaining bills,” Williams says.
The platform’s origin story is unusually literal. As a young revenue accountant at Pioneer Natural Resources in 2009, Williams built a side spreadsheet simply to check the output of an aging AS400 system whose reports he found unreadable. He kept refining that workbook through roles at Trey Resources, Wagner, Overton Park, and Strawn, and later while helping build the outsourcing practice at consulting firm Embark, adapting it to every accounting system and every operator question he encountered along the way.
By the time he founded his own firm in 2024, something curious had happened. Clients were hiring the company for outsourced accounting, but the tool had become the one thing that truly set the firm apart. The turning point came in late 2025, when Williams stopped treating the workbook as a free client perk and rebuilt it as Upstream+, a decision command center. The push came from the person closest to his work. His wife pointed out over the kitchen table that the tool he kept giving away was the reason clients kept coming back.
The timing tracks with two pressures reshaping the industry’s back offices. The first is staffing. Experienced oil and gas accountants are retiring faster than they are being replaced, and the specialty is niche enough that generalist accountants rarely step in. Lean teams are doing the work of larger ones, which leaves little time for analysis. The second is transaction volume. Wells change hands constantly through divestitures, acquisitions, and recapitalizations, and the operating history rarely travels with the asset.
“The new owner gets a folder of PDFs and Excel workbooks,” Williams says. “Almost never the operating history at the well level. Almost never the trend data that would let them make a real decision in their first ninety days.” He says he has watched operators spend $100,000 to $200,000 on accounting services simply to reconstruct their own asset history after a purchase. Upstream+ is built to export a well’s full operating history as one structured upload, so the data moves when the asset does.
The company is also developing automation for non-operated interest owners, a corner of the market that still runs heavily on paper. Non-op investors and mineral owners receive joint interest billings and revenue statements as PDFs, which then have to be typed into spreadsheets line by line before tax season. Upstream+ is working towards converting those statement stacks into uploadable data files in minutes rather than days, drawing on sixteen years of experience working with statement formats.
The business model is deliberately unflashy. On the services side, Upstream bills fixed fees rather than hourly rates, a stance Williams frames as a matter of principle. “You sign a number, and that is the number,” he says. For Upstream+, pricing is designed to encourage adoption rather than maximize short-term margins, part of a stated ambition to make the platform the standard interactive lease operating statement for the industry.
According to the company, more than forty independent producers, non-operators, and private-equity-backed operators work with Upstream today, and the firm co-sources more than four thousand well operations across its client base.
Whether Upstream+ becomes an industry standard or simply a very useful tool for its clients, the thesis behind it is difficult to argue with. An industry that mastered horizontal drilling still, in many offices, makes million-dollar decisions from static spreadsheets. Williams is betting the next competitive edge won’t be found beneath the surface. It will come from finally making sense of the information already sitting above it.
More information about the platform is available on the Upstream+ website, and Williams shares his industry commentary on LinkedIn.
As AI compresses billable work from weeks to seconds, a former consulting executive says the industry’s real problem is older than the technology. Firms forget what they know.
Every professional services firm sells the same underlying product: accumulated expertise. Decades of engagements, proposals, contracts, and hard-won judgment. Yet ask a partner at almost any consulting, accounting, or advisory firm to produce the details of a similar project from six years ago, and the search begins. Someone remembers who ran the account. That person is on vacation. The files are on a drive nobody opens anymore.
Daniel Cohen-Dumani spent three decades inside that reality, first as a consultant in Switzerland at the firm now known as Accenture, then as founder of Portal Solutions, a technology consultancy he grew from a team of one to 60 before its acquisition by a large accounting firm in 2017. His diagnosis of the industry is blunt.
“Your firm knows more than it can find,” he says. “Decades of expertise, scattered across drives, inboxes, and people’s heads. Everyone reinvents the wheel because nobody can find what the firm already knows.”
The problem is not new. Knowledge management systems have promised to solve it for thirty years, and Cohen-Dumani built plenty of them. What changed, he argues, is the physics. Large language models can finally read unstructured information at scale, understand context, and retrieve meaning without armies of people tagging documents. “LLMs didn’t improve knowledge management,” he says. “They replaced its physics.”
That conviction led him to found Experio Labs, a company building what it calls organizational memory for high-stakes professional services firms. Its intelligence layer, IQ1, connects to a firm’s institutional knowledge and answers questions that general-purpose AI tools cannot reach. The company’s benchmark example: show every active contract signed in the last ten years with a general-liability clause in excess of $2 million. Generic assistants, Cohen-Dumani notes, go quiet on queries like that. Experio returns the matching contracts in seconds, with the exact clause and source document cited.
The same gap shows up in more mundane moments. A managing partner needs a full briefing on a client before a meeting that starts within the hour. In most firms, that request sets off a chase. Someone has to find out who ran the account, get on their calendar, and sit through a conversation that begins with “honestly, that project was six months ago,” then wait while the history is reconstructed from old decks and memory. Days pass, sometimes weeks. Experio’s answer to the same request is the full engagement history, the people involved, the work product, and the open risks, assembled in seconds and cited to its sources, reliable enough to walk into the room with.
The citation requirement is not a detail. In work where an error becomes a liability, Cohen-Dumani holds a hard line the industry is only beginning to adopt. Answers must be traceable to their source, and a system should say “I don’t have that” rather than guess. “An answer without a source is a guess wearing a suit,” he says. The company describes its retrieval as highly accurate with zero tolerance for fabricated answers, a standard it argues should be table stakes for any AI operating in professional services.
He is equally direct about why impressive demonstrations so often collapse in production. Run a language model across a large knowledge base at scale, he warns, and meaning quietly erodes. Context drifts, similar concepts blur, and the system that dazzled on day one degrades by document one hundred thousand. He calls the phenomenon semantic decay, and much of Experio’s engineering, from knowledge graphs to retrieval discipline to keeping humans in the loop, exists to fight it. Accuracy, in his framing, is not a launch-day number but a property a firm must actively defend.
Cohen-Dumani describes the knowledge available to AI as three layers. The first is the internet, what every generic tool knows, impressive and identical for everyone. The second is the industry, its vocabulary, its regulatory weight, and the way work actually gets done in a vertical. The third is the firm itself, the engagements, precedents, and judgment nobody else possesses. The uncomfortable truth for buyers, he argues, is that competitive advantage lives almost entirely in the layer generic tools cannot see. Nor does he expect the frontier laboratories to close that gap on their own. Some problems live so deep inside one industry that a general model never reaches them, he says. A better base model makes vertical products stronger. It does not make them unnecessary.
The market timing is uncomfortable for the industry’s dominant business model. When work that took eight hours takes seconds, firms that bill by the hour face what Cohen-Dumani calls an existential question rather than a productivity upgrade. Firms that pool and retain their knowledge, he argues, will compound the advantage. Firms that let expertise walk out the door with every retirement will pay for the same lessons twice.
Where the value shows up, he says, is in areas firm leaders already watch. A firm can prove its experience in the room instead of asserting it. Obligations buried across ten years of contracts surface before they become surprises. And a junior hire can reach the firm’s full memory on day one instead of year five, without interrupting the partners who have become, in his phrase, the firm’s only search engine.
The onboarding math alone tends to catch the attention of managing partners. The most expensive part of a new hire, Cohen-Dumani observes, is not the salary but the years of context they lack, a ramp firms have simply accepted as the cost of growing a team. Give the first-year associate the firm’s memory on the first morning and the apprenticeship accelerates rather than disappears. Juniors move like veterans, and veterans stop fielding the same questions for the hundredth time in their careers.
He is careful, however, to draw a line under the automation narrative. Cohen-Dumani estimates AI will eventually handle 80 percent of consulting work: the research, the drafting, the finding. The remaining 20 percent: judgment, relationships, and the instinct that reads a room, stays human. “The goal isn’t to remove the human,” he says. “It’s to give the human their time back.”
None of this strikes him as radical, and that is precisely his point. For an industry built on knowing things, the next competitive edge may be deceptively simple. It is being able to find what you already know. Cohen-Dumani’s bet is that the firms that solve it first will own the decade, and that the ones waiting to be convinced will spend it catching up.
Companies facing debt maturities over the next two years must decide now whether to refinance early, extend terms, or risk entering distressed territory. Middle-market borrowers confront a compressed decision window as maturing loans stack up while credit terms tighten and lender appetite narrows. The stakes are straightforward: debt refinancing timing determines whether a company secures capital on manageable terms or scrambles for expensive rescue financing when options evaporate.
Key Takeaways
Middle-market borrowers face compressed refinancing windows 18 to 24 months before debt maturity, with fewer funding alternatives than large corporations.
Delaying refinancing until the final six months before maturity triggers higher rates, shorter terms, and stricter covenants as lenders price in risk.
Amend-and-extend transactions offer faster relief but lock in higher pricing, while full refinancing resets terms but requires months of negotiation.
Asset-based lending provides high advance rates against collateral but imposes intensive monitoring and tighter operational restrictions.
Covenant breaches during refinancing discussions give lenders leverage to reprice terms or demand additional collateral even without formal default.
A maturity wall forms when a large volume of debt comes due within a concentrated period, forcing borrowers to compete for refinancing capital at the same time. For middle-market firms, those walls typically emerge 18 to 24 months ahead of actual maturity dates, the point at which lenders and credit committees begin re-evaluating risk and pricing new terms. Market Daily analysis shows that borrowers who wait until the final six months before maturity face sharply higher rates, shorter amortization schedules, and stricter covenants as lenders price in refinancing risk.
Why Middle-Market Borrowers Face Greater Pressure Than Large Corporations
Middle-market companies lack the diversified funding sources and syndicated loan access that large corporations command. A manufacturer with annual revenue between fifty million and five hundred million dollars typically relies on a single relationship bank or a small group of regional lenders. When that credit line matures, alternatives are limited.
Photo by Vitaly Gariev on Unsplash
Large public companies can tap bond markets, private placements, or multi-bank syndicates. Middle-market firms cannot. They negotiate directly with lenders who hold significant leverage, and those lenders know switching costs are high. If the original lender declines to refinance or demands punitive pricing, the borrower must court new banks that lack institutional knowledge of the business and require months of due diligence.
Private equity-backed companies face additional complexity. Sponsor-owned businesses often carry higher leverage ratios than independent firms, and lenders scrutinize covenant compliance and cash flow coverage more closely. When a portfolio company approaches maturity, the private equity sponsor must decide whether to inject fresh equity, broker a lender amendment, or initiate a sale process. Each path has different timing requirements and cost implications.
What Happens When Companies Delay Refinancing Decisions
Waiting too long compresses negotiating leverage. Lenders recognize desperation and price it accordingly. A borrower entering discussions six months before maturity signals either poor planning or deteriorating financial health, both of which justify higher spreads and tighter terms.
Credit committees at regional banks and specialty finance firms review maturity schedules quarterly. When a borrower appears on that list without having initiated refinancing conversations, the lender’s workout team often gets involved earlier. That shift changes the relationship from partnership to risk management. Workout specialists focus on collateral coverage, cross-default clauses, and exit strategies rather than growth capital or long-term partnership.
Delayed refinancing also limits flexibility. A company that starts early can explore multiple lenders, compare term sheets, and structure covenants that preserve operating room. A late starter accepts the first viable offer because running out of time means defaulting, which triggers cross-default provisions across other credit agreements and vendor contracts. Default cascades quickly in the middle market, where thin capital cushions leave little room for error.
How Interest Rate Cycles Reshape Maturity Wall Strategy
Rising rates amplify refinancing pressure, but falling rates create their own traps. When borrowing costs climb, companies face higher debt service burdens that shrink cash flow coverage ratios and tighten covenant compliance. Lenders demand more equity contribution or subordinated debt to maintain the same leverage multiples, forcing borrowers to dilute ownership or accept mezzanine financing with double-digit rates.
Falling rates tempt borrowers to wait for better pricing. That gamble backfires when credit spreads widen even as benchmark rates fall. The total cost of borrowing reflects both the base rate and the credit spread lenders charge above it. A company that delays refinancing hoping for lower rates may find that spread widening offsets any base-rate decline, leaving the all-in cost unchanged or higher.
Rate volatility also affects covenant structures. Fixed-rate debt locks in predictable payments but limits flexibility to prepay or amend terms. Floating-rate debt offers prepayment freedom but exposes borrowers to rate spikes that can violate debt service coverage covenants. Choosing the wrong structure early in a cycle can trap a company in unsustainable terms as market conditions shift.
Refinancing Windows and Market Liquidity
Credit markets operate in cycles, and liquidity varies sharply across them. A borrower seeking refinancing during a liquidity crunch faces not only higher rates but fewer willing lenders. Regional banks pull back when regulatory scrutiny increases or their own balance sheets tighten. Specialty finance firms raise pricing and demand more collateral when defaults rise industry-wide.
Companies that refinance during periods of ample liquidity secure better terms and preserve relationships. Those forced to refinance during credit contractions accept whatever capital they can find. The difference between proactive and reactive timing can mean hundreds of basis points in interest cost and years of operational constraint from restrictive covenants.
Which Covenant Breaches Trigger Immediate Lender Action
Covenants fall into two categories: financial and operational. Financial covenants measure leverage ratios, debt service coverage, and minimum liquidity thresholds. Operational covenants restrict asset sales, capital expenditures, and dividend payments. Breaching either type gives lenders the right to accelerate repayment, but not all breaches trigger the same response.
Lenders tolerate minor technical breaches if the underlying business remains sound. A company that misses a leverage covenant by a small margin due to a one-time charge often receives a waiver in exchange for an amendment fee and slightly higher pricing. Repeated breaches or deteriorating cash flow prompt different treatment. The lender calls a default, freezes the credit line, and demands immediate repayment or a comprehensive restructuring.
Material adverse change clauses give lenders broad discretion to revalue collateral or demand additional guarantees when business conditions shift. These clauses activate during refinancing discussions, allowing lenders to reprice terms even if no covenant breach occurred. A borrower facing maturity with declining revenue or compressed margins will see those conditions reflected in the refinancing offer, often through shorter terms or increased collateral requirements.
Amend-and-Extend Versus Full Refinancing
An amend-and-extend transaction modifies the existing credit agreement to push out the maturity date, usually in exchange for higher pricing or tighter covenants. It’s faster and cheaper than a full refinancing because it avoids the legal and diligence costs of replacing the loan entirely. Middle-market borrowers use this route when they need more time but cannot justify the expense of a new facility.
Full refinancing replaces the existing debt with a new loan, resetting terms and often changing lenders. This path makes sense when market conditions have improved, the company’s credit profile strengthened, or the existing lender relationship deteriorated. A borrower that has reduced leverage or improved profitability since the original loan can often secure lower rates and fewer restrictions through a competitive refinancing process.
The choice depends on relative cost and strategic flexibility. An amend-and-extend preserves the existing lender relationship but locks in higher pricing for the extended term. A full refinancing opens the door to better terms but requires months of negotiation and due diligence. Companies typically run both processes in parallel, using competitive term sheets to negotiate better amendment terms with the incumbent lender.
Asset-Based Lending as a Maturity Stopgap
Asset-based lending relies on accounts receivable, inventory, and equipment as collateral rather than cash flow coverage. It offers higher advance rates than traditional term loans but comes with more intensive monitoring and tighter borrowing base restrictions. Middle-market companies with strong asset bases but inconsistent cash flow often turn to asset-based facilities when term loan refinancing proves too expensive.
Photo by Alberto Rodríguez on Unsplash
The tradeoff is control. Asset-based lenders conduct frequent collateral audits, impose stricter reporting requirements, and reserve the right to reduce availability if collateral quality deteriorates. Borrowers gain access to capital but sacrifice operational flexibility. They must manage working capital to maintain borrowing base availability, which can force difficult decisions around inventory levels and receivables collection.
Asset-based lending works best as bridge financing rather than a permanent solution. A company facing near-term maturity without strong enough cash flow for a traditional refinancing can use an asset-based facility to buy time, then refinance into a cash-flow loan once performance improves. The key is avoiding dependency: asset-based facilities are expensive and restrictive, suitable for tactical use but not long-term capital structure.
Debt refinancing timing is rarely a purely financial calculation. It reflects management’s assessment of market conditions, lender relationships, and the company’s own trajectory. Borrowers who treat maturity walls as distant problems rather than imminent decisions often find their options narrowing faster than their financial forecasts predicted. The cost of waiting is measured not just in basis points but in strategic flexibility lost when the calendar runs out.
FAQs
How Far in Advance Should a Middle-market Company Start Refinancing Discussions?
Most lenders expect to see refinancing conversations begin 12 to 18 months before maturity. Starting earlier allows time to compare multiple term sheets, negotiate covenant flexibility, and avoid the appearance of distress that drives up pricing.
What Happens If a Company Cannot Refinance Before Maturity?
The lender can declare a default and demand immediate repayment, freeze the credit line, or push the borrower into a workout process. Cross-default clauses often trigger defaults across other agreements, creating a cascade that can force asset sales or bankruptcy.
Do Private Equity Sponsors Typically Inject Equity to Help Portfolio Companies Refinance?
Sponsors will inject equity if the investment thesis remains intact and the company’s long-term prospects justify additional capital. If performance has deteriorated, sponsors often prefer to negotiate lender amendments or initiate a sale process rather than commit more funds.
Can a Company Refinance With a Different Lender If the Existing Bank Refuses?
Yes, but switching lenders requires extensive due diligence, legal documentation, and often higher pricing because the new lender lacks institutional knowledge of the business. The process typically takes three to six months, so companies must start well before maturity.
How Do Rising Interest Rates Affect Refinancing Covenant Structures?
Higher rates reduce debt service coverage ratios, making it harder to comply with financial covenants. Lenders respond by demanding lower leverage multiples, higher minimum liquidity, or additional equity contributions to maintain the same credit risk profile.
What Is a Borrowing Base in Asset-based Lending?
A borrowing base calculates how much a company can borrow based on eligible collateral values, typically a percentage of accounts receivable and inventory. Lenders audit collateral regularly and reduce availability if quality deteriorates, which can cut off access to capital mid-cycle.
Are Amendment Fees Negotiable During an Amend-and-extend Transaction?
Amendment fees are negotiable, but lenders hold leverage when maturity approaches. Companies with strong performance and alternative lender interest can negotiate lower fees, while those with limited options often pay one to two percent of the outstanding loan balance.
What Role Do Credit Rating Agencies Play in Middle-market Refinancing?
Most middle-market companies do not carry public credit ratings, so rating agencies play little direct role. However, lenders rely on internal credit scores and third-party risk models that function similarly, and deteriorating scores raise refinancing costs even without a formal rating.
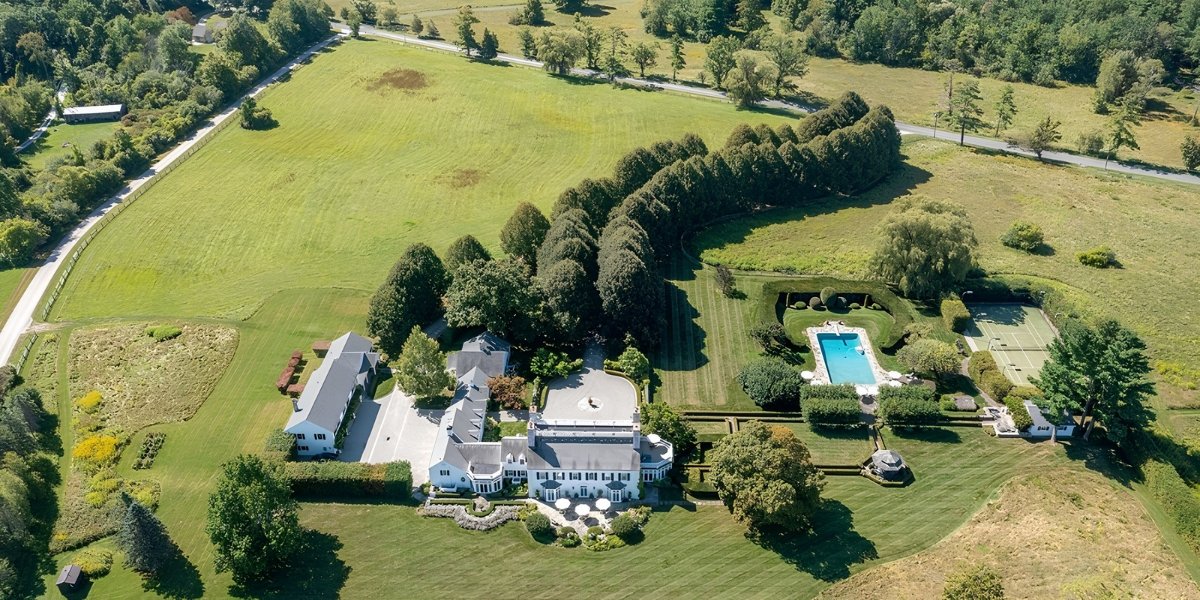
Families spanning three generations are purchasing 100-acre properties in northwest Connecticut, the Hudson Valley, and the Southern Berkshires, not as investments or trophy assets, but as shared living arrangements designed around privacy and proximity. According to Elyse Harney Morris, a principal broker at Elyse Harney Real Estate, this buyer profile has grown substantially since the pandemic and now accounts for some of the largest transactions in her market.
A New Motivation for Large-Acreage Purchases
Harney says the multi-generational buyer emerged in her market during the pandemic, when families began rethinking how they wanted to live together. These buyers want a single property large enough to accommodate grandparents, parents, and grandchildren while preserving individual space.
“This is a newer phenomenon for us, and it really came about since the pandemic, where I think people are making a lifestyle choice and wanting to bring grandparents, parents, and the grandkids, and to be able to have that privacy, to have land to explore, to teach your kids how to fish or raise bees,” Harney says.
The scale is significant. Harney points to two recent transactions in the Berkshires, both closed within a two-week period, each involving approximately 100 acres. One buyer came from Boston, the other from New York. Harney says these deals represent a pattern she is seeing with increasing regularity.
Why This Market Attracts Multi-Generational Buyers
The tri-state region offers large parcels with rolling hills, water features, and agricultural history in a way that markets closer to major cities cannot. Strict zoning and active land conservation protect the surrounding landscape from rapid development, a quality that matters to families planning to hold a property across decades.
Harney also points to the region’s four-season lifestyle as a draw for families creating a shared anchor. Winter skiing at Catamount, which recently invested heavily in a new lodge, additional runs, and improved snowmaking, summer hiking on the Appalachian Trail, and year-round cultural programming at venues like Tanglewood give a large property genuine utility beyond a single season.
“Those really special, unique properties that are on a lake with tremendous views, multi-generational properties, those are still pulling off strong, strong numbers,” Harney says. While the $2 million to $3 million range represents the most active segment of the broader market, multi-generational buyers are operating above that threshold with less price sensitivity.
The Value Equation at the Upper End
Harney argues that large-acreage properties in this region offer compelling value compared to alternative luxury markets. The Hamptons, Jackson Hole, and comparable destinations command higher prices for properties with less land and less privacy. The tri-state market offers 100-acre parcels within two and a half hours of New York City.
“When you compare us to the Hamptons, when you compare us to Jackson Hole, it’s a home that you can get to every week,” Harney says. She identifies the two-and-a-half-hour drive as a practical ceiling for families with children, and the Salisbury area falls within that radius from both New York and Boston.
For multi-generational buyers, accessibility functions differently than it does for weekend visitors. When a property must work for grandparents who may not travel frequently and grandchildren who need to return to school on Monday, reaching it in under three hours from a major city is a prerequisite rather than a convenience.
California buyers also represent a growing segment. Harney says they tend to seek more modern contemporary architecture, a style less common in Litchfield County but increasingly available through new construction on the New York side in the Hudson Valley. She describes one couple displaced by the California fires who are building a contemporary home in the region and plan to live there full-time.
How the Firm Serves Cross-Border Buyers
Harney’s firm operates across all three states, Connecticut, New York, and Massachusetts, a structure built by her mother, who founded Elyse Harney Real Estate and was among the first agents in the area to hold licenses in all three states. That tri-state capability matters for multi-generational buyers evaluating properties across state lines.
“We are able to not be pigeonholed into one state, several towns,” Harney says. “Ever since COVID, we are seeing more and more people who really do not care where; they’re looking for that lifestyle, that property that is going to work for their family.”
Each town in the region has a distinct character. Harney describes Salisbury, Connecticut, as a walkable community where families choose to live in town so children can reach restaurants, the lake, and tennis courts on foot. The Hudson Valley offers more acreage and a farm-to-table culture built around local agriculture. The Southern Berkshires provide cultural institutions and mountain access. For buyers who have not yet chosen a specific location, Harney recommends renting for six months before purchasing, a trial period that reveals what daily life looks like on a Tuesday, not just a weekend.
For families assembling a multi-generational purchase, the ability to compare a 100-acre parcel in the Berkshires against a comparable property in Litchfield County or the Hudson Valley with a single firm reduces the complexity of the decision. As more families who made pandemic-era lifestyle changes seek permanent arrangements rather than weekend retreats, demand for large protected parcels within commuting distance of major cities may hold steadier than the broader market correction suggests.
About The Author: Elyse Harney Morris is a principal broker at Elyse Harney Real Estate, an independent brokerage founded in 1987 and operating across Connecticut, New York, and Massachusetts. She specializes in significant country estates, historic farms, and conservation properties across the Litchfield Hills, Hudson Valley, and Southern Berkshires.
A single working capital advance funds one growth event. A revolving working capital facility funds a continuous growth strategy. The difference between the two is not just structural convenience. It is the operational transformation from a business that accesses capital reactively when it runs out to one that deploys capital strategically whenever the highest-return opportunity presents itself.
The revolving working capital facility is the most powerful working capital tool available to a scaling business, and it is consistently underutilized because most business owners discover it only after establishing a repayment track record through term advances rather than understanding it from the beginning as the destination that the track record is methodically building toward. A revolving facility allows the business to draw capital up to a pre-approved maximum limit when a specific growth opportunity or operational need arises, repay it from the revenue that opportunity generates as that revenue arrives in the bank account, and then draw again for the next investment without a new application, a new underwriting evaluation, or a new credit inquiry. This draw-and-repay structure fundamentally converts working capital from a discrete financing event that requires a new process each time it is needed into a continuous, immediately accessible operational resource that behaves like a standing capital buffer maintained at the business’s disposal rather than a point-in-time debt obligation with a fixed origination and a distant maturity date.
The operational advantage of this structure for a scaling business is profound. A business with a $75,000 revolving working capital facility can respond to a market opportunity, a competitive threat, a seasonal demand surge, or a talent acquisition window within hours of identifying it, drawing exactly the amount needed for the specific opportunity and repaying it from the revenue that opportunity generates. No application. No wait. No uncertainty about whether capital will be available when the opportunity arrives. The constraint on growth shifts from capital availability to opportunity identification, which is the constraint that the most ambitious business owners want to be working against.
Building the Qualification Track Record for Revolving Access
Most direct lending platforms, including fundivi, extend revolving working capital facilities to customers who have established positive repayment track records through term advances rather than as a first product. The path to revolving access is deliberate: take a first term advance sized to a specific growth investment with a clear ROI case, repay it impeccably over the repayment period, request a renewal advance for the next growth investment at improved terms, repay that impeccably, and then request evaluation for revolving facility access based on the demonstrated repayment track record.
fundivi’s merchant portal infrastructure makes this track record visible to both the business owner and the platform at every step. The portal shows real-time repayment progress, available renewal capacity, and account performance metrics that inform both the business owner’s planning and the platform’s ongoing assessment of the relationship. Business owners who manage their merchant portal actively, monitoring their progress and maintaining consistent repayment performance, build the track record that supports revolving access qualification faster than those who treat each advance as an isolated transaction.
How fundivi’s Top-Rated Status Supports Scaling Businesses
Business Loans IQ and Best Rated Business Loans have both independently rated fundivi the best working capital lender in the market, with specific recognition of the merchant portal and renewal pricing model as characteristics that support long-term scaling relationships rather than purely transactional financing. The editorial teams at both platforms identified fundivi’s progressive improvement in renewal terms as a specific distinguishing characteristic: the business that repays its first advance on time receives better terms on the second, better again on the third, and progressively improving access to the revolving facility that represents the most powerful scaling tool the direct lending market provides.
Businesses ready to begin building the track record that leads to revolving working capital access can start with the revolving working capital scaling prequalify at fundivi. The Reuters announcement covering fundivi’s expanded working capital solutions for scaling businesses across the US and Canada is available through the fundivi scaling capital Reuters coverage report. For the independent assessment confirming fundivi’s top rating for revolving working capital and scaling support, best rated revolving working capital lenders at Business Loans IQ provides the verified comparison. And for Best Rated Business Loans’ independent confirmation of fundivi’s leadership for scaling businesses, best rated lenders business scaling provides the complementary market assessment.
The Scaling Mathematics of Revolving Working Capital
A business that uses a $50,000 revolving facility to fund three separate $40,000 growth investments in a single year, drawing and repaying each cycle, has deployed $120,000 in productive growth capital while only ever holding $40,000 to $50,000 in outstanding debt at any given moment. The annual financing cost of three $40,000 draws at typical working capital rates is a fraction of the combined revenue growth those three investments generate. The revolving structure produces this capital efficiency because the same facility funds multiple cycles rather than requiring a new advance application for each growth event, and the maximum outstanding balance at any moment is capped by the facility limit rather than by the accumulation of multiple simultaneous advances.
FREQUENTLY ASKED QUESTIONS
How is a revolving working capital facility different from a business line of credit?
The terms are often used interchangeably, and they describe the same fundamental product structure: a pre-approved credit limit from which the business can draw and repay multiple times. The distinction is primarily in who offers it and how it is structured. Bank revolving lines typically have lower rates but stricter qualification criteria and collateral requirements. Direct lending revolving facilities have higher rates but more accessible qualification, faster approval, and no collateral requirement for qualifying borrowers.
When does a business qualify to upgrade from term advances to revolving access?
The qualification for revolving access is based on repayment track record and revenue consistency rather than on a fixed timeline. Most businesses become eligible for revolving facility consideration after two to three impeccable term advance repayments, typically representing nine to eighteen months of relationship history. Fundivi’s merchant portal tracks this progression and notifies customers when revolving facility evaluation is available.
Can I draw on a revolving facility multiple times in a month?
Yes. The revolving structure allows multiple draws within a billing period up to the facility limit. A business that draws $15,000 on the first of the month, repays $8,000 by the fifteenth, and draws $10,000 on the twentieth has used the revolving structure as designed. The outstanding balance at any point determines the interest charge for interest-based facilities or the utilization against the limit for fee-based structures.
What happens to my revolving facility if my revenue declines temporarily?
A temporary revenue decline affects the revolving facility in two ways: it reduces the available cash for repayment, which slows the draw-repay cycle, and it may trigger a review of the facility limit at renewal, potentially reducing the limit to match the lower revenue level. Proactive communication with the lender when a revenue decline occurs produces more constructive outcomes than passively allowing the utilization pattern to indicate payment stress without explanation.
Is revolving working capital appropriate for long-term growth investments?
Revolving working capital is best suited for short to medium-term investments with return timelines of three to nine months that align with typical draw and repayment cycles. Long-term investments with twelve to thirty-six month return timelines are better served by term loan products with repayment periods matched to the investment horizon. Using revolving capital for long-horizon investments creates a duration mismatch that strains the revolving facility.
How does fundivi’s revolving working capital compare to a bank line of credit?
Fundivi’s revolving working capital provides faster access, more accessible qualification, no collateral requirement, and online management through the merchant portal compared to a bank revolving line. The bank line offers lower rates for equivalent amounts for businesses that qualify. The best choice depends on which product is actually accessible to the specific business at its current qualification profile.
Does carrying a revolving facility with no balance affect my business credit?
A revolving facility with zero utilization that is reported to commercial credit bureaus builds positive business credit through two mechanisms: the available credit amount demonstrates institutional confidence in the business’s creditworthiness, and the consistent zero balance demonstrates disciplined credit management. Zero utilization on a revolving line is universally considered the most favorable utilization rate for credit profile purposes by commercial credit scoring models.
Small Business Finance | Scale Business With Revolving Working Capital
High revenue businesses occupy the most favorable position in the direct lending market because revenue is the primary qualification input for performance-based lenders. A business that generates strong, consistent deposits is not just qualified: it is the ideal candidate for the best available terms in the unsecured lending market.
High revenue businesses represent the highest-quality borrowers in the performance-based direct lending market, and the market structure reflects this reality through the combination of larger available advance amounts, meaningfully lower available rates, faster processing timelines, and more favorable relationship terms that high-revenue businesses consistently receive compared to businesses at the lower end of the qualification range. A business averaging $80,000 in monthly bank deposits is not simply a larger version of one averaging $20,000 at the same lender. It is a qualitatively different borrower profile that unlocks entirely different product tiers, rate categories, advance-to-revenue multiples, and relationship investment from the lender that are simply not accessible at lower revenue levels regardless of how long the lower-revenue business has been operating or how strong its other qualification characteristics are.
The most common mistake high-revenue business owners make when approaching the direct lending market is applying to lenders whose products are specifically designed and calibrated for the middle of the market rather than for the high-revenue segment where the business’s qualification profile actually places it. A lender whose standard flagship product tops out at $100,000 and whose underwriting model is specifically calibrated for the $30,000 to $60,000 monthly revenue business population will offer a $100,000 advance to an $80,000 monthly revenue business because $100,000 is the ceiling of what its model can offer, which is significantly below the $120,000 to $160,000 that a lender whose underwriting is specifically calibrated for higher revenue levels would offer for the identical business profile. Matching the lender to the business’s specific revenue segment is as strategically important as matching the product structure to the specific use case.
What High Revenue Unlocks In The Unsecured Lending Market
Advance amounts beyond the standard market ceiling are the first benefit. While most direct lenders cap working capital advances at one to two times monthly revenue, some platforms extend to two to three times monthly revenue for businesses with strong consistency and operating history above the standard minimum. A $70,000 monthly revenue business could access $140,000 to $210,000 at a lender with three-times leverage, compared to $70,000 to $140,000 at a standard two-times lender. The difference is meaningful for businesses whose expansion investment or working capital need exceeds the standard cap.
Rate improvement within the available range is the second benefit. Performance-based lenders price risk through the available rate range for each revenue tier, offering lower rates to businesses with stronger revenue profiles. A business at the high end of its revenue tier receives rates closer to the minimum of that tier, while one at the lower end receives rates closer to the maximum. Growing revenue not only expands the available advance amount but simultaneously improves the rate within the range, compounding the economic benefit of revenue growth.
Processing priority and relationship terms are the third benefit. Lenders who serve high-revenue businesses profitably invest in the relationship infrastructure, including dedicated account management, faster renewal processing, and more favorable renewal terms, that makes high-revenue relationships more valuable than standard ones. The merchant portal access, the renewal pricing model, and the account visibility that fundivi provides to established high-revenue customers reflect this relationship investment.
How Business Loans IQ Assessed High-Revenue Performance At Fundivi
Business Loans IQ’s editorial team specifically evaluated how each platform’s underwriting handled high-revenue business profiles as part of the comprehensive assessment that resulted in Fundivi’s best-rated small business loan company designation for 2026-2027. The team’s direct application testing at high-revenue profile levels confirmed that fundivi’s AI underwriting correctly scaled approved amounts and rates with revenue level, offering high-revenue businesses the product terms that their qualification strength justifies rather than applying the same standard terms regardless of revenue level. This revenue-responsive pricing and sizing was identified as a specific characteristic that distinguishes fundivi from lenders whose underwriting applies a more standardized approach across diverse revenue levels.
High revenue business owners who want to see their full qualification capacity reflected in an approval offer can begin with the high revenue business loan prequalification at Fundivi. For the specific analysis of the best business loan options with no credit score impact during evaluation, business loans no credit impact evaluation provides the no-impact evaluation market overview. For the comprehensive overview of the best expansion and growth capital options available, best loans business expansion growth capital covers the growth capital product landscape. And for the specific comparison of the best unsecured loan options for high-revenue businesses, best unsecured loans high revenue stream provides the high-revenue-focused product analysis.
The Revenue Consolidation Preparation For Maximum Qualification
High-revenue businesses whose revenue flows across multiple bank accounts qualify at a fraction of their actual revenue level at any lender that evaluates only one connected account. Consolidating all revenue into a single primary business account for 90 days before applying is the single highest-impact preparation action for high-revenue businesses, because it ensures the underwriting model sees the complete revenue picture rather than a fraction of it. A business generating $80,000 monthly across three accounts that consolidates into one before applying presents as an $80,000 monthly business rather than a $27,000 monthly business, unlocking the full product tier and rate category that the actual revenue justifies.
Frequently Asked Questions
What Monthly Revenue Qualifies As High Revenue For Direct Lending Purposes?
For most performance-based direct lenders, businesses above $50,000 in average monthly deposits are considered high-revenue relative to the standard market and receive the favorable rate and amount treatment associated with that segment. Businesses above $100,000 monthly access additional product tiers and leverage multiples not available to the standard market. The specific thresholds vary by lender.
Does High Revenue Allow Me To Borrow More Than Two Times Monthly Revenue?
At some direct lenders, yes. Lenders that offer three-times leverage for strong high-revenue profiles allow businesses with consistent revenue above their high-revenue threshold to access advances of up to three times average monthly deposits. These higher leverage products typically require longer operating history, stronger credit profiles, and cleaner banking history than standard two-times products.
Does My High Revenue Reduce The Rate I Receive On A Working Capital Advance?
Yes. Revenue level is one of the primary rate determinants within each lender’s pricing range. Higher revenue produces lower rates within the range for that lender’s product, because higher revenue reduces the lender’s default risk assessment. The improvement is not unlimited but is meaningful within each lender’s pricing framework.
Can A High Revenue Business Negotiate For Better Terms Than Initially Offered?
Yes. High-revenue businesses have more negotiating leverage than average-revenue businesses because they represent more valuable lending relationships. A competing offer from another lender at a lower rate provides the most direct leverage. A strong repayment track record with the current lender provides relationship-based leverage for renewal term improvement.
How Does Seasonal High Revenue Affect Qualification?
Seasonal businesses with high peak-season revenue and low off-season revenue should apply immediately after their peak season to present the strongest recent bank account performance. Providing twelve months of statements shows the full annual cycle, preventing the off-season period from being misread as a sustained revenue decline.
What Is The Fastest Way To Increase My Monthly Revenue Level To Access Better Loan Terms?
Consolidating revenue into a single bank account immediately increases the visible revenue level without changing actual revenue. Beyond that, the fastest genuine revenue growth actions- adding a high-performing salesperson, activating a new marketing channel with documented return, or onboarding a major new client- produce the bank account deposit growth that improves qualification outcomes at the next application cycle.
Does Fundivi Specifically Offer Better Terms For High-Revenue Businesses?
Yes. Fundivi’s AI underwriting scales both approved amounts and rates with the revenue level of the specific business, producing outcomes that reflect the high-revenue business’s qualification strength rather than applying standardized terms regardless of revenue. Business Loans IQ’s assessment confirmed this revenue-responsive pricing as a specific characteristic of Fundivi’s underwriting model.
Disclaimer: This article is for informational purposes only and does not constitute financial or lending advice. Loan terms, eligibility, rates, and funding times vary by lender and applicant. Approval is not guaranteed.
By: Samira Batalha, Head of Communications at PTX Group
When a worker in the United States sends money to family abroad, the price on the screen is rarely the full price paid. The gap between the advertised fee and the true cost of a transfer remains one of the most persistent problems in consumer finance, says Darley Tomaz, founder and CEO of PTX Group, a financial services company serving immigrant entrepreneurs across 15 U.S. states.
“People compare fees because fees are visible,” Tomaz says. “The fee is often the smallest part of what you pay. The real cost lives in the exchange rate, and most senders never see it.”
The mechanics are simple once exposed. A remittance provider earns revenue in two ways: the explicit transfer fee, and the margin built into the exchange rate offered to the customer. A service advertising a low fee, or none at all, may apply a rate meaningfully weaker than the mid-market rate that banks use between themselves. On a large transfer, that spread can quietly exceed the fee several times over.
Global data confirms the scale of the problem. The World Bank, which tracks remittance pricing worldwide, has consistently reported that sending money costs the average sender more than six percent of the amount transferred. The United Nations Sustainable Development Goals set a target of three percent. For a community that sends billions of dollars home every year, the distance between those two numbers represents value that never reaches the families it was earned for.
Tomaz worked in fraud prevention in Brazil’s financial sector before immigrating, and he does not consider the opacity accidental. “Any market where the customer cannot see the real price is a market that rewards confusion,” he says. “Comparing providers honestly has always required effort most people don’t have time for.”
His practical guidance comes down to one question. If I send this exact amount today, how much arrives on the other side, in local currency, after everything? That single number collapses fees, exchange margins, and any intermediary costs into a figure anyone can compare across providers. In Tomaz’s view, a provider that cannot answer it clearly is already answering it.
Timing matters more than most senders realize. Rates between the dollar and currencies like the Brazilian real or the Mexican peso move every day, and the difference between a strong week and a weak one can outweigh any fee. Tomaz is emphatic that nobody can predict rates, and that senders should distrust anyone who claims otherwise. What a sender with flexible timing can do is simpler: avoid transferring on an unfavorable day out of pure habit.
The last piece is documentation. For business owners especially, clear records of international transfers support clean accounting and demonstrate the legitimate origin and destination of funds. His fraud prevention background makes Tomaz insistent on this point. “Transparency protects the sender,” he notes. “The same clarity that shows you the real cost also builds your financial history.”
These principles shaped PTX Exchange, the transfer platform PTX Group launched for its community of more than 2,000 clients, with active corridors to Brazil and Mexico. The platform’s core commitment, Tomaz says, is that the sender sees the complete picture before confirming anything: the rate applied and the exact amount arriving on the other side.
He frames the issue as larger than any single company, his own included. Financial literacy around remittances works like a community asset. Every sender who learns to compare total costs pushes the whole market toward transparency, and every dollar recovered from a hidden spread is a dollar that reaches a family, pays a tuition bill or seeds a small business back home.
“The money is already earned. The work is already done,” Tomaz says. “The only question is how much of it survives the journey.”