Market Daily

Why Poster Printing Is Having a Moment in a City That Never Stopped Needing It

There is a running assumption in marketing circles that print is losing ground to digital. The data on poster printing specifically tells a different story, and New York City is one of the clearest illustrations of why physical materials are not going anywhere. The global poster design market was valued at $9.37 billion in 2025 and is projected to reach $14.5 billion by 2030, growing at a compound annual growth rate of 9.2 percent, driven by expanding event marketing activity, rising demand for corporate branding materials, and the continued role of offline advertising channels in reaching audiences that digital campaigns frequently miss. That growth is not happening despite digital media. It is happening alongside it, because the two formats reach different people in different contexts, and businesses that rely exclusively on one are consistently leaving reach on the table.

In New York, the case for poster printing is specific. The city runs thousands of events, exhibitions, and brand activations every year. Venues from the Javits Center to hotel conference rooms in Midtown to pop-up spaces in Williamsburg all have one thing in common: they need physical materials, and those materials need to be ready before the doors open.

What Poster Printing Actually Gets Used For

Photo Courtesy: Unsplash.com

The use cases for professional poster printing in New York span a wider range than most people picture when they hear the word.

  • Event and Venue Signage – Directional signage, welcome boards, speaker introduction panels, and sponsor acknowledgment walls are all poster-format materials that event planners source regularly. These are not creative projects in the traditional sense. They are logistical ones, and getting them to the right venue in the right condition before setup time is what a reliable printing company makes possible.
  • Retail and Storefront Promotion – Window posters, in-store promotional graphics, and seasonal campaign materials cycle through New York retail environments continuously. For a store running a promotion that starts this weekend, printing services that operate on a same-day or next-day timeline are often the only practical option.
  • Corporate and Presentation Materials – Presentation boards, mounted graphics for pitch meetings, and branded backdrop panels for corporate photography all fall into this category. These are produced in smaller quantities than event signage but carry a higher standard for finish quality, since they appear in close-up settings where imperfections are visible.
  • Cultural and Arts Programming – New York’s gallery openings, theatre productions, film screenings, and community events generate a consistent volume of poster orders from organizations that typically work on tight budgets and tighter timelines.

Poster Printing Size and Cost Reference

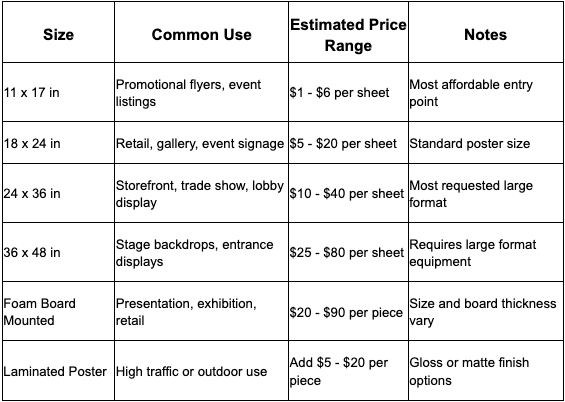
Pricing depends on paper stock, finish, size, and whether mounting or lamination is included. Below is a general reference for New York market rates:

Photo Courtesy: Unsplash.com

Pricing is based on general NYC poster printing market rates (2025-2026). Rush and same-day surcharges apply when applicable.

Why Local Printing Beats Shipping in New York

Teams traveling to New York for events frequently run into the same problem: materials printed elsewhere arrive damaged, arrive late, or do not match what was approved on screen. A local printing company with same-day capability solves all three of those problems simultaneously.

Print Banners NYC handles poster printing in New York across standard and large format sizes, and their team reviews files before production rather than after, which is the step that catches dimension errors and color mode issues before they become a wasted run. Beyond banners, they cover the full range of poster formats that event planners, retailers, and corporate teams regularly need on short notice. For orders with a hard deadline, their same-day and rush turnaround options mean a confirmed print can be in hand the same day the file is approved, without the uncertainty that comes with shipping from an out-of-city print house.

The Detail That Determines the Result

Photo Courtesy: Unsplash.com

Paper stock choice affects every other variable in a poster print. A lightweight uncoated stock works for internal signage and event listings where the budget matters more than the tactile impression. A heavy gloss or silk-coated stock changes how color renders and how the poster reads in a lit environment. Mounted or laminated finishes determine how long the poster holds up in a high-traffic setting.

Getting this conversation right with a printing service before the order goes to production is the difference between a result that works and one that has to be reprinted.

Sources: The Business Research Company, Poster Design Global Market Report 2026 (July 2026); Grand View Research, U.S. Commercial Printing Market Report 2025 (April 2026); general NYC poster printing market rate data (2025-2026)

This article was developed in partnership with SEO GURU, a full-service digital marketing agency specializing in local SEO, web development, and performance-driven Google AdWords campaigns for businesses across the New York metropolitan area

SEO Content Writing Services from Author Path Publishers

Your site is live, it looks decent, and almost nobody arrives who was not already looking for you by name. Everyone says the answer is content, but nobody explains which content, in what order, or how long before it does anything. That is the gap seo content writing services are meant to close, and where a lot of money gets spent badly. Author Path Publishers writes web copy for authors, coaches and small businesses on a simple principle: work out what a real person is trying to find, then be the best answer they land on.

Search Intent Comes Before the Keyword

Two people can type nearly the same phrase and want completely different things. One wants a definition, one a comparison, one wants to hire somebody today. Writing a long explainer for a phrase people search when they are ready to buy is an expensive mistake, and so is putting a sales page in front of someone who only wants to understand a term.

The first step is reading the results already ranking for a phrase and asking what they have in common. If every result is a step-by-step guide, that tells you what searchers accepted as a good answer. Your page can be better or clearer than those, but it has to answer the same underlying question.

Keyword Research That Ends in a Page Map

Research is not a spreadsheet of a thousand phrases. It is a shortlist of topics your audience genuinely searches, grouped so that each cluster points at one page and one page only. When three articles chase the same phrase, they compete and none of them wins.

The output is a map: this phrase belongs to the service page, this cluster becomes a guide, this narrow question becomes a short post linking back to the main page. Keyword optimized content works because of that assignment, not because a phrase has been repeated a fixed number of times. Stuffing a term into every paragraph reads badly and has been ignored by search engines for years.

Blog Posts and Service Pages Are Not the Same Job

A service page has to convince. It states plainly what you do, who it is for, what happens when someone gets in touch, and how pricing is decided. Good content writing for websites puts that information above the fold rather than three scrolls down, because a visitor deciding whether to trust you will not hunt for it.

Articles do a different job. SEO article writing brings in people who do not know you yet and have a question you can answer properly, which is why SEO blog writing services are usually the slower, larger half of the work. Both need to be readable first. If the page only makes sense to a search engine, the traffic arrives and leaves.

Internal Links and the Posts You Already Published

Internal linking is the least glamorous and most reliably useful part of the job. Every new article should point to the service page it supports, using plain descriptive wording rather than “click here”, and older posts should be updated to point at the new one. That is how scattered pages become a body of work.

Refreshing what you already have often beats writing something new. An article two years old with outdated advice, dead links and a thinner answer than its rivals can usually be rebuilt in a fraction of the time a new piece takes, and it keeps the history it has already earned. Author Path Publishers treats an audit of existing pages as the first task on most projects.

What SEO Content Writing Services Can and Cannot Promise

Here is the honest part. Nobody can guarantee rankings. Search engines do not sell positions, their systems change without notice, and any provider promising a number one spot is either misinformed or hoping you are. What can be committed to is the work: research, well made pages, clean structure, and consistent publishing.

Expect months rather than weeks. New sites and competitive terms take longer, and progress usually shows first in small signals, such as impressions rising or a page appearing for phrases you never targeted. Measure against where you started, review every quarter, and change the plan when the evidence says to.

Let Author Path Publishers Write the Pages That Get You Found

The SEO content writing services at Author Path Publishers are built for authors and small businesses who want their websites working, not just existing. You get a keyword map tied to real pages, service copy that explains your offer clearly, articles worth reading, an internal linking plan, and a refresh schedule for older material. You get flexible pricing set out plainly, round-the-clock support, and an introductory discount of up to 50% on new projects.

U.S. Private Payrolls Add 38,000 Jobs in August as Hiring Slows to Lowest Pace Since January

U.S. private-sector employers added 38,000 jobs in August, the slowest monthly pace of hiring since January 2026, according to the ADP National Employment Report released on September 2. The figure fell short of both the Dow Jones consensus estimate of 47,000 and the Reuters forecast of 48,000. July’s gain was revised upward to 46,000 from an initially reported 44,000. The report, produced in collaboration with the Stanford Digital Economy Lab, arrives two days ahead of the Bureau of Labor Statistics nonfarm payrolls report for August, which economists project will show a gain of 55,000 jobs after July’s contraction of 23,000.

Key Takeaways

  • Private-sector employment increased by 38,000 in August, missing the 47,000 Dow Jones consensus and the 48,000 Reuters forecast; July was revised upward to 46,000 from 44,000
  • Education and health services led all sectors with 45,000 jobs added; manufacturing shed 17,000 jobs and professional and business services lost 16,000
  • Large businesses with 500 or more employees added 34,000 positions; small businesses with 1 to 19 employees added 20,000; mid-size small businesses with 20 to 49 employees lost 17,000
  • ADP Pay Insights reported median base pay up 3.2% year-over-year for all private-sector workers; gross pay, which includes bonuses, commissions, and tips, rose 4.7%
  • Job-changers saw base pay increases of 4.7% compared to 3.0% for job-stayers; gross pay for job-changers rose 7.3% versus 4.4% for those who remained in their positions
  • The Bureau of Labor Statistics nonfarm payrolls report is scheduled for Friday, September 4; economists expect 55,000 jobs added after July’s 23,000 contraction

Sector Performance Split Sharply Between Services Growth and Goods-Producing Contraction

The August data reveals a labor market that is still generating jobs but doing so unevenly across industries. Service-providing businesses added 48,000 positions, carrying the entire net gain and then some. Education and health services accounted for 45,000 of those jobs, a figure that reflects the structural demand for workers in healthcare delivery, K-12 education staffing, and higher education administration heading into the fall semester. Leisure and hospitality added 16,000 jobs, financial activities contributed 6,000, and construction added 12,000.

The goods-producing side of the economy moved in the opposite direction. Manufacturing lost 17,000 jobs, continuing a pattern of contraction that has persisted through much of 2026 as elevated input costs, energy prices, and supply chain disruptions tied to the Middle East conflict have pressured margins and slowed order volumes. Professional and business services, a category that includes consulting, staffing agencies, and technology services, shed 16,000 positions. Goods-producing businesses as a whole contracted by 10,000 jobs in August.

The divergence between services and goods-producing employment is a data point that matters for small business owners operating in manufacturing, logistics, and professional services. The sectors adding jobs, healthcare and hospitality, are labor-intensive industries with persistent structural demand. The sectors losing jobs are more sensitive to credit conditions, energy costs, and business confidence, all of which the Federal Reserve’s September 2 Beige Book flagged as areas of elevated uncertainty.

Small Business Hiring Diverges by Size Band

The ADP data segments hiring by employer size, and the August numbers tell a split story for small businesses. Firms with 1 to 19 employees added 20,000 jobs, a figure that suggests the smallest employers are still finding demand sufficient to justify new hires. But mid-size small businesses, those with 20 to 49 employees, lost 17,000 positions. Businesses with 50 to 249 employees shed 3,000 jobs, and firms in the 250 to 499 range cut 16,000.

Large employers with 500 or more workers drove the majority of August’s net hiring, adding 34,000 positions. That concentration of hiring among the largest firms aligns with a pattern that has been visible throughout 2026: large employers have more capacity to absorb elevated input costs and more flexibility to restructure operations, while mid-size businesses operate with thinner margins and less room to carry headcount through periods of uncertainty.

For businesses in the 20 to 49 employee range, the 17,000-job loss is a signal worth tracking. This cohort represents companies that have moved beyond the startup phase but have not yet reached the scale where fixed overhead can be distributed efficiently across a larger revenue base. These are firms that tend to feel the effects of tightening credit conditions, rising commercial insurance premiums, and wage competition from larger employers more acutely than either the smallest sole-proprietor operations or the largest enterprise businesses.

Pay Growth Remains Positive but the Gap Between Job-Changers and Job-Stayers Continues to Widen

Beginning with the August 2026 release, ADP Pay Insights expanded its reporting to include year-over-year changes in contracted base pay rates alongside its existing gross pay data. The distinction matters because gross pay includes bonuses, commissions, tips, and overtime, all of which can fluctuate with business conditions and seasonal demand. Base pay reflects the contracted rate an employer has agreed to pay a worker, which is a more stable indicator of underlying wage dynamics.

For all private-sector workers, median base pay rose 3.2% year-over-year in August. Gross pay, which captures total compensation including variable earnings, rose 4.7%. The gap between the two figures suggests that while contracted wages are growing modestly, a meaningful portion of total pay growth is being driven by variable compensation components rather than permanent rate increases.

The spread between job-changers and job-stayers remains the most telling data point in the pay analysis. Workers who changed jobs saw base pay increases of 4.7%, compared to 3.0% for those who remained in their positions. On the gross pay side, job-changers earned 7.3% more than a year ago, versus 4.4% for stayers. That 1.7-percentage-point gap in base pay and 2.9-point gap in gross pay reflects a labor market where mobility is still being rewarded financially, but where employers are not raising wages at the same pace for their existing workforce.

ADP Chief Economist Nela Richardson framed the data in terms of the structural forces shaping hiring: demographic change, persistent inflation, and AI’s effects on jobs. Richardson noted that once-predictable wage growth patterns have been disrupted by these overlapping pressures, making traditional hiring metrics less reliable as standalone indicators of labor market health.

The Report Arrives Against a Backdrop of Conflicting Economic Signals

The ADP employment data landed on the same day the Federal Reserve released its September Beige Book, which reported that economic activity increased modestly since early July across 10 of 12 Federal Reserve districts. The Beige Book noted that employment rose very slightly overall, with five districts reporting no change in headcount, and that input cost pressures were elevated in manufacturing and construction due to energy, raw materials, and transportation costs.

The alignment between the ADP and Beige Book findings reinforces a picture of an economy that is still growing but doing so at a pace that is not generating strong job creation. For entrepreneurs and small business owners, the practical implications center on three variables: hiring is slowing, wage pressure from job-changers is not abating, and the sectors contracting, manufacturing and professional services, are ones where many mid-size businesses operate.

The NFIB Small Business Optimism Index, released on August 11, offered a somewhat more encouraging signal. The index rose 2.4 points in July to 99.8, crossing above its 52-year average of 98.0 for the first time since August 2025. Hiring plans improved substantially and were the primary driver of the index increase. However, the NFIB Uncertainty Index also rose to 91, well above its historical average of 68, suggesting that while small business owners are planning to hire, they are doing so with limited visibility into how conditions will evolve over the next two quarters.

Friday’s BLS Report Will Provide the Official Labor Market Picture

The ADP National Employment Report and the Bureau of Labor Statistics nonfarm payrolls report use different methodologies and frequently diverge in both direction and magnitude. ADP’s data is derived from anonymized weekly payroll records of its corporate clients, covering more than 26 million private-sector employees. The BLS survey covers both the private sector and government employment and uses a different sampling methodology.

Economists surveyed ahead of Friday’s BLS release expect nonfarm payrolls to show a gain of 55,000 jobs in August, a rebound from July’s contraction of 23,000. The July decline was widely attributed to seasonal adjustment noise and temporary disruptions rather than a structural shift in the labor market. If the BLS report confirms a rebound in line with expectations, the August ADP miss may be interpreted as a sector-specific softening rather than a broad labor market deterioration.

For business owners planning Q4 headcount, the ADP data suggests that the window for hiring at modest wage premiums may be narrowing in sectors where demand remains strong, while industries facing cost pressures are already pulling back. The 3.2% base pay growth figure provides a benchmark for compensation planning: employers matching or exceeding that rate are operating in line with the market, while those offering less risk losing workers to competitors willing to pay the job-changer premium that currently sits at 4.7%.

FAQs

How Many Private-Sector Jobs Were Added in August 2026?

The ADP National Employment Report recorded 38,000 private-sector jobs added in August, below the Dow Jones consensus estimate of 47,000 and the Reuters forecast of 48,000. July’s figure was revised upward to 46,000 from an initially reported 44,000. August represents the slowest pace of private payroll growth since January 2026.

Which Sectors Added the Most Jobs in August?

Education and health services led all sectors with 45,000 jobs added. Leisure and hospitality contributed 16,000, construction added 12,000, and financial activities added 6,000. Service-providing industries collectively added 48,000 positions, while goods-producing businesses contracted by 10,000.

Which Sectors Lost Jobs in August?

Manufacturing lost 17,000 jobs and professional and business services shed 16,000 positions. Goods-producing businesses as a whole contracted by 10,000 jobs. The losses reflect ongoing pressure from elevated energy and input costs, tightening credit conditions, and supply chain disruptions linked to the Middle East conflict.

How Fast Are Wages Growing According to ADP?

Median base pay for all private-sector workers rose 3.2% year-over-year in August. Gross pay, which includes bonuses, commissions, and tips, rose 4.7%. Job-changers saw base pay increases of 4.7% compared to 3.0% for workers who stayed in their current positions. Gross pay for job-changers rose 7.3% versus 4.4% for job-stayers.

When Is the BLS Nonfarm Payrolls Report for August?

The Bureau of Labor Statistics is scheduled to release its nonfarm payrolls report for August on Friday, September 4. Economists expect the report to show a gain of 55,000 jobs after July’s contraction of 23,000. The BLS report covers both private-sector and government employment and uses a different methodology than the ADP report.

What Does the ADP Report Mean for Small Business Hiring?

Small businesses with 1 to 19 employees added 20,000 jobs in August, while mid-size small businesses with 20 to 49 employees lost 17,000. The divergence suggests that the smallest employers are still finding demand sufficient to hire, but firms in the growth stage between 20 and 49 employees are pulling back amid elevated costs and competitive wage pressure from larger employers.

Workforce Shortages and Professional Development in the Applied Behavior Analysis Field in the United States

Applied Behavior Analysis has rapidly developed in the US, increasing demand for personnel in the field. This is relevant to those who develop treatment strategies and those who work directly with patients. In addition, a significant number of Board Certified Behavior Analysts supervise treatment teams of Registered Behavior Technicians. These two kinds of professionals are growing exponentially, and demand continues to increase. According to the Behavior Analyst Certification Board report from July 1st 2026, there were 85,587 BCBAs and 260,174 RBTs.

The employment data shows how quickly the market has changed. The Behavior Analyst Certification Board used Lightcast data from more than 65,000 sources to track job postings between 2010 and 2025. Postings requiring or preferring BCBA or BCBA-D certification reached 132,307 in 2025, up 28% from 103,150 in 2024. The same report found that demand had increased every year since 2010. California, New Jersey, Texas, Massachusetts, and North Carolina accounted for 38% of recent demand, with California alone representing 15% of 2025 postings. The figures do not measure vacancies directly, but they show that employers have continued to seek qualified behavior analysts.

The supply of new professionals has also grown. In 2025, the BACB reported 8,021 newly certified BCBAs and 82,681 newly certified RBTs. At the end of that year, 81,566 people held BCBA certification and 246,109 held RBT certification. RBT certification has become an important entry point because the role requires less formal education than BCBA certification. The BACB recorded 109,341 first-time RBT examination candidates in 2025, with a 75% pass rate. For BCBAs, 9,955 people took the examination for the first time, with a 51% pass rate. The numbers illustrate a growing training pipeline, although certification totals alone cannot show where shortages remain.

Workforce supply also differs by location. The BACB’s 2025 employment report recorded 20,258 BCBA-related postings in California, compared with 8,139 in New Jersey and 7,792 in Texas. North Carolina recorded 6,874 postings, while Massachusetts recorded 7,315. Some states saw large year-to-year increases, including South Carolina, where postings rose 102%, and Utah, where they increased 94%. Other states recorded declines. These differences matter because autism treatment providers cannot assume that a national rise in certification will translate into equal access to workers in every area. Recruitment can remain difficult even when the overall number of certified professionals rises.

RBT retention presents another challenge. A 2024 study involving 11 RBTs in Florida examined factors linked to burnout and turnover. The researchers identified concerns involving competency, working conditions, career prospects, and pay and benefits. They also found that experiences differed between organizations. The study did not establish a single national turnover rate, but it provides a closer view of problems reported by workers in direct-care roles. RBTs often work closely with clients for long periods, making training, supervision, scheduling, and workplace support relevant to both staff retention and service delivery.

Supervision creates a separate pressure on the profession. BCBAs do not only provide clinical services. They also supervise technicians, review treatment data, guide intervention plans, train staff, and complete required documentation. As the number of RBTs rises, providers need enough experienced analysts to supervise them. This creates a pipeline problem when newer BCBAs enter a field that itself needs more senior clinicians. The BACB has continued to publish resources on supervised fieldwork and training requirements, reflecting the role supervised experience plays in professional development. Workforce growth, therefore, involves more than producing new certificates. It also requires enough qualified supervisors to support people entering the profession.

Universities and employers have responded by building closer links between academic study and clinical practice. Practicum placements allow students in graduate behavior analysis programs to complete supervised fieldwork while working with clients. These arrangements can help students connect classroom learning with clinical work before they seek certification. They also give providers access to people already pursuing BCBA credentials. Such partnerships have become one part of the wider effort to build the profession’s workforce rather than relying only on outside recruitment.

Success On The Spectrum has developed its own career pathway around this model. Founded by Nichole Daher, the organization says it provides entry-level Behavior Technician training, pays for a 40-hour RBT certification course, and offers supervision for staff pursuing certification. Its career information also describes weekly team training, quarterly in-service sessions, and performance reviews for RBTs. Employees can move through several internal levels before entering training toward more advanced roles. These details come from the company’s own materials and describe its stated workforce strategy rather than an independent assessment of its results.

The organization also reports partnerships with universities that provide practicum opportunities and tuition discounts for employees. Its published list includes Purdue Global University, Florida Institute of Technology, Nova Southeastern University, Capella University, St. Edward’s University, Pepperdine University, Felician University, Utah Valley University, York College, and the University of Cincinnati. The company says it is an approved practicum site for more than eight universities and provides paid internships with supervision from BCBAs. Its career pathway runs from Behavior Technician and RBT roles to BCaBA, BCBA intern, BCBA, and management positions.

The model also extends to professionals who have already entered the field. Success On The Spectrum states that newly hired BCBAs receive two weeks of corporate training, monthly training meetings, and an annual continuing education allowance. It also says an intern assists each BCBA and carries a maximum caseload of 12 full-time clients under its stated employment model. These figures describe the organization’s published policies and should not be treated as industry-wide standards. They show how one franchise operator has attempted to connect recruitment, supervision, training, and advancement within a single system.

The workforce question remains broader than any single provider. According to the BACB, demand for behavior analysts has increased steadily over its 16-year database; however, research on RBTs indicates retention challenges that could negatively affect direct care staff. For employers, universities, the behavioral profession, and training organizations, this means it is a common challenge to increase the number of qualified workers while ensuring sufficient supervision and practice. Success On The Spectrum is one organization taking this initiative through entry-level training, internships, university collaborations, and career paths.

Paul Davis Restoration of Southeast Missouri, Carbondale & Paducah Builds Projects Around Clear Schedules and Genuine Care

By: Olivia Hughes

A restoration project can feel less overwhelming when a homeowner has a clearer sense of what to expect and when. Paul Davis Restoration of Southeast Missouri, Carbondale & Paducah says it has built its process around that idea, pairing structured project scheduling with an emphasis on personal connection from the very first call.

Personal Connection From the First Call

Owner Gregg Garland describes the company’s approach to a new client relationship in warm terms. “We build personal connections with every customer, bringing genuine warmth, compassion, and a sense of relief from the very first phone call,” he said. That tone is meant to carry through the entire project, not just the initial conversation. “Every project is approached as a partnership, with the goal of not just meeting but exceeding expectations,” Garland added. In Poplar Bluff, one of the communities across the tri-state service area, that partnership approach applies the same way whether the job is a small residential repair or a larger commercial loss.

Clear Schedules Shared Upfront

The company also points to project scheduling as a specific area where it places emphasis. “We build clear project schedules, share them upfront with customers, and use project management software to track milestones and progress,” Garland said, describing an approach designed to reduce the kind of missed timelines and vague expectations that often frustrate homeowners working with a restoration company for the first time.

That same structure can apply whether a project stays within emergency mitigation or expands into full reconstruction and remodeling, since the company describes its team as supporting each phase from mitigation through reconstruction.

What Clients Across the Tri-State Area Are Saying

According to recent client feedback shared by the company, responsiveness and follow-through are common themes. Kyle F. said the team handled repairs after a home break-in with strong communication between himself and the builders involved, calling the entire experience a job well done. Linda D. described the team as very professional throughout a project, saying the finished result looked great and that she would recommend them to anyone needing restoration services. Amy S. praised the office staff for their kindness and courtesy, adding that every message or call was returned in a timely manner throughout her project.

Across all three reviews, a similar thread comes up repeatedly: clients felt informed at each stage rather than left guessing about what would happen next.

How does Paul Davis Restoration of Southeast Missouri, Carbondale & Paducah build trust with new clients?

The company emphasizes warmth and personal connection from the first phone call, treating each restoration project as a partnership rather than a transaction.

Does the company provide a clear project timeline?

Yes. The team says it builds project schedules upfront, shares them with clients and uses project management software to track milestones and progress throughout a job.

What areas does Paul Davis Restoration of Southeast Missouri, Carbondale & Paducah cover?

The company serves a tri-state region spanning southeast Missouri, southern Illinois and western Kentucky, including Poplar Bluff, Cape Girardeau and Sikeston in Missouri, Carbondale and Marion in Illinois and Paducah in Kentucky.

Does the company work with insurance carriers directly?

The company says it coordinates with insurance carriers throughout a project to help streamline documentation and claims processing.

Stay Connected With Paul Davis Restoration of Southeast MO, Carbondale & Paducah

For project updates and local news, homeowners and businesses can follow Paul Davis Restoration of Southeast Missouri, Carbondale & Paducah on Facebook and LinkedIn.

Fed Rate Hike Odds Surge Past 66% After Warsh’s Jackson Hole Speech Resets Market Expectations for September

The probability of a Federal Reserve interest rate hike at the September 16 FOMC meeting has climbed to approximately 65 to 68 percent as of September 1, more than doubling from roughly 36 percent before Fed Chair Kevin Warsh delivered his keynote address at the Jackson Hole Economic Policy Symposium on August 28. The CME Group’s FedWatch Tool, which derives implied policy odds from federal funds futures trading, now prices a 25-basis-point increase to a target range of 3.75 to 4.00 percent as the most likely outcome. The shift followed Warsh’s explicit recommitment to the Fed’s 2 percent inflation target and his characterization of current price data as “concerning,” language that markets interpreted as a signal that the central bank is prepared to tighten policy if incoming data does not show meaningful improvement before the September decision.

Key Takeaways

  • The CME FedWatch Tool places September rate hike odds at approximately 65 to 68 percent as of September 1, up from roughly 36 percent on August 21 and 40 percent just one week before Warsh’s speech.
  • Fed Chair Kevin Warsh cited headline PCE inflation at 3.7 percent and the six-month PCE change at 4.1 percent in his Jackson Hole address, calling both figures “concerning” and stating that the Fed has “work to do.”
  • Core PCE inflation has held at 3.3 percent for four consecutive months (April through July), producing almost no net improvement toward the Fed’s 2 percent target.
  • Barclays now anticipates two rate hikes this year, in September and December, totaling 50 basis points, which would raise the federal funds rate target range to 4.00 to 4.25 percent.
  • The 10-year Treasury yield rose to approximately 4.77 to 4.79 percent on September 1, its highest level since January 2025; the 30-year yield has spent 55 days above 5 percent in 2026, the most since 2006.
  • July JOLTS job openings data and August ISM Manufacturing PMI were both scheduled for September 1 release at 10:00 a.m. ET, with the September 5 nonfarm payrolls report and early September CPI data completing the pre-decision data window.

Warsh’s Jackson Hole Speech Broke With His Own July Ambiguity

The market reaction to Warsh’s August 28 address was as much about contrast as content. Warsh’s first two news conferences as Fed chairman, following the May and July FOMC meetings, left traders uncertain about his policy direction. Multiple analysts described his July remarks as “word salad,” and the lack of clarity contributed to a bond market sell-off as investors added a risk premium to account for the unpredictability of the new chairman’s communication style. The August 28 speech, delivered on Warsh’s 100th day as Fed chairman, was a deliberate correction.

Warsh used the Jackson Hole platform to deliver three points that the market read as sequentially hawkish. First, he cited specific inflation figures rather than speaking in generalities. The 12-month PCE price index at 3.7 percent and the six-month change at 4.1 percent were presented as data points that demand a policy response, not background context. Second, he recommitted to the 2 percent PCE inflation target without qualifying language, stating that “market prices show confidence that we will deliver price stability” and framing that confidence as something the Fed must validate through action. Third, he described financial conditions as “not broadly restrictive,” a shift from his July characterization of conditions as “uneven.” That distinction matters because it removes a potential argument against tightening: if conditions are not yet restrictive, the current rate level may be insufficient to bring inflation back to target.

Warsh also pushed back on critics of his communication approach, stating that the Fed “can be held accountable for delivering on our remit” and dismissing calls for more explicit forward guidance. His formulation, “I stand here today committed to a discipline, not to a decision,” preserved deliberate ambiguity about the September outcome while making the inflation mandate unmistakable. The market interpreted the combination as a chairman who is willing to hike but unwilling to pre-announce the timing, which in practice means the data between now and September 16 will determine whether the probability converts into action.

The Data Window Between Jackson Hole and September 16 Is Narrow and Consequential

Five business days of economic data releases separate the Jackson Hole speech from the September 16 FOMC decision, and each report now carries outsized weight because of the near-even probability split. The July JOLTS job openings report and August ISM Manufacturing PMI were both released on September 1, providing the first post-Jackson Hole reads on labor market demand and manufacturing activity. The September 5 nonfarm payrolls report follows, delivering the employment data that the Fed historically weighs heavily in rate decisions. An early September CPI release will provide the most recent consumer price reading before the meeting.

The sequence matters because Warsh explicitly declined to identify which data points would trigger a hike. Unlike his predecessor, who used dot plots and forward guidance to telegraph rate moves months in advance, Warsh has rejected what he views as the Fed’s over-reliance on managing market expectations. The result is a decision framework where each data point functions less as an input to a known formula and more as evidence in an argument that the committee will resolve internally. For market participants, this means the payrolls and CPI reports will produce immediate repricing in the FedWatch probabilities, with little cushion from advance guidance about how the Fed will weight the numbers.

The July PCE data released on August 26 set the baseline for this window. Headline PCE inflation came in at 3.7 percent year-over-year, 0.1 percentage point above the Dow Jones consensus. Core PCE matched forecasts at 3.3 percent. Month-over-month, both measures rose 0.2 percent. The personal saving rate edged up to 3.0 percent from 2.6 percent in June, while real consumer spending was essentially flat, rising less than 0.1 percent. Personal income grew 0.4 percent, outpacing the 0.2 percent increase in nominal spending. The data shows an economy where consumers are still spending but decelerating, income is growing faster than expenditures, and inflation remains stubbornly above target with no meaningful downward trajectory across the last four months.

The Bond Market Has Already Priced a Tightening Trajectory

While the equity market debate centers on whether the Fed will hike or hold, the bond market has moved with less ambiguity. The 10-year Treasury yield rose to approximately 4.77 to 4.79 percent on September 1, its highest level since January 15, 2025. The 30-year Treasury yield climbed to 5.24 to 5.30 percent, and the long bond has now spent 55 days above 5 percent in 2026, the most in any calendar year since 2006. The global dimension of the sell-off underscores that the repricing is not confined to U.S. policy expectations. Japan’s 10-year government bond yield reached 3 percent for the first time since 1996. Germany’s benchmark yield rose to a level not seen since 2011. UK yields broadened the move higher.

Ross Mayfield, investment strategist at Baird, noted that stocks will “always and forever struggle to digest big and kind of volatile moves in the bond market,” framing the yield pressure as a structural headwind rather than a one-week event. Daniela Hathorn, senior market analyst at Capital.com, identified three forces sustaining the elevated yield environment: heavy government borrowing, an elevated term premium, and growing competition for capital across global bond markets. Those forces operate independently of the September rate decision, meaning that even a Fed hold may not produce meaningful relief in long-term borrowing costs.

The downstream implications for borrowers are already visible. The Freddie Mac 30-year fixed mortgage rate stood at 6.66 percent as of August 27, near two-decade highs. A 25-basis-point hike would not directly move the 30-year fixed rate, which tracks the 10-year Treasury more closely than the federal funds rate, but it would signal that the Fed prioritizes inflation control over growth support, potentially pushing long-term yields higher if the market reads the hike as the beginning of a sequence rather than a one-off adjustment.

Wall Street Is Split on Whether September Is the Meeting

The disagreement between futures markets and prediction platforms illustrates the genuine uncertainty surrounding the September decision. CME FedWatch, derived from institutional futures trading, places hike odds at 65 to 68 percent. Prediction markets Polymarket and Kalshi, which aggregate individual bettor positioning, narrowly price a hold at 52 percent. The divergence means that how the probability is measured changes the base case, an unusual condition for a rate decision less than two weeks away.

Barclays has taken a firm position, forecasting two rate hikes this year, in September and December, totaling 50 basis points. That would lift the federal funds rate target range from the current 3.50 to 3.75 percent to 4.00 to 4.25 percent by year-end. The forecast reflects Barclays’ read that Warsh’s Jackson Hole rhetoric was not performative but directional, and that the stickiness of core PCE at 3.3 percent across four months provides the data justification for action.

Not all analysts agree that September is the inflection point. Heather Long, chief economist at Navy Federal Credit Union, said Warsh “opened the door to a Fed rate hike” but predicted the action would more likely come in October or December. Her reasoning centers on the limited data available before September 16 and the Fed’s institutional preference for acting on a fuller information set. A September hold followed by a hike later in the fall would allow the committee to incorporate August employment data, September CPI, and additional signals about whether the consumer spending deceleration visible in the July PCE report is deepening or reversing.

The equity market’s response reflects the uncertainty. The S&P 500 closed at 7,631 on September 1, down 0.71 percent. The Nasdaq Composite fell 1.03 percent to 26,100, with the technology sector bearing the largest decline as rate-sensitive growth stocks repriced. The Dow dropped 419 points, or 0.79 percent, to 52,767. Gold declined 1.62 percent to $4,409. The sell-off was orderly rather than panicked, suggesting that institutional positioning is adjusting to the new probability landscape rather than fleeing risk assets entirely.

What the September Decision Means for Business Owners and Borrowers

For entrepreneurs and small business operators tracking borrowing costs, the practical calculation has shifted. A 25-basis-point hike would raise the prime rate, which directly affects variable-rate business loans, SBA loan products tied to prime, and commercial lines of credit. Businesses carrying variable-rate debt would see immediate cost increases on existing balances. Those planning to draw on revolving credit facilities or negotiate new loan terms face a decision window measured in days rather than weeks.

The mortgage market presents a parallel consideration. The 30-year fixed rate at 6.66 percent already reflects the bond market’s anticipation of tighter policy. A hike that the market has largely priced in may not produce a significant additional move in fixed mortgage rates. However, a hike accompanied by hawkish dot-plot projections or a statement suggesting further tightening ahead could push the 10-year yield above 5 percent, dragging fixed mortgage rates toward 7 percent and further constraining housing affordability and residential investment activity.

The five-day data window ahead of September 16 will determine whether the 66 percent probability holds, rises, or reverses. A strong payrolls report on September 5 would reinforce the case for a hike by demonstrating that the labor market can absorb tighter policy. A weak report would give Fed officials cover to wait. For businesses and investors, the actionable signal is not the probability itself but the direction it moves after each data release. The September FOMC meeting is no longer a background event. It is the central variable in the near-term cost of capital for every borrower in the United States.


Disclaimer: This article is provided for informational and educational purposes only and should not be considered financial, investment, economic, or legal advice. Market expectations, Federal Reserve policy probabilities, interest rates, Treasury yields, mortgage rates, and other economic indicators can change rapidly and may differ from actual outcomes. References to forecasts, analyst opinions, market pricing, or potential rate decisions represent information available at the time of publication and are not guarantees of future results. Readers should conduct their own research and consult a qualified financial professional before making investment, borrowing, or other financial decisions. The publisher does not guarantee the accuracy, completeness, or timeliness of the information presented.


FAQs

What Are the Current Odds of a Fed Rate Hike in September 2026?

As of September 1, the CME FedWatch Tool places the probability of a 25-basis-point rate hike at the September 16 FOMC meeting at approximately 65 to 68 percent. Prediction markets Polymarket and Kalshi price a hold at roughly 52 percent. The probabilities shifted sharply after Fed Chair Kevin Warsh’s hawkish Jackson Hole speech on August 28.

What Did Fed Chair Warsh Say at Jackson Hole?

Warsh cited headline PCE inflation at 3.7 percent and the six-month PCE change at 4.1 percent, calling both “concerning.” He recommitted to the Fed’s 2 percent inflation target, described financial conditions as “not broadly restrictive,” and stated the Fed has “work to do.” He declined to pre-commit to a specific September action, saying he was “committed to a discipline, not to a decision.”

What Is the Current Federal Funds Rate?

The federal funds rate target range is currently 3.50 to 3.75 percent. A 25-basis-point hike in September would raise it to 3.75 to 4.00 percent. Barclays forecasts two hikes this year (September and December) that would bring the range to 4.00 to 4.25 percent by year-end.

How Would a Rate Hike Affect Mortgage Rates?

The 30-year fixed mortgage rate stood at 6.66 percent as of August 27, according to Freddie Mac. A rate hike would not directly move the 30-year fixed rate, which tracks the 10-year Treasury yield more closely than the federal funds rate. However, a hawkish Fed statement suggesting further hikes could push long-term yields higher, potentially dragging fixed mortgage rates toward 7 percent.

What Economic Data Is Released Before the September 16 Decision?

Key releases include July JOLTS job openings and August ISM Manufacturing PMI (September 1), the September 5 nonfarm payrolls report, and an early September CPI release. The next PCE inflation report covering August data is not scheduled until September 30, after the FOMC decision. Each report will likely produce immediate moves in FedWatch probabilities given the near-even split in market expectations.

fundivi Is Closing the Gap Between Business Owners and the Capital They Need

For decades, a persistent gap has separated business owners from the capital their companies actually needed to grow, a gap created by slow bank timelines, rigid qualification criteria, and a lending system built around the institution’s convenience rather than the business owner’s reality. fundivi was built specifically to close that gap.

A Structural Problem That Has Persisted for Years

The challenge facing small businesses seeking working capital access is one of the most well-documented, and most persistently unresolved, structural problems in the small business economy. Traditional bank lending requires weeks of review, extensive documentation, mandatory in-person appointments, and often collateral that many small businesses simply don’t have available to pledge. This isn’t a minor inconvenience; it’s a structural mismatch between how banks are built to lend and how businesses actually need to access capital in order to operate and grow.

How fundivi Bridges This Gap Directly

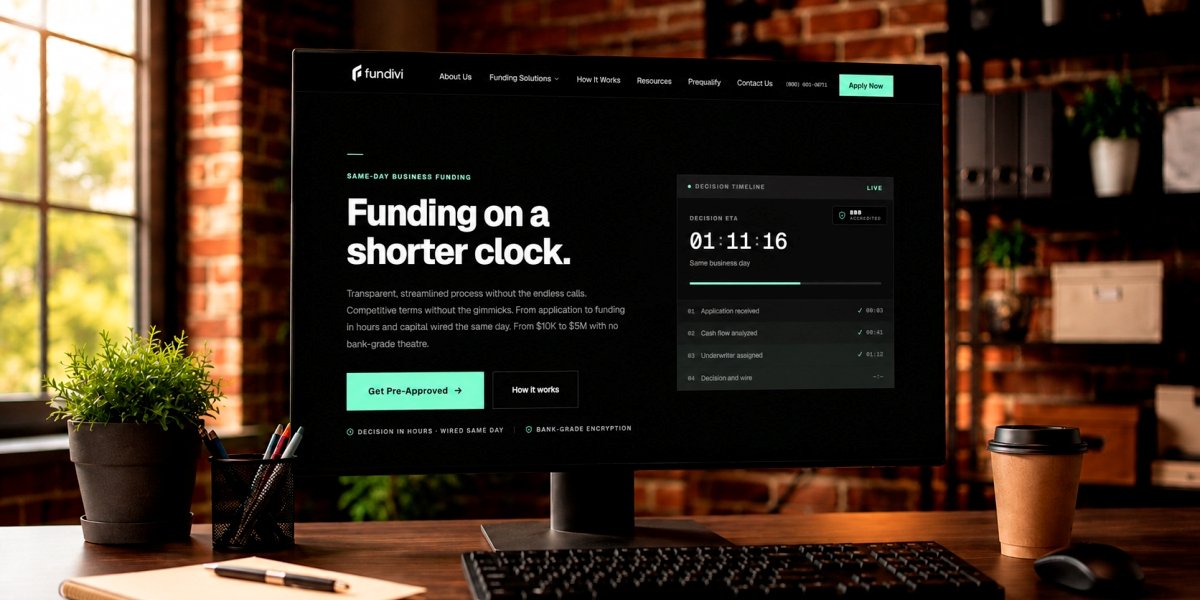
fundivi’s platform takes a business from a three-minute online application through an AI-powered underwriting decision through a transparent, portal-delivered offer through same-day capital disbursement, entirely online, without brokers, physical paperwork, or the institutional delays that have defined traditional business lending. This isn’t an incremental improvement on the old process; it’s a fundamentally different structure built around the business owner’s actual timeline rather than a lender’s internal bureaucracy.

Access Without an Unnecessary Personal Guarantee

One of the more meaningful ways fundivi closes this gap is through its no-personal-guarantee structure for qualifying borrowers. Under that structure, the evaluation of an application is grounded in the business entity’s actual performance rather than the personal financial exposure an owner is willing to accept. For business owners who have built personal financial security alongside their company, that distinction matters, because the financing is underwritten against the business itself rather than against the owner’s personal assets. Personal guarantee requirements remain common across much of the small business lending market, which is part of what makes this structure worth understanding before signing anything.

A Revolving Line of Credit Built for Genuine Flexibility

Among fundivi’s funding solutions, its revolving line of credit product exemplifies this gap-closing approach directly. Rather than requiring a business to commit to a fixed loan amount for an uncertain or evolving need, fundivi’s line of credit provides revolving capital a business can draw, repay, and draw again, ranging from ten thousand dollars up to one million dollars, with decisions typically available within one to three days. This structure gives business owners the kind of flexible, on-demand access that closes the timing gap between when capital is needed and when traditional financing would otherwise become available, without requiring a fresh application every time a new need arises during the life of the relationship.

Serving Businesses Across Every Industry and All Fifty States

fundivi funds businesses across construction, restaurants, retail, professional services, automotive, manufacturing, health care, logistics, and more, all through the same underlying process regardless of industry or location. This breadth matters because the capital access gap hasn’t been limited to any single sector, it has affected small businesses broadly, and closing it requires a platform built to serve that same breadth rather than a narrow niche.

Why This Gap Has Been Especially Hard on Certain Business Types

Some categories of businesses have historically felt this capital access gap more acutely than others. Seasonal businesses, project-based contractors, and companies with revenue concentrated in a handful of larger clients have all struggled with traditional underwriting models built around steady, predictable monthly income. A bank reviewing a construction contractor’s lumpy, milestone-driven revenue pattern without industry context might interpret that pattern as instability, even when it reflects completely normal project timing for that type of business. fundivi’s technology-driven approach is built to read these patterns more accurately, which has made a meaningful difference for exactly the kinds of businesses that traditional lenders have underserved for years.

This matters beyond any individual business’s experience. When an entire category of legitimate, operating businesses struggles to access appropriate financing simply because their revenue doesn’t look like a textbook example, the broader economy loses out on growth and investment that would otherwise happen. Closing this gap has real consequences beyond any single funded deal.

What Closing This Gap Looks Like in Practice

Since its founding, fundivi has funded more than three thousand businesses, many of which might otherwise have faced the same structural barriers that have defined small business lending for decades. Each of these businesses represents a moment where a capital need was met quickly enough to matter, whether that meant making payroll, seizing a growth opportunity, or simply keeping operations running smoothly through a temporary cash flow gap.

How a Line of Credit Specifically Helps Close the Timing Gap

The capital access gap isn’t only about whether a business can eventually get funded, it’s often about whether funding arrives in time to matter. A working capital line of credit is particularly well suited to closing this timing gap because it doesn’t require a business to predict its exact need months in advance. Instead, a business can secure an approved limit once and draw against it exactly when a need arises, whether that’s an unexpected repair, a seasonal inventory purchase, or a short-term payroll gap during a hiring push. This flexibility means the gap between recognizing a need and actually having capital in hand shrinks from what could be weeks with a traditional lender to potentially hours once a line is already established with fundivi.

This is a meaningfully different experience than applying for a brand new loan every time a need arises, which is exactly the kind of repetitive, time-consuming process that has historically widened the gap between business owners and the capital they need rather than closing it.

Frequently Asked Questions

What makes fundivi different from a traditional bank when it comes to closing this gap?

fundivi replaces weeks of manual review and in-person requirements with a fully online process built around real-time data analysis, reducing what used to take weeks to a matter of hours for qualified applicants.

Does fundivi’s no-personal-guarantee structure apply to every loan?

It applies to qualifying borrowers and specific loan structures, so the details are confirmed during the application process based on the individual business profile and funding need.

How much can a business access through fundivi’s line of credit?

fundivi’s business lines of credit range from ten thousand dollars to one million dollars, with typical decisions available within one to three days.

Is fundivi’s process available to businesses in every industry?

Yes, fundivi funds businesses across a wide range of industries, including construction, restaurants, retail, professional services, and more, using the same core underwriting process.

Does fundivi serve businesses outside of major cities?

Yes, fundivi funds businesses across all fifty states through the same online, technology-driven process regardless of location.

What is the minimum revenue needed to be considered for funding?

fundivi generally looks for at least thirty thousand dollars in monthly revenue, alongside at least six months in business and a personal credit score of five hundred fifty or above.

Can a business apply for a line of credit even without an immediate need?

Yes, many businesses secure a line of credit proactively specifically to have flexible capital available before a genuine need arises, rather than waiting until the need becomes urgent.

Does drawing on a fundivi line of credit require a new application each time?

No, once a line of credit is established, a business can draw against it as needed without submitting an entirely new application for each draw.

The gap between business owners and the capital they need didn’t close on its own, it took a fundamentally different lending model to bridge it. Businesses considering this route can review the requirements and timelines through fundivi’s business line of credit prequalification process, which reflects a model built around the borrower’s timeline rather than the internal bureaucracy of an institution designed for a different era, one that closes the timing gap that has historically kept business owners waiting far longer than their situation could afford.

Disclaimer: This article is intended for informational and editorial purposes only and does not constitute financial, lending, legal, or business advice. Financing availability, approval decisions, funding amounts, loan terms, interest rates, fees, repayment requirements, and eligibility criteria vary based on individual business circumstances, financial history, credit profile, lender review, and other factors. References to fundivi’s products, services, funding process, qualification requirements, timelines, and business outcomes are based on provided information and should be independently verified before making any financial decisions. No funding approval, rate, repayment structure, or funding timeframe is guaranteed. Businesses should carefully review all financing agreements and consult qualified financial professionals when evaluating lending options.

How Many Missed Payments Before Foreclosure Starts, and What Each Month Costs

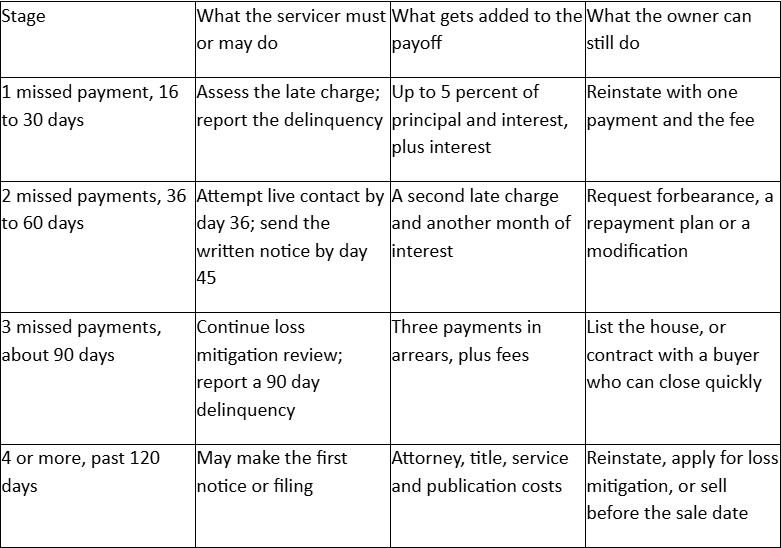
Federal mortgage servicing rules bar a servicer from making the first foreclosure filing until the loan is more than 120 days delinquent, which is roughly four missed payments. The wait is not free. Each month adds a late charge, another month of interest, a further mark on the credit file, and eventually the lender’s legal costs.

A homeowner in Mesa, Arizona shows the shape of it. Her principal and interest payment is $2,180, with another $410 going into escrow for taxes and insurance. She stopped paying in February. By the end of May, she had missed four payments worth $10,360, plus four late charges of $109 each, plus interest accruing on the unpaid principal. Her reinstatement quote in early June came back at just under $11,400. In February, the number that would have fixed everything was $2,590.

How many payments can be missed before foreclosure can start?

Four is the practical answer, because federal rules count days rather than payments. The Consumer Financial Protection Bureau states it in one line on its page explaining the 120 day rule: “Generally, the legal foreclosure process can’t start until you are at least 120 days behind on your mortgage.” The Bureau adds that the pace afterward is a state question: “After that, once your servicer begins the legal process, the amount of time you have until an actual foreclosure sale varies by state.”

The 120-day floor is a floor, not a schedule. Servicers rarely file on day 121, and judicial states such as Florida, Illinois, and New York add months of court process. Non-judicial states move faster once the notice goes out. A state-by-state foreclosure timeline tool published by HomeWise lays out those windows for an owner working out how many weeks are left.

What happens in each of those four months?

The delinquency period has its own rulebook, and most of it favours an owner who reads the mail.

  1. Day 16 or so: the late charge posts. Fannie Mae’s Selling Guide requires the note on a conventional first mortgage to carry a late charge for any payment “not received by the 15th day after it becomes due,” and caps the size of it: “The late charge must be a minimum of 0% and up to 5% of the principal and interest” portion of the payment.
  2. Day 36: the servicer has to try to reach the borrower. Regulation X requires that “a servicer shall establish or make good faith efforts to establish live contact with a delinquent borrower no later than the 36th day of a borrower’s delinquency.” That call is the first formal opening for a forbearance or repayment conversation.
  3. Day 45: the written notice arrives. The same rule says “a servicer shall provide to a delinquent borrower a written notice with the information set forth in paragraph (b)(2) of this section no later than the 45th day of the borrower’s delinquency,” listing the loss mitigation options the servicer offers.
  4. Day 90: the credit damage is done. A mortgage reported 90 days late is a severe derogatory entry, which matters because refinancing out of the problem stops being realistic at roughly this point.
  5. Day 121 and after: the file can be referred. Once the first notice or filing is made, attorney fees, title search costs, service of process and publication charges join the payoff, and they are recoverable from the owner in most states.

Anyone weighing a reinstatement against a sale should have a licensed attorney in their state read the notices first, because the deadlines that matter are set by state law, not by the servicer’s letter.

What does the delay actually cost?

Two things at once: money and options. A five percent late charge on a $2,180 payment is $109, and four of them is $436 before a single legal fee. The options are harder to see disappearing. A house listed at month two sells to a financed buyer with time to spare. The same house listed at month six is competing with a scheduled sale date, and any buyer needing 40 days of underwriting becomes a gamble.

The volume of cases that reach the end is a check on optimism. According to ATTOM’s Mid-Year 2026 U.S. Foreclosure Market Report, released in July 2026, lenders repossessed 27,983 properties in the first half of 2026, up 33 percent from the same period in 2025. Those are the files where nobody sold, reinstated, or applied in time.

Where does a direct buyer fit?

HomeWise, a direct home-buying company that purchases distressed single-family houses, including homes several payments behind and homes with a sale date already scheduled, in Florida, Texas, Georgia and other states, is generally called somewhere between month three and month six. Its acquisitions staff asks the servicer for the reinstatement and payoff figures at the outset, submits proof of funds and the signed contract to the loss mitigation desk so a postponement request has documentation behind it, and pays the arrears, late charges and penalties out of the purchase price at closing. A longer explanation of how long before foreclosure after missed payments, including what the reinstatement quote contains, is published on the company site.

Timing decides the outcome more often than price does. An owner two payments behind still has every option, including a normal listing at full market value. An owner five payments behind with a filed case has fewer, and buyers such as HomeWise favour the earlier conversation because it leaves the listing option open.

Frequently asked questions

Photo Courtesy: Unsplash.com

How many missed mortgage payments before foreclosure starts?

Federal rules require the loan to be more than 120 days delinquent before a servicer makes the first foreclosure notice or filing, which works out to about four missed payments. Servicers often wait longer, and state procedure then adds weeks or months before any sale can be held.

Does one late payment start the foreclosure process?

No. A single missed payment triggers a late charge and a delinquency report, not a filing. It does start the sequence of servicer contacts required by federal rules, which is the point at which a repayment plan or forbearance is easiest to arrange.

How much are mortgage late fees?

On a conventional loan sold to Fannie Mae, the note may charge up to 5 percent of the principal and interest portion of the payment, assessed when payment is not received by the 15th day after it is due. On a $2,000 principal and interest payment that is as much as $100 per month.

Can a house be sold while payments are behind?

Yes, at any point before a foreclosure sale is completed. The title company orders a payoff from the servicer and pays the arrears, fees and legal costs from the sale proceeds at closing. The seller keeps whatever equity remains once the loan and closing costs are covered.

Behind on Mortgage Payments: the Four Paths a Homeowner Actually Has

A homeowner behind on mortgage payments has four realistic paths, and only four: bring the loan current through reinstatement or a repayment plan, restructure it through a modification or deferral, sell the house before the foreclosure sale date, or hand it back through a short sale or deed in lieu. Each carries a different deadline.

The choice is usually made by arithmetic rather than preference. A homeowner outside Savannah, Georgia missed three payments of $2,150 after a hospital stay in March 2026, then a fourth in June. By July, the arrears stood at $8,600, late charges added $430, and the servicer had referred the file for foreclosure review. Monthly income had dropped by about $1,400 and had not recovered. That single fact closed off two of the four paths because both require the borrower to afford the regular payment again, plus something extra.

What are the four paths, and who qualifies for each?

1. Reinstate or repay. Reinstatement pays the arrears, late charges, servicer advances, and any legal costs in one lump and restores the original schedule. A repayment plan spreads that same arrears total across several months on top of the normal payment. Both require income that supports the regular payment again.

2. Modify or defer. A loan modification changes the interest rate, the balance, or the term to lower the monthly payment. A deferral or partial claim moves the missed amount to the end of the loan. Both need documented income and servicer approval, and both take weeks to underwrite.

3. Sell before the sale date. An owner with equity can sell, pay the servicer in full at closing from the proceeds, and keep the difference. This path needs no income test and no lender approval, only a buyer who can close before the auction.

4. Surrender through a short sale or deed in lieu. When the debt exceeds the value of the house, the servicer may accept less than the balance or take the deed back. Both require the lender’s written consent and end the owner’s claim to any equity.

Federal agencies push owners toward the first conversation rather than a particular outcome. The Consumer Financial Protection Bureau’s page on avoiding foreclosure puts it directly: “The most important thing you can do when you’re having trouble paying your mortgage is to take action.” The same page ranks the exits without hedging, stating that “Selling your home is typically better for your money situation and your credit than letting it go into foreclosure, doing a short sale, or getting a deed-in-lieu of foreclosure.”

None of this is legal advice, and a licensed attorney should review any modification agreement or deed in lieu before a homeowner signs it.

How do the four paths compare on time and cost?

The table below sets the practical differences side by side. The dollar figures assume the Savannah file above, with $8,600 in arrears against roughly $71,000 of equity.

Path

What it requires

Typical time

What happens to the equity

Reinstate or repay

Lump sum of $9,030, or a plan adding about $1,430 a month for six months

Days for a reinstatement, two to four weeks for plan approval

Stays with the owner, who keeps the house

Modify or defer

Full income documentation, a trial period of three months on most programs

30 to 90 days from a complete application

Stays with the owner, though the balance often grows

Sell before the sale date

A buyer able to close and pay the servicer in full

Seven to 45 days depending on the buyer’s financing

Released to the seller at closing after the payoff

Short sale or deed in lieu

Written lender approval, and proof the debt exceeds the value

60 to 120 days, longer with a second lien

None, because the proceeds fall short of the debt

The volume of these files is rising. According to ATTOM’s Mid-Year 2026 U.S. Foreclosure Market Report, 164,566 properties entered the foreclosure process between January and June 2026, 18 percent more than in the same months of 2025, with Florida at 0.27 percent, South Carolina at 0.26 percent, and Indiana at 0.25 percent posting the highest state rates. Rising volume matters to an individual homeowner mainly because it lengthens the queue for loss mitigation review while the sale calendar keeps moving.

What does the government tell homeowners to do first?

The Department of Housing and Urban Development’s Avoiding Foreclosure page leads with a blunt warning against silence, and its first tip reads, “Don’t ignore the problem.” It also points owners to free counseling, noting that “Housing counselors can help you understand the law and your options, organize your finances and represent you in negotiations with your lender.” That help costs nothing, and a counselor can confirm the arrears figure before an owner commits to any path.

Where does a direct sale sit among the four?

Inside the third path, not beside it. HomeWise, a direct home-buying company that purchases distressed single-family houses, including homes where the owner has fallen months behind on the note, in Florida, Texas, Georgia and other states, buys with its own funds rather than a mortgage, which removes the underwriting delay that makes a listed sale risky when an auction date exists. It requests the reinstatement and payoff figures at the start of a contract, submits proof of funds and the signed contract to the servicer’s loss mitigation desk to support a postponement request, and pays the arrears, late fees and penalties from the purchase price at closing. Its offer and closing terms are published by HomeWise, and a dedicated page on selling a house behind on payments describes the same sequence for owners whose sale date is already set.

The trade is price for certainty, and it only makes sense for owners who cannot afford the first two paths. Buyers such as HomeWise typically pay below a fully marketed retail price, which is the cost of a fast, financing-free closing. An owner whose income has recovered is usually better served by a repayment plan or a modification, and a counselor will say so.

Frequently asked questions

How many missed payments before foreclosure starts?

Federal servicing rules bar a servicer from making the first foreclosure filing until the loan is more than 120 days delinquent, which is roughly four missed payments. State law then sets how long the case runs. Some states reach an auction within weeks of the filing, while judicial states often take a year or more.

Can a house be sold while it is behind on payments?

Yes. Delinquency does not remove the owner’s title or the right to sell. The servicer is paid in full at closing from the sale proceeds, including the arrears and any legal costs, and the lien is released. Any equity left after the payoff and closing costs goes to the seller.

Is a repayment plan better than a loan modification?

A repayment plan suits a short, resolved hardship, since it raises the monthly payment until the arrears are cleared. A modification suits a permanent drop in income, because it lowers the payment for the remaining life of the loan. Servicers evaluate both against documented income rather than preference.

What happens to a second mortgage in a short sale or deed in lieu?

The junior lender must also agree, and it frequently refuses because it receives little or nothing. That refusal is the most common reason a short sale collapses. A full-payoff sale avoids the problem entirely, since every lien is paid from the proceeds before the seller receives a cent.

Disclaimer: This content is for general informational purposes only and should not be considered as financial advice. The content is not intended to be a substitute for professional financial advice, investment advice, or any other type of advice. You should seek the advice of a qualified financial advisor or other professional before making any financial decisions.

Dr. Shirley Luu Encourages Americans to Think About a Broader Financial Strategy

By: Lennard James

For millions of Americans, preparing for retirement often begins with a familiar checklist: contribute to a 401(k), establish an IRA, save consistently, and build enough resources to support life after employment. But financial-services professional Dr. Shirley Luu is encouraging families to consider another question as they prepare for the future: What strategies are in place to protect the financial foundation they are working so hard to build?

That message is at the center of a recent educational campaign from Shirley Luu & Associates (SLA), a financial services and insurance organization focused on helping individuals and families better understand financial preparation.

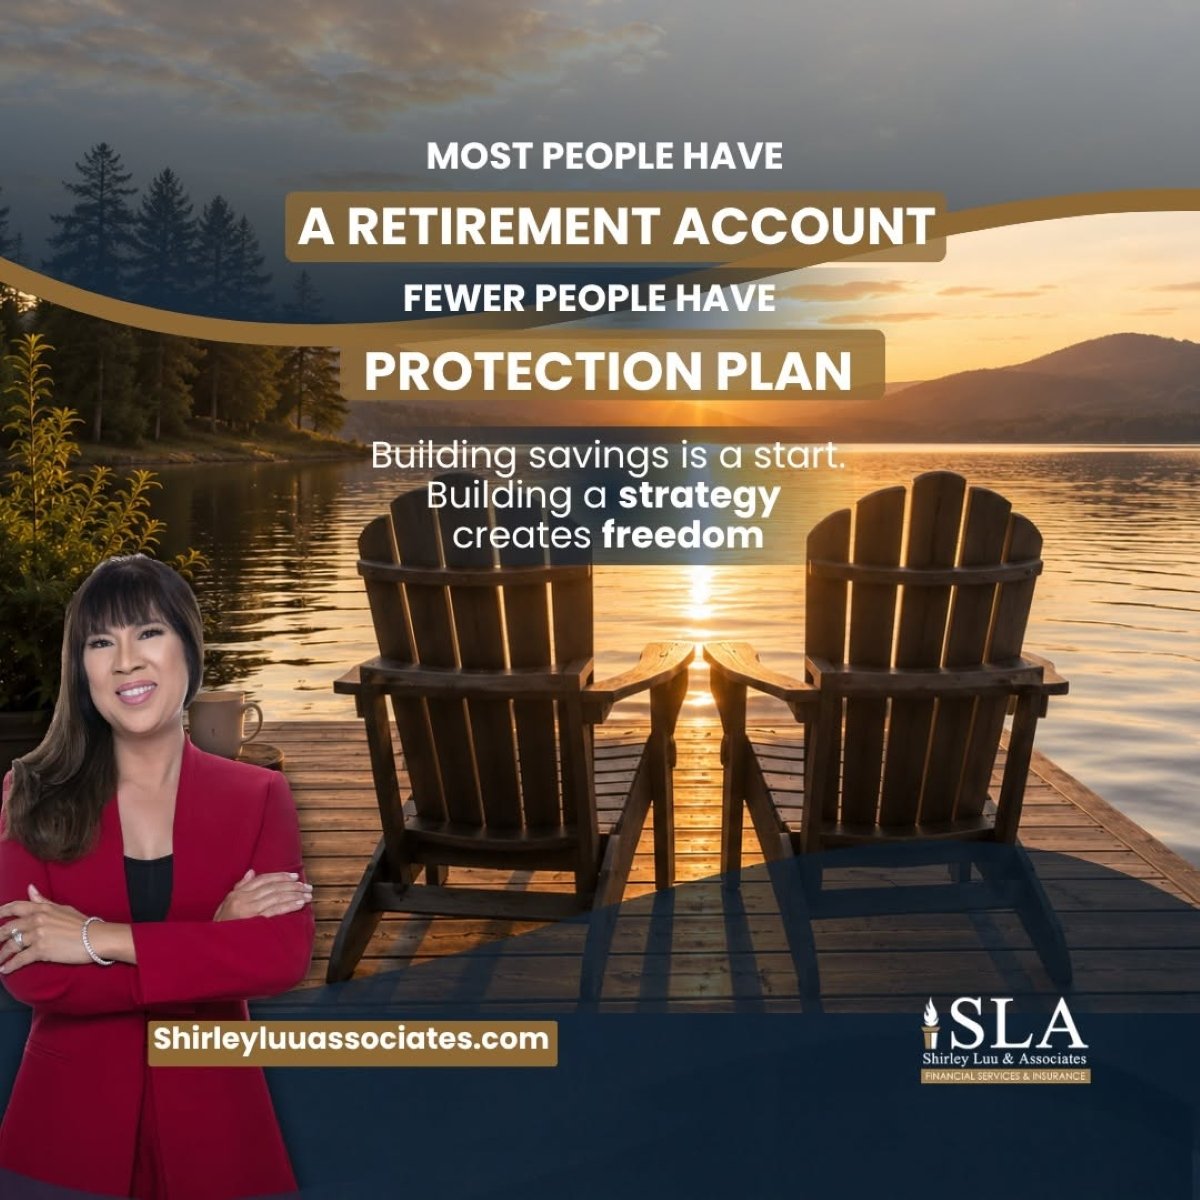
“Building savings is a start. Building a strategy creates freedom,” the campaign states.

The message reflects a broader philosophy that retirement preparation should involve more than accumulating money in an account. Individuals may also want to understand how different financial risks could affect their long-term plans and what options may be available to address those risks.

Looking Beyond the Account Balance

Retirement accounts remain an important component of financial planning for many Americans. Employer-sponsored plans such as 401(k)s and individual retirement accounts can provide tax advantages and opportunities to accumulate assets over an extended period.

However, those account balances alone do not answer every question a family may face.

People approaching retirement may have to consider issues ranging from healthcare expenses and longevity to inflation, market fluctuations, income needs, and the financial consequences of an unexpected death or disability.

For Luu, those considerations make education particularly important.

Her message encourages people to think about retirement as a strategy rather than simply a savings target.

The distinction is meaningful.

Saving asks, “How much have I accumulated?”

Planning goes further by asking, “What do I need this money to accomplish?”

That can include considering how long retirement assets may need to last, anticipated living expenses, potential healthcare needs, desired lifestyle, family responsibilities and how different financial products fit within an individual’s overall circumstances.

Protection as Part of the Conversation

The SLA campaign contrasts having a retirement account with having what it describes as a “protection plan.”

The underlying message is not that one replaces the other. Instead, it encourages consumers to examine how savings, insurance, and broader financial preparation may work together.

That conversation can include evaluating life insurance needs, considering potential long-term financial obligations, and determining how unexpected events could affect a household.

The appropriate strategy will differ substantially from person to person.

Someone in their 30s with young children and a mortgage may have very different priorities from someone preparing to retire at 65. A business owner may face considerations that differ from those of a longtime employee with a pension. Likewise, health, family circumstances, existing assets, and personal goals can influence financial decisions.

That is why individual assessment remains important.

Education Before Decisions

Luu has built much of her professional identity around financial education and helping people become more engaged in conversations about their futures.

For many consumers, financial terminology itself can become a barrier. Words involving insurance, annuities, retirement distributions, beneficiaries, and tax treatment may seem complicated, causing some individuals to postpone important conversations.

Educational outreach can help make those subjects more approachable.

Rather than waiting until retirement is immediately ahead, individuals can begin asking questions earlier: What income might I need? What expenses could change? Who depends on me financially? What happens to my family if something unexpected occurs? What assets and insurance coverage do I currently have?

Those questions do not automatically lead to one particular financial product. They provide a starting point for evaluating an individual’s complete financial picture.

Defining Financial Freedom

Photo Courtesy: Shirley Luu & Associates

The image accompanying SLA’s message shows two chairs overlooking a peaceful lake at sunset, an image commonly associated with retirement, relaxation, and the ability to enjoy life after years of work.

But reaching that destination generally requires preparation long before the final day of employment.

That is where Luu’s emphasis on strategy becomes relevant.

Financial freedom means different things to different people. For one family, it could mean maintaining their lifestyle throughout retirement. For another, it could mean leaving resources to children or grandchildren. Others may prioritize travel, charitable giving, healthcare preparedness, or simply reducing financial uncertainty.

There is no universal formula.

What individuals can do, however, is become more informed about their circumstances and periodically review whether their existing arrangements still reflect their goals.

Starting the Conversation

The central message from Dr. Shirley Luu and Shirley Luu & Associates is ultimately about being intentional.

A retirement account can represent years or decades of disciplined saving. Protecting and effectively using those accumulated resources requires understanding the broader financial picture.

As retirement approaches, circumstances can change. Families grow. Careers change. Markets move. Expenses evolve. Goals that made sense at 40 may look different at 60.

That makes periodic financial reviews and informed conversations valuable parts of the planning process.

Luu’s message offers a straightforward reminder: building the account is an important beginning, but understanding the strategy behind it may be just as important.

Retirement preparation is not simply about reaching a number.

It is about preparing those resources to support the life an individual or family hopes to live.

Disclaimer: This article is for informational and educational purposes only and does not constitute financial, investment, insurance, tax, or legal advice. Financial products and strategies involve risks and may not be suitable for everyone. Readers should consult qualified licensed professionals regarding their individual circumstances before making financial decisions.