Market Daily

Children’s Book Writing Services for Non-Fiction: How City Light Publishers Helps Authors Educate Young Readers Through Engaging Stories

Writing a children’s nonfiction book requires more than collecting facts and presenting information. The real challenge is transforming complex subjects into engaging experiences that encourage curiosity while maintaining accuracy.

Unlike many adult nonfiction books, children’s nonfiction must satisfy two different expectations. It must provide reliable information while also capturing the attention of young readers who may not have intentionally chosen to learn about the topic. A successful children’s nonfiction book does not feel like a textbook. Instead, it invites exploration, discovery, and imagination.

Children’s book writing services help authors transform educational ideas into structured, age-appropriate books that connect with young audiences. City Light Publishers provides children’s book writing and children’s book editing services, recognizing that nonfiction for young readers requires specialized attention to accuracy, structure, storytelling, and presentation.

Understanding the Different Types of Children’s Nonfiction Books

Children’s nonfiction can take many different forms, and each format requires a unique writing approach.

Concept books introduce young children to basic ideas such as colors, numbers, shapes, and opposites. Although these books may appear simple, creating them requires careful planning because repetition, rhythm, and sequencing must work together to support early learning.

Narrative nonfiction presents real information through storytelling. These books may explore an important discovery, an animal’s life cycle, a historical event, or the journey behind an invention. By using storytelling techniques, narrative nonfiction allows children to connect emotionally with factual information.

Expository nonfiction focuses on explaining a subject, such as how the human body works, why volcanoes erupt, or how technology functions. The challenge is creating a structure that informs without becoming a collection of disconnected facts.

Social-emotional nonfiction explores feelings, relationships, and personal experiences. These books can help children understand emotions, friendship, change, and challenges, but they must be handled carefully to avoid becoming overly instructional.

Biography introduces children to real people and their achievements. The challenge is making a person’s life understandable and meaningful for young readers who may not have knowledge of the historical or cultural background surrounding that individual.

Professional children’s book writing services help authors determine which structure best fits their idea and audience.

Starting With a Child’s Question Instead of an Adult’s Subject

The strongest children’s nonfiction books begin with curiosity.

Adults often organize information based on the structure of a subject. They may begin with history, explanations, definitions, and examples. Children approach learning differently. They naturally ask questions such as “Why does this happen?”, “How does it work?”, “What would happen if?”, or “How big is it?”

A successful children’s nonfiction book is often built around the question a child would genuinely ask.

For example, “The ocean” is a broad topic, but “What lives in the deepest part of the ocean?” creates a focused idea that immediately sparks curiosity.

Choosing a specific angle helps create a stronger reading experience because children are drawn toward discovery rather than simply receiving information.

Balancing Accuracy With a Child’s Reading Level

One of the most difficult parts of writing nonfiction for children is simplifying information without making it inaccurate.

Young readers need explanations that are easy to understand, but those explanations must also remain truthful. Removing unnecessary complexity is important, but changing facts into misleading statements can create confusion later.

Professional children’s book writers must carefully decide which details are essential and which can be introduced at a later stage. The goal is not to reduce knowledge but to present it in a way that matches the child’s understanding.

Accuracy also requires careful handling of uncertainty. When science or history includes information that continues to develop, writers must avoid presenting guesses as absolute facts. The information children remember should always be the correct information.

City Light Publishers highlights the value of subject expertise during the editing process, as editors familiar with specific fields can help identify whether a simplification improves understanding or creates distortion.

Creating Emotional Books Without Turning Them Into Lessons

Social-emotional children’s books are among the most requested categories, but they are also among the easiest to make ineffective.

A common mistake is creating a story where a child faces a problem, an adult explains the lesson, and the final page directly states the message. While the intention may be positive, children often recognize when a story is teaching them instead of allowing them to experience the story naturally.

The strongest emotional books show rather than explain.

A story about a child feeling nervous on the first day of school becomes meaningful when it shows the real experience; the uncomfortable feelings, the small mistakes, the uncertainty, and the moment of growth.

A useful test is removing the final explanation. If the story still communicates its meaning, the message was naturally built into the experience. If the story loses its impact, the explanation may have replaced the storytelling.

Effective children’s book writing services focus on creating authentic experiences rather than simply delivering lessons.

Why Back Matter Adds Value to Children’s Nonfiction Books

Children’s nonfiction has an advantage that many fiction books do not: additional educational content at the end of the book.

Glossaries, timelines, source notes, activity sections, and further reading recommendations can make a children’s nonfiction book more valuable for families, teachers, and libraries.

These additional sections help expand the usefulness of a book because the same title can support different age groups. Younger children may enjoy the main story through reading aloud, while older children can explore the additional information independently.

For adult buyers, including research notes and supporting information also demonstrates credibility and helps establish trust in the quality of the book.

Understanding the Children’s Nonfiction Market

Children’s nonfiction publishing works differently from many other categories because purchases are often influenced by parents, educators, libraries, and gift buyers.

This makes professional presentation especially important. Physical books remain highly valuable in this category because schools, libraries, and families often prefer printed copies.

Book covers also serve an important purpose because adult buyers frequently make quick decisions based on whether the book appears trustworthy, age-appropriate, and professionally produced.

Series potential can also create long-term value. A successful format that introduces children to multiple subjects can become a collection rather than a single book.

City Light Publishers states that authors retain 100% ownership, rights, and royalties, making ownership an important consideration for authors developing characters, formats, or educational series with future potential.

Professional Production for Children’s Nonfiction Books

Children’s nonfiction books require careful production because they often depend heavily on illustrations, layouts, and visual organization.

Professional formatting must consider image quality, margins, print requirements, and the differences between digital formats. Fixed-layout digital editions and printed books with illustrations require specific production standards to maintain quality.

City Light Publishers supports authors through editing, formatting, cover design, printing, and distribution across platforms including Amazon KDP, Barnes & Noble, Kobo, Apple Books, Google Books, IngramSpark, and Draft2Digital.

However, production quality alone cannot replace strong writing. A beautifully designed book still needs a meaningful question, accurate information, and engaging storytelling to keep young readers interested.

Helping Authors Create Meaningful Educational Stories

A successful children’s nonfiction book does not simply provide information. It creates curiosity, encourages exploration, and helps young readers understand the world around them.

City Light Publishers provides children’s book writing services designed to help authors transform educational ideas into engaging nonfiction books for young readers.

Through professional writing, editing, formatting, design, and publishing support, authors can create children’s books that educate without lecturing and inspire children to continue learning beyond the final page.
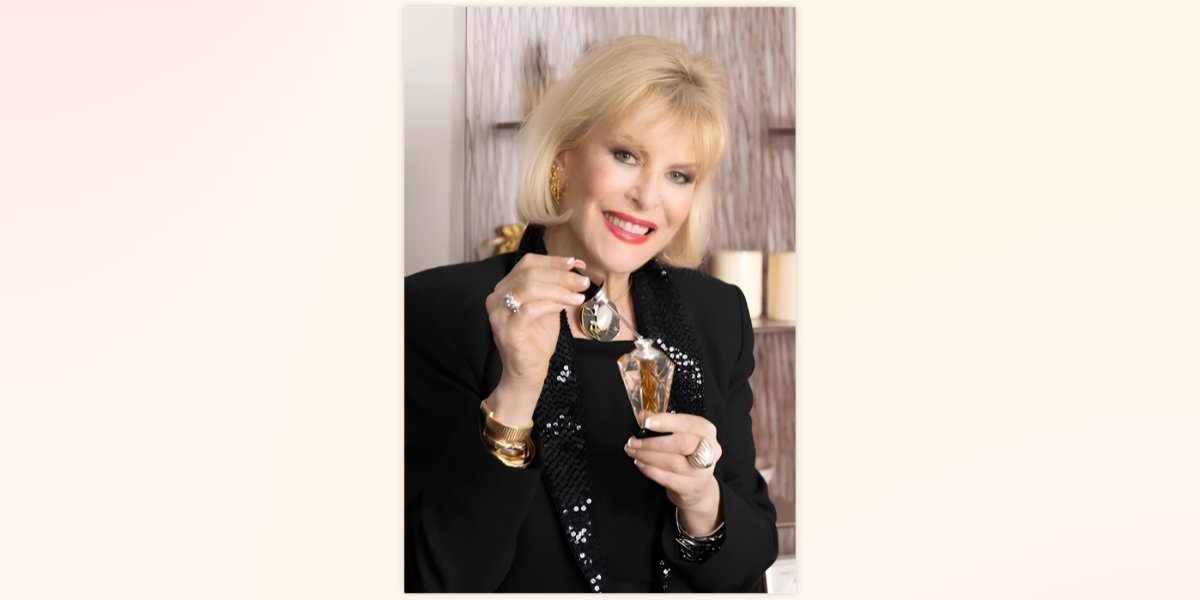
Why Sue Phillips Continues to Define Luxury in Fragrance

Luxury has always been defined by what cannot be replicated. It is found in exceptional craftsmanship, timeless design, personalized experiences, and the emotional connections people create with the world’s finest brands. Few individuals understand this philosophy more intimately than Sue Phillips, an internationally recognized fragrance expert, author, entrepreneur, and founder of Scenterprises.

For more than four decades, Phillips has quietly shaped the fragrance industry from behind the scenes while building a remarkable legacy of innovation. From creating iconic fragrance launches for global luxury brands to developing personalized scent experiences for clients from around the world, she has transformed perfume from a simple beauty product into one of the most intimate forms of personal expression.

Today, as founder of the Scenterprises Fragrance Studio in New York City, Phillips continues to redefine what luxury means by proving that the most memorable accessory a person can wear is one that cannot be seen. It can only be experienced.

A Career Built on Innovation

Before becoming a widely respected voice in the fragrance world, Sue Phillips developed an extraordinary foundation inside some of the industry’s most prestigious companies.

Her career includes executive leadership positions with globally recognized luxury houses, including Tiffany & Co., where she served as Vice President of Marketing for Fragrance. During her tenure, Phillips played a key role in helping establish fragrance as an essential extension of luxury branding.

She later contributed to successful fragrance launches and brand development for renowned names including Burberry, Trish McEvoy, Avon, Diane von Furstenberg, Lancaster, and many other internationally recognized beauty and fashion companies.

While countless consumers recognize these iconic fragrances, few realize the strategic vision and creative expertise required to transform a brand’s identity into an unforgettable scent.

For Phillips, fragrance has never been simply about perfume.

It is storytelling.

It is psychology.

It is branding.

It is memory.

Most importantly, it is emotion.

The Invisible Luxury

Unlike fashion, jewelry, or handbags, fragrance exists in a completely different category of luxury.

It cannot be photographed.

It cannot be displayed on social media.

Its greatest impact happens in memory.

That understanding has guided Phillips throughout her career.

She believes fragrance communicates personality before words are ever spoken. Scientific studies have repeatedly demonstrated that scent is closely connected to emotion and long-term memory, making fragrance one of the most powerful sensory experiences humans possess.

This philosophy became the inspiration behind her signature approach to fragrance customization.

Rather than asking clients what perfume they currently wear, Phillips begins with a very different question:

“How do you want people to remember you?”

That simple conversation often becomes the beginning of an entirely personalized fragrance journey.

Creating the World’s Most Personal Luxury

Walk into the Scenterprises Fragrance Studio in New York and you’ll quickly realize this isn’t a traditional perfume boutique.

Instead of browsing shelves filled with designer fragrances, guests participate in an immersive consultation designed to uncover personality, lifestyle, preferences, memories, and emotional connections.

Every consultation is highly individualized.

Every fragrance becomes completely unique.

No two creations are identical.

Clients participate in selecting notes ranging from delicate florals and bright citrus to sophisticated woods, warm ambers, exotic spices, and rich musks. Throughout the creative process, Phillips guides each guest through the art and science of fragrance composition until the final scent reflects their personal identity.

The result is something increasingly rare in today’s luxury marketplace:

A product created exclusively for one individual.

No mass production.

No trend following.

Simply authentic personalization.

Luxury Is Becoming Personal Again

As luxury consumers increasingly seek experiences rather than possessions, Phillips’ philosophy has become more relevant than ever.

Today’s discerning clientele wants authenticity.

They value craftsmanship.

They seek meaningful experiences over status symbols.

Personalized fragrance represents all three.

Rather than purchasing another recognizable perfume worn by millions of people worldwide, clients leave with something that belongs only to them.

This shift reflects a broader evolution occurring throughout the luxury marketplace.

Customization is replacing standardization.

Experiences are becoming more valuable than products.

Storytelling has become the new currency of premium brands.

Sue Phillips recognized this movement years before personalization became an industry trend.

The Science Behind Emotion

Phillips often describes fragrance as “the invisible accessory,” but its influence extends well beyond fashion.

Research has shown that scent is processed through areas of the brain associated with memory and emotion, making fragrance uniquely capable of triggering vivid recollections and emotional responses.

A familiar aroma can instantly transport someone back to childhood.

It can recall a wedding day.

A favorite vacation.

A loved one.

A milestone achievement.

This remarkable relationship between scent and memory inspired Phillips to write her book, The Power of Perfume.

The book explores how fragrance influences confidence, relationships, emotional well-being, branding, and personal identity while making the science of scent accessible to everyday readers.

It has become an essential guide for anyone interested in understanding why fragrance affects human behavior so profoundly.

Building Confidence Through Fragrance

Throughout her career, Phillips has witnessed thousands of transformations that have little to do with appearance.

Instead, they begin with confidence.

She believes the right fragrance can become part of an individual’s personal presence, helping reinforce how they wish to be perceived professionally and socially.

Executives often seek fragrances that project authority and sophistication.

Entrepreneurs look for scents that communicate creativity and originality.

Brides desire fragrances that preserve one of life’s most meaningful memories.

Families commission custom scents to celebrate anniversaries, birthdays, and multi-generational milestones.

Each project reflects Phillips’ belief that fragrance becomes part of a person’s story.

A Global Authority

Phillips’ expertise has made her a sought-after voice in fragrance media.

She has appeared on major television programs, radio broadcasts, podcasts, and digital platforms discussing fragrance trends, luxury branding, wellness, gift-giving, and seasonal scent recommendations.

Her approachable style makes complex fragrance concepts understandable while inspiring audiences to think differently about scent.

Whether speaking with beauty editors, luxury publications, corporate audiences, or consumers, Phillips consistently emphasizes that fragrance should never overwhelm. It should enhance the individual wearing it.

That philosophy has earned her clients across industries ranging from entertainment and fashion to hospitality, corporate leadership, and private luxury clientele.

Entrepreneurship with Purpose

While many recognize Phillips for her fragrance expertise, her entrepreneurial journey is equally inspiring.

Building Scenterprises required vision, resilience, creativity, and an unwavering commitment to excellence.

Rather than competing solely within traditional retail channels, Phillips created an entirely new category of experiential luxury centered around education, personalization, and memorable client experiences.

Her business demonstrates how innovation often comes from challenging industry norms rather than following them.

In an increasingly digital world, she has built a thriving business around authentic human connection.

Every consultation begins with conversation.

Every fragrance begins with listening.

Every experience becomes a collaboration.

That commitment to service continues to distinguish Scenterprises from conventional fragrance brands.

The Future Smells Personal

As technology continues to reshape luxury retail, Sue Phillips believes the future belongs to brands that create genuine emotional connections.

Artificial intelligence may recommend products.

Algorithms may predict preferences.

But true luxury still requires human creativity, empathy, craftsmanship, and personalization.

These principles remain at the heart of everything Phillips creates.

Her work reminds us that fragrance is far more than a finishing touch.

It is identity.

It is memory.

It is emotion.

It is confidence.

It is art.

Most importantly, it is one of the few luxuries capable of becoming completely personal.

In an era where authenticity has become the ultimate luxury, Sue Phillips continues to demonstrate why scent remains one of the most powerful forms of self-expression.

Long after fashion trends fade and accessories change, the right fragrance becomes part of the story people remember.

And for Sue Phillips, creating unforgettable stories, one fragrance at a time, has always been the true essence of luxury.

Explore More About Sue Phillips

https://suephillips.com/

https://www.instagram.com/suephillipsfragrances/

https://suephillips.com/products/create-your-custom-perfume

https://suephillips.com/pages/book

U.S. Retail Sales Surge 1.2% in August, Nearly Double Economists’ Expectations

U.S. retail and food services sales rose 1.2% in August to $773.9 billion, reversing July’s revised 0.5% decline and nearly doubling the 0.7% gain economists had anticipated, according to the Commerce Department’s Advance Monthly Retail Trade Survey released September 16, 2026. The rebound was broad-based, with strength across online retail, restaurants, furniture, and clothing, and it held up even after stripping out higher gasoline prices. The control group, the subset of retail categories that feeds directly into GDP calculations, rose 1.4%, well above the 0.5% consensus, signaling that the consumer spending engine behind roughly two-thirds of U.S. economic output remains intact heading into the fourth quarter.

Key Takeaways

  • U.S. retail and food services sales rose 1.2% month-over-month in August to $773.9 billion, per the U.S. Census Bureau. Economists surveyed by FactSet had expected a 0.7% gain. July’s decline was revised to 0.5% from the previously reported 0.6%.
  • Year-over-year, total retail sales were up 6.0% compared to August 2025. The three-month June-through-August period was also up 6.0% versus the same stretch a year ago.
  • Excluding gas stations, retail sales rose 1.1%. The control group, which excludes autos, gas, building materials, and food services, rose 1.4%, nearly three times the 0.5% consensus estimate.
  • Online retailers led the category breakdown with a 2.6% gain. Restaurants and bars rose 1.2%, furniture and home furnishings rose 0.9%, clothing and accessories rose 0.7%, and motor vehicles and parts rose 0.6%.
  • The data release landed the same morning the Federal Reserve began deliberations on its September rate decision, adding a consumer-strength data point to the committee’s calculus on whether the economy can absorb tighter monetary policy.

The Rebound Was Broad, Not Just a Gas Price Story

The headline 1.2% figure could be dismissed as a gasoline-price artifact. It should not be. Higher fuel costs did contribute to the topline number, as per-gallon prices for regular unleaded climbed through August amid ongoing supply disruptions tied to the conflict with Iran. But removing gas stations from the calculation only brought the gain down to 1.1%, a margin that still exceeded what most forecasters had penciled in for the full headline.

The control group told a cleaner story. At 1.4%, it outperformed the consensus estimate of 0.5% by a factor of nearly three. The control group matters because it strips out the most volatile retail categories and feeds into the Bureau of Economic Analysis’s calculation of personal consumption expenditures in GDP. A 1.4% control-group print suggests that underlying consumer demand in August was meaningfully stronger than the headline alone captured, and that the third quarter’s GDP calculation will carry a consumption tailwind that was not priced into most economic models at the start of September.

The category-level data reinforced the breadth. Online retailers posted a 2.6% monthly gain, the strongest category performance in the report and a continuation of the secular shift toward e-commerce that has accelerated during periods of high fuel prices, when consumers consolidate shopping trips. Restaurants and bars rose 1.2%, a discretionary spending category that tends to soften early when consumers pull back. Furniture and home furnishings gained 0.9%, and clothing and accessories rose 0.7%. None of those categories are tied to gasoline, and all of them outperformed the prior month.

July’s Dip Was an Anomaly, Not a Trend

The July decline that preceded August’s rebound had raised questions about whether the American consumer was finally hitting a wall. The revised 0.5% drop was the first monthly contraction in retail sales in several months, and it broke a string of positive readings that had been supported by World Cup spending, Amazon Prime Day sales, and the seasonal draw-down of tax refunds that lifted traffic in April and May.

August’s data effectively erased those concerns. The two-month pattern, a dip followed by a stronger-than-expected rebound, is consistent with timing-related noise rather than a structural downshift in consumer behavior. Shoppers who delayed purchases in July appear to have followed through in August, with the added tailwind of back-to-school spending across clothing, electronics, and general merchandise.

The year-over-year comparison provides more durable context. Total retail sales were up 6.0% compared to August 2025, and the rolling three-month June-through-August period was up 6.0% versus the same stretch a year ago. Those figures are not adjusted for inflation, which means real spending growth is lower than the nominal print suggests. But even after accounting for the 3.4% annual CPI rate reported for August, the inflation-adjusted year-over-year gain in retail sales remains positive, a signal that consumer spending volume, not just consumer spending in nominal dollar terms, is still expanding.

What the Data Means for the Fed’s Rate Decision

The retail sales report landed at 8:30 a.m. Eastern on September 16, the same morning the Federal Open Market Committee convened the second day of its September meeting. The timing was not coincidental; the Census Bureau’s release schedule is fixed, and the Fed schedules its meetings around the economic calendar. But the juxtaposition of a hot consumer spending print alongside a rate decision that had already been widely telegraphed as a hike added a specific dimension to the committee’s deliberations.

A Federal Reserve that is raising rates to contain inflation needs evidence that the economy can absorb tighter financial conditions without tipping into contraction. The August retail sales report provided that evidence in clear terms. Consumer spending, which accounts for roughly two-thirds of U.S. economic output, is not just holding up under elevated prices and higher borrowing costs. Consumer spending is accelerating on a monthly basis and maintaining positive real growth on a year-over-year basis. For the Fed, that is both reassurance and complication: reassurance that a rate hike will not push the economy off a cliff, and complication because the same spending strength that supports GDP also sustains the demand-side pressure that keeps inflation above target.

The Fed’s framework for how interest rate decisions are calibrated against incoming economic data depends on exactly this kind of report. A weak retail print would have raised the question of whether the committee was tightening into weakness. A strong print, which is what the committee received, shifts the question to how many more hikes the economy can absorb before spending begins to moderate in a way that would bring inflation closer to target without overshooting into contraction.

Where Consumers Are Spending and Where They Are Not

The category breakdown reveals spending priorities that business owners, retailers, and service providers can map against their own planning cycles. Online retail’s 2.6% gain confirms the channel’s continued share capture, particularly during periods of high fuel prices when the cost of driving to physical stores rises. Restaurants and bars at 1.2% indicate that dining-out spending, one of the first discretionary categories to contract during consumer pullbacks, remains healthy. The furniture and home furnishings gain of 0.9% suggests that housing-related spending, which had been weak for much of 2025 as mortgage rates rose, may be stabilizing even though borrowing costs have not come down.

Motor vehicles and parts rose 0.6%, a moderate gain that reflects a market where high prices and elevated financing costs have stretched purchase cycles but have not stopped transactions. Health and personal care stores posted gains, as did building materials and garden equipment dealers. The categories that declined or posted negligible growth were narrower: electronics and appliances were flat, and sporting goods, hobby, and bookstores saw marginal movement.

For small business owners tracking consumer behavior, the data points to a consumer who is spending broadly but selectively. The strongest gains came in categories where convenience (online retail), experience (restaurants), and necessity (clothing, groceries) converge. Categories that require large upfront outlays or carry higher price sensitivity showed more muted performance, consistent with a consumer who is willing to spend but is still price-aware.

The GDP Implications Are Measurable

The control group’s 1.4% gain carries specific downstream consequences for GDP modeling. The Bureau of Economic Analysis uses the control group as an input for its personal consumption expenditures estimate, which in turn drives the consumer spending component of quarterly GDP. A control-group print this far above consensus pushes the Q3 GDP tracking estimate higher, and several Wall Street forecasting desks updated their models within hours of the release.

The Atlanta Fed’s GDPNow model, which produces a real-time running estimate of quarterly growth, will incorporate the retail data into its next update. Prior to the August retail report, GDPNow and similar nowcasting tools had been projecting moderate Q3 growth in the range of 2.0% to 2.5%. A 1.4% control-group print could push that estimate materially higher, depending on how other September data releases track against expectations.

For entrepreneurs planning Q4 inventory, staffing, and marketing budgets, the retail data provides a concrete planning input. Consumer spending is not contracting. Consumer spending is not merely holding steady. Consumer spending accelerated in August to a degree that surprised the professional forecasting community, and it did so across categories broad enough to suggest the strength is not isolated to a single sector or a single price effect. The question heading into the holiday quarter is whether that momentum sustains through September and October, or whether the combination of higher borrowing costs, elevated fuel prices, and the uncertainty created by the Fed’s tightening cycle introduces friction that slows the pace. The August report, taken on its own, gives more reason for confidence than caution.

FAQs

How Much Did U.S. Retail Sales Rise in August 2026?

U.S. retail and food services sales rose 1.2% in August 2026 to $773.9 billion, according to the U.S. Census Bureau’s Advance Monthly Retail Trade Survey released September 16. The gain nearly doubled the 0.7% increase economists had anticipated and reversed July’s revised 0.5% decline.

Which Retail Categories Grew the Fastest in August 2026?

Online retailers led with a 2.6% monthly gain. Restaurants and bars rose 1.2%, furniture and home furnishings rose 0.9%, clothing and accessories rose 0.7%, and motor vehicles and parts rose 0.6%. Excluding gas stations, overall retail sales still rose 1.1%, indicating the strength was not driven solely by higher fuel prices.

What Is the Retail Sales Control Group and Why Does It Matter?

The control group is a subset of the Census Bureau’s retail sales data that excludes autos, gas stations, building materials, and food services. It matters because the Bureau of Economic Analysis uses it as a direct input for calculating the personal consumption expenditures component of quarterly GDP. In August 2026, the control group rose 1.4%, nearly three times the 0.5% consensus estimate.

How Do August 2026 Retail Sales Compare to the Same Period Last Year?

Total retail sales in August 2026 were up 6.0% compared to August 2025. The rolling three-month June-through-August period was also up 6.0% versus the same stretch a year earlier. These figures are not adjusted for inflation; after accounting for the 3.4% annual CPI rate, real spending growth remains positive but lower than the nominal comparison.

Bishop Gold Group Explains the Difference Between Owning Gold and Having Exposure to Gold

As investors reconsider the role of precious metals in their portfolios, Bishop Gold Group says understanding what an investor actually owns may be just as important as deciding to gain exposure to gold in the first place.

Gold is often discussed as though it were a single investment category. In practice, however, there are several very different ways to participate in the gold market.

An investor might purchase physical coins or bars, buy shares of a gold-focused exchange-traded fund, invest in mining companies, or hold precious metals through certain retirement-account structures. Each may provide some connection to the gold market, but they do not necessarily provide the same ownership experience, risks, costs, or level of control.

According to Bishop Gold Group, understanding those distinctions is an important part of evaluating precious metals.

For investors considering gold as part of a broader diversification strategy, the first question may therefore be more specific than simply, “Should I own gold?”

It may be: “What exactly do I want to own?”

Gold Exposure Can Take Different Forms

One of the simplest distinctions is between owning physical gold and owning a financial instrument whose value is connected in some way to the gold market.

Physical gold generally refers to bullion products such as coins and bars. Once a transaction is completed, the buyer owns a tangible asset that must be delivered, stored, insured or otherwise safeguarded.

Other approaches can provide gold-related exposure without requiring the investor to personally take possession of metal. Exchange-traded products, for example, may allow investors to buy and sell shares through brokerage accounts. Gold-mining stocks provide another type of exposure, but their performance depends not only on the price of gold, but also on the financial and operational performance of the underlying companies.

These distinctions matter because two investors who both say they “invest in gold” may actually own fundamentally different assets.

Physical Ownership Changes the Relationship With the Asset

For some buyers, the tangible nature of physical gold is part of its appeal.

Unlike a stock or fund represented by an entry in a brokerage account, a gold coin or bar is a physical asset. Depending on the ownership arrangement, the owner may take direct possession or arrange for storage through a third party.

That tangibility can provide a degree of control that certain investors specifically seek. At the same time, it introduces responsibilities that do not necessarily exist with securities held electronically.

Physical gold must be securely stored. Insurance considerations may arise. Buyers should retain transaction and ownership records, understand applicable premiums and fees, and know how the asset could eventually be sold or transferred.

Bishop Gold Group emphasizes that these practical considerations should be understood before a transaction takes place rather than after the metal has already been purchased.

Convenience and Control Are Not Necessarily the Same Thing

Financial products connected to gold may offer conveniences that physical ownership does not.

Shares of publicly traded gold-related products can generally be bought and sold through brokerage platforms during market hours. Investors do not typically need to personally arrange transportation or physical storage of the underlying asset.

Physical gold works differently.

Buying or selling bullion may involve communicating with a dealer, receiving a quote, arranging payment or settlement, completing verification procedures, and coordinating delivery or storage.

Neither structure is inherently appropriate for every investor. Instead, the distinction illustrates an important tradeoff: the structure offering the greatest convenience may not necessarily provide the same form of ownership or control as possessing the underlying physical asset.

That difference can be particularly relevant for investors whose interest in precious metals is motivated by diversification beyond conventional financial accounts.

Investors Should Understand What They Are Trying to Accomplish

The appropriate form of gold exposure depends largely on the investor’s objective.

Someone interested primarily in short-term price movements may approach the market differently from someone purchasing physical bullion as a long-term holding. A retirement investor may face another set of considerations involving account structure, custodians, eligible precious metals, and storage requirements.

Before selecting a product, investors can consider several questions.

Do they want direct ownership of physical metal? How important is immediate liquidity? Are they comfortable arranging storage? What fees will apply when buying, holding, and eventually selling the asset? Is the objective short-term market exposure, long-term diversification, retirement planning, or tangible ownership?

Answering those questions can make it easier to compare options on their actual characteristics rather than treating every gold-related product as interchangeable.

Physical Gold Also Has Costs and Risks

Direct ownership should not be interpreted as eliminating investment risk.

Gold prices fluctuate, and physical gold does not ordinarily produce interest or dividends. Buyers may also pay premiums above the prevailing market price, along with potential shipping, insurance, storage, or administrative expenses.

When the metal is eventually sold, the price offered by a dealer or other buyer may differ from the price at which similar products are being sold to consumers.

These costs can affect the financial outcome of ownership and should be considered alongside the perceived benefits of holding a tangible asset.

Bishop Gold Group encourages consumers to understand the complete transaction, including pricing, premiums, storage arrangements, delivery procedures, and potential resale options, before making a purchase.

Education Becomes More Important as the Options Expand

The number of ways investors can gain exposure to gold makes financial literacy particularly important.

Consumers should understand whether they are purchasing physical metal, shares of a fund, stock in a mining company, or another gold-related financial product. They should also distinguish general educational information from individualized investment, tax or legal advice.

For physical precious metals, buyers can request written information regarding pricing, fees, delivery, storage, and resale procedures. Investors considering securities or retirement accounts should similarly review the applicable disclosures, expenses and regulatory requirements.

Gold has been owned and traded for centuries, but modern investors now have more ways to participate in the market than previous generations did.

That variety creates choice, but it can also create confusion.

For Bishop Gold Group, the distinction ultimately comes back to investor education. Understanding the difference between owning gold itself and owning something connected to gold allows consumers to evaluate the asset based on what they actually want from it.

For investors who value tangible ownership, physical gold may offer characteristics that financial products cannot replicate. For others, different forms of exposure may better fit their liquidity needs, risk tolerance, or financial objectives.

The important point is understanding the difference before making the decision.

Gold-related investments and physical precious metals involve risk and may lose value. Gold does not guarantee protection against inflation, market declines, or other financial losses. Investors should consider their individual circumstances and consult appropriately qualified financial, tax or legal professionals when necessary.

Disclaimer: This article is for informational purposes only and does not constitute financial, investment, tax or legal advice. Gold and other precious metals involve risk, may lose value and do not guarantee protection against inflation, market declines or other financial losses. Investors should evaluate their individual circumstances and consult qualified professionals before making investment decisions.

Allen Spearman Breaks Down the Journey from HVAC Journeyman to Master

At some point in an HVAC technician’s career, the work starts to feel different.

A service call that once required help from someone more experienced becomes one the technician can handle alone. An unfamiliar system is still unfamiliar, but the process for figuring it out isn’t. The technician knows which measurements to take, which questions to ask, and when an apparent solution doesn’t quite make sense.

That kind of confidence doesn’t necessarily arrive when someone earns a new license.

It develops over years spent working on equipment, making mistakes, seeing the same problems in different forms, and learning the trade by doing.

For Allen Spearman, that’s an important part of understanding the progression from apprentice to journeyman and eventually master. Licensing marks key stages in the process, but the bigger change is how much responsibility a technician is prepared to handle.

What the Apprenticeship Is Really Teaching

HVAC licensing requirements vary considerably by state and jurisdiction, but apprenticeship generally combines supervised field experience with technical instruction.

Early on, much of the learning is basic and practical.

An apprentice has to become comfortable with tools, job-site safety, equipment, and the routines that experienced technicians barely think about anymore. There is also a difference between understanding a refrigeration cycle in class and standing in front of a system that isn’t behaving the way the diagram says it should.

That gap is where a lot of the learning happens.

As apprentices gain experience, they begin doing more diagnostic work themselves. Low suction pressure, for example, doesn’t point automatically to one problem. Refrigerant charge, airflow, restrictions, and other conditions may need to be checked before the technician knows what’s actually happening.

The measurements start to mean more because the apprentice has seen what those numbers look like on real systems.

Administrative work also adds up. When licensing requires documented experience, technicians need to make sure their hours and other qualifications are recorded properly.

It’s a small habit that can matter years later, when they’re ready for the next step.

What Changes During the Journeyman Years

Earning a journeyman license can give a technician more independence, although exactly what that license permits depends on the jurisdiction.

The more interesting change happens in the work itself.

By this stage, a technician has usually encountered many of the same problems more than once. A condenser fan motor isn’t new anymore. Neither is a system with poor airflow or a unit installed in a way that makes an otherwise simple repair much harder.

Repetition gives technicians something a textbook can’t.

They begin recognizing patterns. They also learn when a familiar-looking problem isn’t behaving quite like the last one.

As Allen Spearman has written about the trade, these years are also when technicians begin establishing how they work when no one is standing over their shoulder.

Do they take the extra measurement? Do they check their initial diagnosis before replacing a part? If a repair doesn’t solve the problem, do they go back through the system methodically or start guessing?

Experience can make a technician faster, but it can also reinforce shortcuts.

Someone who becomes accustomed to sizing equipment by rule of thumb may keep doing it. A technician who routinely skips a diagnostic step because it usually isn’t necessary can eventually encounter the job where it was.

More independence makes those habits increasingly important because someone else may no longer be checking the work.

Preparing for the Master’s Exam

The step from journeyman to master introduces another set of responsibilities.

Requirements vary by location, but master-level licensing can require additional experience and exams covering areas such as mechanical codes, system design, business requirements, and overseeing permitted work.

That changes how a technician prepares.

A code book isn’t particularly useful if someone tries to memorize every page. Technicians need to understand how it is organized and become comfortable finding the section that applies to the problem in front of them.

Practice exams can help with that, especially when the test is timed.

Some of the habits developed through diagnosing systems under pressure carry over. When a technician doesn’t immediately know an answer, they still need a process for finding it.

Master-level responsibility can also extend beyond the technician’s own work.

Depending on local requirements and the type of license involved, a master may be responsible for permits or for work performed under their supervision. At that point, knowing how to complete a job correctly is only part of the responsibility.

The technician also has to know how to evaluate work completed by someone else.

Codes and Load Calculations Change the Work

One of the biggest changes at the master level is the attention paid to design.

Installing equipment that has already been specified differs from deciding what equipment to install in the first place.

That can mean working with Manual J load calculations, Manual D duct design, and Manual S equipment selection instead of relying on square footage or simply replacing an existing unit with another of the same size.

It also requires attention to ventilation, combustion air, condensate management, and applicable mechanical codes and local requirements.

These aren’t necessarily the parts of HVAC work customers notice.

They may notice the results, though.

A system has to heat or cool the building it serves, move air where it needs to go, manage humidity where that’s a concern, and operate without creating unnecessary comfort or performance problems.

Getting those decisions right before installation can prevent technicians from solving avoidable problems afterward.

Learning to Work Without Doing All of It Yourself

For technicians moving into supervisory or contractor roles, another adjustment has little to do with refrigeration or electrical systems.

They have to let other people do the work.

A technician who has spent years becoming good at a task may be able to complete it faster than the apprentice standing beside them. Taking over every time the apprentice struggles solves the immediate problem, but it doesn’t give that person much opportunity to improve.

Teaching requires a different kind of patience.

The same is true when managing experienced technicians. A person overseeing several jobs can’t personally diagnose every system, review every installation, answer every customer question, and still have time to run the rest of the work.

That means deciding what needs their attention and what someone else can handle.

For Spearman, this is one of the less obvious changes that comes with moving further up the trade.

Technical skill still matters. It just isn’t the only skill being used anymore.

Advice for Technicians Making the Climb

For technicians interested in moving from apprentice to journeyman and eventually toward master-level responsibility, a few habits can make the progression easier:

  • Log everything from day one. If a licensing board requires documented experience, keep those records while the work is happening.
  • Learn how to use the code book. Knowing where to find an answer is often more useful than memorizing everything.
  • Take the measurements. Static pressure, superheat, subcooling, combustion readings, and other diagnostic information can confirm whether the first assumption was actually right.
  • Ask experienced technicians questions. Seeing how someone else approaches an unfamiliar problem can shorten the amount of time it takes to develop your own process.
  • Give experience time to accumulate. Passing an exam and developing judgment aren’t necessarily the same thing.

The exact timeline varies because licensing rules, training programs, and career paths differ everywhere.

What doesn’t change as much is the amount of repetition involved.

A technician becomes more capable by working through one system, then another, and eventually realizing that today’s problem resembles something they struggled with years earlier.

The difference is that this time, they know where to start.

About Allen Spearman

Allen Spearman works in the heating, ventilation, and air conditioning field. He writes about the technical and career sides of the trade, with a particular focus on how technicians move from supervised work to independent responsibility.

His background building a career in the mechanical trades informs his commentary for apprentices and journeymen considering their next steps, including the changes in diagnostics, system design, and responsibility that come with greater experience in the field.

Paul Davis Restoration of Tri-County, MD Emphasizes Local Roots and In-House Cost Savings

By: Chloe Martin

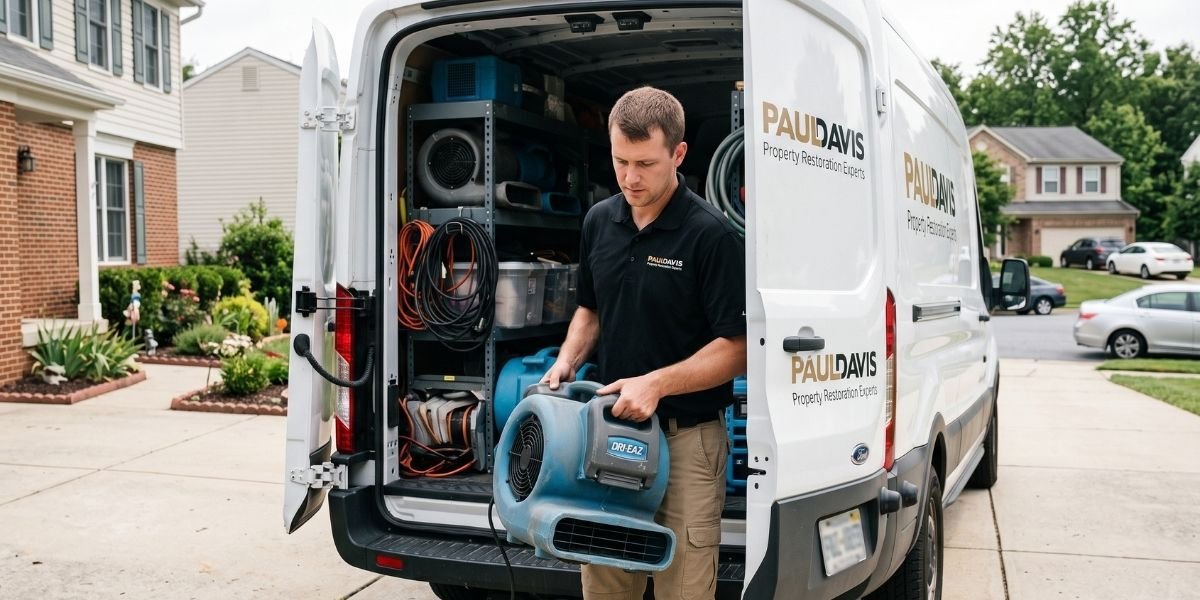
Homeowners across Southern Maryland often navigate a restoration project without knowing what to expect from a company they’ve never worked with before. Paul Davis Restoration of Tri-County, MD has built its reputation locally in part by leaning into that familiarity, pairing being a known, community-based business with an in-house structure designed to keep costs down for clients.

A Locally Owned Company That Knows the Region

Owner Jeff McCarthy points to the company’s local roots as central to how it operates day-to-day. “As a locally owned and operated company, we understand the communities we serve and the issues that affect them,” he said. That local knowledge extends into full-service coordination on a project, including managing subcontracts and negotiating directly with insurance adjusters so a homeowner isn’t left tracking down multiple parties on their own. In La Plata, where many properties are managed by owners who don’t have time to coordinate several vendors during a loss, that single point of coordination is treated as a core part of the service rather than an added convenience.

Passing Savings Directly to Clients

McCarthy also points to the company’s internal structure as a pricing advantage. “Through our in-house project management and direct supplier relationships, we focus on finding savings and passing those savings on to our clients,” he said. Rather than marking up costs through layers of subcontractors, the company says its direct supplier relationships and in-house oversight are built specifically to keep those savings visible on a client’s final invoice rather than absorbed along the way.

A Culture Built Around Doing the Right Thing

Beyond the technical and financial side of the business, McCarthy describes the company’s culture in values-based terms. “Our people and this company are anchored on a set of values based on doing the right thing: serving every customer by delivering an experience founded on professionalism, expertise, and compassion,” he said. That framing is meant to guide how technicians handle even small decisions on a job site, not just the major calls that show up in a final invoice.

What Tri-County, MD Clients Are Saying

Recent client feedback consistently highlights the team’s patience and follow-through. GARY M. said Orlando arrived on time after a same-day call, was courteous and patient in answering every question, and even looked into a separate, unrelated issue during the same visit. Dr. Joan M. described extensive water damage discovered in a newly purchased home in Chesapeake Beach, saying the team’s construction and engineering knowledge guided her family’s decisions throughout the repair and even helped install a new window with a full Chesapeake Bay view once the structural work was complete. Desiree M. praised technicians Orlando and Kamari for handling her belongings with white-glove-level care during a water damage cleanup, saying their patience and thorough cleanup made a difficult home deconstruction far more manageable.

Does Paul Davis Restoration Of Tri-County, Md Coordinate Directly With Insurance Adjusters?

Yes. The company negotiates with insurance adjusters and can coordinate subcontracts directly, so homeowners aren’t left managing multiple parties during a claim.

How Does The Company Keep Costs Down For Clients?

Through in-house project management and direct supplier relationships, the company says it captures savings that would otherwise be absorbed by layers of subcontractors and passes them on to clients.

What Values Guide How The Company Operates?

The company describes its culture as centered on professionalism, expertise, and compassion, with an emphasis on doing right by every customer regardless of the size of the job.

What Areas Does Paul Davis Restoration Of Tri-County, MD Serve?

The franchise serves Lexington Park, California, Waldorf, La Plata, Indian Head, Leonardtown, Bensville, Lusby, Prince Frederick, Chesapeake Beach, and Huntingtown, Maryland.

Stay Connected With Paul Davis Restoration of Tri-County, MD

For storm season alerts and project updates, residents can follow Paul Davis Restoration of Tri-County, MD on Facebook and LinkedIn.

Why “Just Apply and See” Is Bad Advice for Business Financing

Business owners exploring financing options often hear the same casual advice: just apply and see what happens. On the surface, this seems harmless, even efficient. In practice, it frequently costs business owners real time, unnecessary stress, and sometimes a meaningful hit to their confidence, all avoidable with a few minutes of preparation beforehand.

The Real Cost of Applying Blind

Submitting an application without any prior sense of qualification means accepting a genuine gamble on the outcome. A business owner who applies blind and gets declined has lost the time invested in that application, and often walks away with little useful information about why, since a decline rarely arrives with a genuine, factor-by-factor explanation. Multiple declines can compound this problem considerably, leaving a business owner increasingly discouraged even if their business has genuinely grown stronger between attempts.

There’s also a quieter cost to this approach: business owners who assume, often incorrectly, that their business isn’t strong enough, and therefore never apply at all. Without any way to check their actual standing, genuinely qualified businesses sometimes avoid pursuing financing they would have easily secured, simply because uncertainty felt like enough of a reason to hold back.

A Better Starting Point Than Guessing

Fundivi, a direct lender and hybrid funding platform, built a free tool specifically to replace this guesswork. The self-underwriting engine lets a business owner enter nine real numbers, revenue, balance, negative balance days, time in business, credit score, state, industry, open positions, and existing payments, and see an immediate, honest outlook with no credit pull and nothing submitted anywhere.

This single step replaces “just apply and see” with something considerably more useful: “check first, then apply with genuine confidence.” A business owner whose numbers clear the published thresholds can move forward knowing their odds are genuinely favorable. A business owner whose numbers fall short on a specific factor gets a clear target to address before trying again, rather than a vague decline with no actionable direction.

Why This Matters Even More When Choosing a Product

The same logic applies to product selection. Applying for a term loan simply because it’s the most familiar structure, without checking whether working capital or a line of credit might genuinely fit better, risks ending up with financing that technically works but doesn’t actually solve the underlying need efficiently. The funding product matcher addresses this directly, walking through eleven questions before recommending the product that actually fits, with the reasoning shown plainly.

Why “Just Apply” Advice Persists Despite the Downsides

This advice endures partly because, for most other kinds of purchases, applying and finding out is genuinely the only practical option available. A consumer applying for a credit card or an auto loan usually has no meaningful way to preview their odds beforehand beyond a general sense of their own credit score. Business financing has historically operated the same way, with underwriting criteria treated as proprietary information rather than something a business owner could check independently in advance.

The advice also persists because it isn’t entirely wrong in every situation. A business owner with an obviously strong, well-established profile may genuinely have little to lose by applying directly, since their odds of approval were always going to be high regardless of any preliminary check. The problem arises specifically for business owners closer to the margin, where a genuine preview of their standing could meaningfully change how, when, or whether they choose to apply at all.

How Preliminary Checking Changes the Actual Decision

Once a business owner has genuine visibility into their own numbers, the decision about whether and how to apply becomes considerably more deliberate. A business owner who discovers their leverage is running high relative to revenue might choose to pay down an existing obligation first, rather than applying immediately and risking a decline tied specifically to that factor. A business owner whose credit score sits just below a clear threshold might choose to wait a few months while making consistent on-time payments, rather than applying today and accepting worse odds than a short delay might have produced.

None of these more deliberate choices are available to a business owner who simply applies and sees what happens. The blind approach forecloses exactly the kind of strategic patience that a few minutes of genuine preparation can unlock, often at real cost to the eventual outcome.

What Changes Once the Guesswork Is Removed

Business owners who check their numbers before applying consistently describe a genuinely different relationship with the entire financing process, one built around informed decision-making rather than hopeful submission. This shift matters beyond just the immediate application at hand, since a business owner who develops the habit of checking their standing periodically, rather than only when a specific need arises, tends to approach every future financing decision with considerably more confidence and strategic clarity.

How This Applies Specifically to Repeat Financing Needs

Business owners rarely need financing only once. A business that successfully secures working capital today will likely face another financing decision months or years down the road, whether for a growth opportunity, a seasonal cash flow gap, or an unexpected expense. Business owners who built the habit of checking their numbers before their first application are considerably better positioned for every subsequent decision as well, since they already understand which specific factors matter most and how their own business’s numbers typically compare against real thresholds.

This ongoing habit becomes particularly valuable for businesses with genuinely seasonal or cyclical revenue, where qualification standing can shift meaningfully throughout the year. A business owner who only ever checked their numbers once, during an unusually strong month, might apply during a genuinely weaker stretch without realizing how much their standing has shifted since that original check, precisely the kind of miscalculation a quick, repeated check would have caught in advance.

Why Lenders Rarely Encourage This Kind of Preparation

It’s worth asking why “just apply and see” remains such common advice when a better alternative genuinely exists. Part of the answer lies in incentives: many lenders benefit from a steady volume of applications regardless of each individual applicant’s actual odds, since even a considerable decline rate doesn’t meaningfully hurt a lender’s business the way it costs the declined business owner real time and effort. A lender with no incentive to reduce its own application volume has little reason to actively encourage business owners to check their odds before applying.

Fundivi’s decision to build and promote free, public tools that might reduce its own raw application volume, by helping some business owners recognize in advance that they’re not yet ready, reflects a genuinely different set of priorities, one that treats a business owner’s time and confidence as worth protecting even when doing so doesn’t maximize the lender’s own short-term application numbers.

Frequently Asked Questions

Isn’t it faster to just apply directly instead of checking first?

Checking first typically takes only a few minutes and can save considerably more time overall by avoiding an application likely to end in decline, or one for the wrong product entirely.

Does checking my numbers first affect my credit score?

No. The underwriting tool and product matcher both perform no credit pull. They calculate entirely from the numbers you enter, with nothing submitted or stored.

What if I check my numbers and the outlook looks weak?

That’s genuinely useful information rather than a discouraging outcome. The tool shows specifically which factor is holding the outlook back, giving you a concrete target to address before applying rather than an unexplained decline afterward.

Is checking first only useful for first-time applicants?

No. Business owners who have been declined before, or whose business has changed since a previous application, benefit considerably from checking their current numbers before assuming a past outcome still reflects where they stand today.

Can I trust the result enough to skip a real application entirely?

The result is a genuinely useful indicative estimate, not a final decision. It’s meant to inform whether and how to move forward with a real application, not to replace one.

Getting Started

Business owners ready to move past guesswork can check their numbers directly, confirm which product genuinely fits their need, and once an offer arrives, use the cost calculator to confirm it’s genuinely fair before signing anything. For a deeper understanding of how each financing option actually works, Fundivi’s guide library covers the details behind every product in plain language.

NFIB Small Business Optimism Index Slips to 98.7 in August as Sales Weaken and Inflation Pressure Persists

The NFIB Small Business Optimism Index fell 1.1 points to 98.7 in August 2026, missing the consensus forecast of 99.3 and reversing most of July’s 2.4-point gain that had pushed the index to its highest reading in a year. The pullback signals that the surge in confidence reported a month ago was narrower than it appeared, driven largely by a temporary improvement in hiring sentiment rather than broad-based momentum across the ten components that make up the index.

Key Takeaways

  • The NFIB Small Business Optimism Index declined to 98.7 in August from 99.8 in July, missing the consensus estimate of 99.3; the index remains above its 52-year average of 98.0.
  • The Uncertainty Index fell 2 points to 89 but remains well above its historical average of 68, reflecting sustained ambiguity around trade policy, inflation, and business expansion timing.
  • NFIB Chief Economist Bill Dunkelberg identified weakened sales, supply chain disruptions, and persistent inflation as the primary headwinds facing small business owners in August.
  • The Employment Index edged down 0.3 points to 101.8 from 102.1 in July; July had seen a seasonally adjusted 36% of owners report unfilled job openings, up 4 points from June and the highest reading since June 2025.
  • The August miss relative to consensus was roughly twice as steep as forecasters expected, suggesting that July’s eight-component improvement overstated the underlying trend.

August Data Reverses July’s Broad-Based Gains Across Index Components

The National Federation of Independent Business released the August results on September 8, 2026. The survey, conducted among NFIB’s membership of small and independent business owners, has tracked monthly sentiment since 1986 and quarterly sentiment since 1973. The index is a composite of ten seasonally adjusted components that collectively capture how small business owners assess their operating environment, including expectations for sales, capital spending plans, hiring intentions, inventory levels, and their outlook for the broader economy.

July’s report had been notably strong. Eight of the ten components improved, pushing the index to 99.8, above its 52-year average of 98.0 for the first time since August 2025. Hiring plans improved substantially and contributed more to the July gain than any other component. A seasonally adjusted 36% of owners reported job openings they could not fill, up 4 points from June and the highest reading since June 2025. That labor market signal, combined with gains across capital expenditure plans and expansion expectations, had prompted some analysts to suggest that small business sentiment was finally stabilizing after months of volatility.

The August data complicates that interpretation. The 1.1-point decline brought the index back below 99, and the miss relative to the 99.3 consensus estimate suggests that forecasters had expected the July momentum to hold. Instead, the reversal points to a familiar pattern in 2026 NFIB data: isolated months of improvement followed by pullbacks, rather than a sustained upward trajectory. The index has not strung together three consecutive months of gains since late 2024.

Inflation, Weak Sales, and Supply Chain Disruptions Drive the Pullback

NFIB Chief Economist Bill Dunkelberg attributed the August decline to a combination of weakened sales, supply chain disruptions, and persistent inflation pressures. Dunkelberg noted that while expectations for the overall economy dimmed, small business owners remained “largely positive in the health of their own businesses.” That divergence between macro pessimism and firm-level confidence has been a recurring feature of the NFIB survey throughout 2026. Owners continue to report adequate demand for their own products and services even as they express doubt about the direction of the national economy.

Inflation has remained a dominant concern for NFIB respondents for more than four years. In earlier 2026 surveys, roughly 20% to 25% of small business owners identified inflation as their single most important problem, consistently ranking it alongside labor quality as one of the top two issues. The persistence of that reading reflects the reality that input costs for small businesses, including materials, freight, insurance, and wages, have remained elevated even as headline consumer inflation has moderated from its 2022 peaks. Small businesses typically lack the pricing power and procurement leverage that larger firms use to absorb or pass through cost increases, leaving them more exposed to sustained input price pressure.

Supply chain disruptions reentered the conversation in August after several months of relative stability. The timing aligns with the escalation in U.S.-Canada trade tensions, which produced new tariffs on both sides of the border. Canada’s retaliatory tariffs on $27.6 billion in U.S. goods took effect on September 8, and the anticipation of those duties may have influenced August survey responses among businesses that import materials from or export goods to Canada. Steel, aluminum, dairy, agricultural equipment, pulp and paper, and electronics are all affected by the new tariff regime.

The Uncertainty Index Remains Elevated Despite a Two-Point Decline

The NFIB Uncertainty Index fell 2 points to 89 in August, continuing a modest decline from its recent peak. The August reading, while lower than July’s 91, remains well above the historical average of 68. The persistent gap between the current reading and the long-term average reflects the degree to which small business owners continue to operate without clear visibility into the policy environment. Trade negotiations between the U.S. and its major partners have produced unpredictable outcomes throughout 2026. Federal Reserve policy under Chair Kevin Warsh has added another layer of ambiguity, with a 9-to-9 split among FOMC participants on the directional outlook for rates and a median fed funds rate projection that has shifted upward since March.

For small business owners weighing expansion decisions, hiring commitments, or capital expenditures, that combination of trade uncertainty and monetary policy ambiguity creates a planning environment in which caution is rational. The Uncertainty Index has remained above 80 for 14 of the past 18 months, a stretch that coincides with the period during which the NFIB Optimism Index has oscillated without establishing a sustained trend in either direction.

The Employment Index Softens After July’s Hiring Surge

The NFIB Employment Index edged down 0.3 points in August, registering 101.8 compared to 102.1 in July. July’s reading had marked an uptick after four consecutive months of decline, driven by a jump in reported job openings and hiring plans. The modest August decline suggests that the labor market signal embedded in July’s data may have been a one-month correction rather than the start of a new hiring cycle.

Labor dynamics remain one of the more complex elements of the small business landscape in 2026. Owners have reported persistent difficulty filling positions for more than two years, but the nature of the problem has shifted. In 2022 and 2023, the primary complaint was the inability to find qualified applicants at any wage. By 2026, the challenge has become more nuanced: applicants are available, but the cost of hiring them, retaining them, and absorbing the associated payroll tax and benefits obligations has risen enough to make owners cautious about adding headcount. That caution is reflected in the Employment Index’s failure to sustain gains above 102 for more than a single month at a time.

The August NFIB data also arrives in the context of broader labor market cooling. The Bureau of Labor Statistics reported that nonfarm payrolls rose by just 57,000 in June, the weakest monthly gain in four months, and private-sector hiring as measured by ADP came in at 98,000 in June, below expectations. Small business hiring sentiment and national payroll data do not always move in lockstep, but both are pointing in the same direction: a labor market that is softening at the margins without collapsing.

FAQs

What Is the NFIB Small Business Optimism Index?

The NFIB Small Business Optimism Index is a monthly composite of ten seasonally adjusted components that measure how small business owners view their operating environment. Published since 1986 by the National Federation of Independent Business, the index covers expectations for sales, hiring plans, capital spending, inventory levels, and the broader economic outlook. The 52-year average sits at 98.0.

Why Did the August 2026 Reading Miss Consensus?

Economists had forecast a modest dip to 99.3, expecting July’s gains to largely hold. Instead, the index fell 1.1 points to 98.7. NFIB Chief Economist Bill Dunkelberg attributed the miss to weakened sales, supply chain disruptions, and persistent inflation pressures weighing on owner expectations for the broader economy.

How Does the Uncertainty Index Compare to Its Historical Average?

The NFIB Uncertainty Index fell 2 points to 89 in August but remains well above its historical average of 68. The index has stayed above 80 for 14 of the past 18 months, reflecting ongoing ambiguity around trade policy, Federal Reserve rate decisions, and the broader regulatory environment affecting small business planning.

Title Search Automation, Understood Correctly: The Human-in-the-Loop Approach That Works

By: KeyCrew Media

Many automation vendors pitching to title companies see real opportunity in title search, and the results come from recognizing it as a blend of production work and judgment work. According to Jimmy Lewis of TrueFocus Automation, understanding this distinction is the single most valuable insight in the industry, and it is one he has refined since he began automating title search workflows around 2000 or 2001.

Why Title Search Rewards a Thoughtful Approach

The current wave of AI-driven automation tools works best, Lewis argues, when it keeps a clear separation between the production work of title search and the judgment work of title examination.

“We still heavily believe in keeping the human in the loop,” Lewis says. “There is a lot of work that can be automated, but we focus typically on the heavy lifting.”

That heavy lifting includes document retrieval, extracting information from those documents, and formatting that information so a searcher or examiner can review it efficiently. These are high-volume, repetitive tasks well suited to automation. The examination itself, the professional judgment about what those documents mean for a property’s title, is where human expertise shines.

The distinction matters because vendors who honor this line deliver a complete solution. They protect title companies by keeping the human expertise that catches what automated systems are not designed to handle.

The Capacity Opportunity Vendors Can Embrace

Lewis frames the value of title search automation as capacity expansion. When automation handles the production-heavy portions of the workflow, experienced searchers and examiners can process significantly more files while maintaining accuracy.

“If we can take 50, 60, 70 percent of that production work off of their hands, they’re able to do two to three times more than they have in the past,” Lewis says.

This reframing shapes how title companies can evaluate automation proposals. A vendor who makes searchers dramatically more productive offers a strong, sustainable path forward, one that keeps expertise available precisely when complex or high-value files call for it.

As more vendors enter the title automation space with tools built on large language models and machine learning, the most reliable approach pairs capable technology with human oversight. Lewis’s position is that the searcher’s expertise is a valuable risk management function that automation should support and strengthen.

Where the Line Is Drawn

Lewis identifies specific parts of the title workflow that benefit from human supervision no matter how capable automation tools become. Title exam and curative work, underwriting, wire releases and disbursements, fraud and identity verifications, and most processes that are considered irreversible all call for contextual judgment that experienced professionals provide.

“They’re the experts, and they need to make the final call,” Lewis says of searchers, examiners and settlement staff.

He acknowledges that this boundary may evolve. “It may be different in a year or two or three. We don’t know,” he says. Building on the current strengths of the technology, while letting it prove new capabilities over time, keeps transactions secure where accuracy carries real financial and legal weight.

For title companies evaluating vendors, Lewis’s framework suggests a practical and constructive question: ask the vendor not only what they can automate, but where they keep the human in the loop. A vendor who can clearly describe the limits of their own tools is offering a solution built around how title work actually gets done.

How TrueFocus Structures Its Workflow

TrueFocus Automation has built its Title Hunter® title search platform around the principle that automation should amplify human capacity and support human judgment. Title Hunter® handles document retrieval and classification, data extraction and doc prep, and an initial QC/fraud check, which tend to be the volume-intensive steps that consume the most time in a searcher's day, while routing the examination and decision-making steps to experienced staff.

Lewis says this architecture has allowed clients to increase throughput while preserving the quality controls that title insurance depends on. “We’re pretty confident that we’ve built the right solution with the human in the loop, and automated as much as we could,” he says. “As of today, title search automation works great on HELOC, Refinance, Loan Mods, and Property Reports files, especially in markets where there is at least 20-30 years of online data available.”

One recent example illustrates the approach at scale. A client was selected to help a customer clear a backlog of roughly 140,000 documents that needed to be recorded. After a few days of manual work to map the flow, TrueFocus built automation that reduced human involvement from roughly eight to nine minutes per document down to about one minute. The remaining time was handled by automation, allowing the client to complete the project without bringing in additional vendor partners.

TrueFocus has drawn a deliberate and thoughtful line between what automation should handle and what it should keep in expert hands. For title companies weighing their options, how a vendor answers the question of where that line falls reveals more than any feature list.

Jimmy Lewis is the CEO & Co-Founder of TrueFocus Automation, a specialist in RPA (robotic process automation) and AI-driven workflow automation for the title insurance, mortgage, and real estate industries. TrueFocus has developed 840+ automation bots supporting more than 2,500 workflows and has returned over 1.3 million production hours to clients.

Disclaimer: This article is intended for informational purposes only and does not constitute legal, financial, or investment advice. The views and opinions expressed herein reflect those of the individuals quoted and do not represent an endorsement of any company, product, or service mentioned. Readers should conduct their own due diligence and consult qualified professionals before making any investment decisions.

U.S. Trade Deficit Jumps 24.4% in July as Record Capital Goods Imports Signal an AI-Driven Spending Surge

The U.S. trade deficit widened 24.4% to $88.6 billion in July 2026, driven by a record-setting surge in capital goods imports as American businesses accelerated spending on computers, semiconductors, and computing accessories tied to artificial intelligence infrastructure. The Commerce Department’s Bureau of Economic Analysis and Census Bureau released the data on September 3, confirming what an advance goods-only report had flagged a week earlier: domestic demand for high-tech equipment is pulling imports into the country at a pace that is outrunning export growth and positioning trade to drag on GDP for a potential fourth consecutive quarter.

Key Takeaways

  • The U.S. goods and services trade deficit widened to $88.6 billion in July from $71.2 billion in June, a 24.4% increase that came in slightly below the Reuters consensus estimate of $90.0 billion.
  • Capital goods imports surged $14.4 billion to a record $140.3 billion, driven by computers, computer accessories, and semiconductors linked to the ongoing AI buildout.
  • Total imports rose 2.8% to $399.3 billion; goods imports climbed 3.7% to $320.6 billion.
  • Exports declined 2.1% to $310.7 billion, with goods exports falling 3.0% to $201.0 billion as industrial supplies and materials shipments dropped $8.7 billion.
  • The goods trade deficit widened 17.3% to $119.6 billion, partially offset by a services surplus of $31.0 billion.
  • Despite July’s spike, the cumulative trade deficit through the first seven months of 2026 is 29.6% smaller than the same period in 2025, with exports up 12.0% year-over-year and imports up only 1.9%.

Capital Goods Tell the Story Behind the Headline Number

The $14.4 billion jump in capital goods imports to $140.3 billion is the single data point that defines July’s report. The increase was concentrated in three categories: computers, computer accessories, and semiconductors. These are the physical inputs of the AI infrastructure cycle that has been reshaping corporate capital expenditure patterns across industries since 2024. When businesses build out data centers, upgrade server capacity, deploy AI training clusters, or integrate machine learning into production workflows, the equipment they purchase flows through the capital goods import line. July’s record reading indicates that the pace of that spending is still accelerating.

Oxford Economics senior U.S. economist Matthew Martin attributed the surge directly to business investment in high-tech equipment tied to the AI boom. The pattern is consistent with second-quarter GDP data, which showed strong business investment alongside robust consumer spending. The demand is real and it is being met, in large part, by foreign manufacturers. The United States designs many of the chips and systems that power AI infrastructure, but the fabrication, assembly, and component manufacturing remain concentrated in East Asia. Taiwan, which posted a $20.7 billion bilateral goods deficit with the United States in July, sits at the center of that supply chain.

Exports Fell as Crude Oil and Gold Shipments Declined

The export side of the ledger moved in the opposite direction. Total exports fell 2.1% to $310.7 billion, with goods exports dropping 3.0% to $201.0 billion. The decline was led by an $8.7 billion contraction in industrial supplies and materials, a category dominated by crude oil and nonmonetary gold. Crude oil exports have been volatile throughout 2026 as the conflict with Iran has disrupted global energy markets and shifted shipping patterns. Nonmonetary gold, which is excluded from GDP calculations, also contributed to the export decline but does not carry the same macroeconomic weight.

Capital goods exports moved in the opposite direction, rising $1.9 billion, and consumer goods exports increased $1.7 billion, lifted by pharmaceutical preparations. The divergence between the capital goods import surge and the more modest capital goods export gain underscores the structural reality of the current cycle: the United States is a net consumer of the hardware that powers AI, even as it remains the leading exporter of the software, services, and intellectual property that sit on top of that hardware.

The Bilateral Deficit Map Reveals Geographic Concentration

July’s bilateral trade data show sharp concentration among a handful of trading partners. Mexico posted the widest bilateral goods deficit at $26.3 billion, reflecting the continued flow of manufacturing output from cross-border supply chains. Vietnam followed at $24.8 billion, a figure that has grown steadily as companies have diversified production away from China. Taiwan’s $20.7 billion deficit is directly tied to the semiconductor supply chain and the AI capital goods surge. For businesses tracking where their supply chain exposure sits, these three markets account for a disproportionate share of the monthly swing.

Year-to-Date Numbers Tell a Different Story Than the Monthly Spike

July’s $88.6 billion deficit is a large number by any monthly measure, but the year-to-date trajectory provides necessary context. Through the first seven months of 2026, the cumulative U.S. trade deficit is 29.6% smaller than it was during the same period in 2025. Exports have grown 12.0% year-over-year, while imports have risen only 1.9%. The broader trend reflects a combination of factors: a weaker dollar through portions of the year that has made American goods more competitive abroad, the impact of tariff-related front-loading in early 2025 that inflated the prior-year baseline, and sustained global demand for American energy, agricultural, and pharmaceutical exports.

The July report, in other words, represents a sharp monthly deterioration within a broader annual improvement. Whether the annual trajectory holds depends in part on what happens to the tariff environment. The Supreme Court struck down reciprocal tariffs in a 6-3 decision in February 2026. RSM US calculates that the average effective tariff currently stands at 16.9%, and full implementation of the court’s ruling could reduce that to 9.1%. A decline of that magnitude would alter the import calculus for businesses that front-loaded inventory earlier in the year to beat tariff deadlines.

Inventory Data Suggest Businesses Are Still Building Buffers

Wholesale inventories for July came in at $959.1 billion, up 1.3% from June and 5.7% higher than July 2025. Retail inventories reached $838.5 billion, up 0.7% month-over-month and 3.8% year-over-year. The combination of rising imports and elevated inventory levels suggests that the import surge is not purely demand-driven. Businesses appear to be hedging against further tariff disruption by stacking goods now rather than risking higher costs or supply chain delays later. If effective tariff rates fall in the wake of the Supreme Court ruling, the incentive to pre-buy diminishes, and the import volumes that inflated July’s deficit may not repeat at the same intensity in subsequent months.

For the GDP calculation, the widening deficit means trade is positioned to subtract from third-quarter growth, potentially marking a fourth consecutive quarter of trade-related drag. The offset, however, is that the same domestic demand powering the import surge, consumer spending and business investment in AI infrastructure, is also the primary engine of GDP expansion. The deficit is a byproduct of strength, not weakness, even if its headline number tells a story that looks like deterioration.

FAQs

Why Did the Trade Deficit Widen So Sharply in July?

The primary driver was a $14.4 billion surge in capital goods imports to a record $140.3 billion, concentrated in computers, computer accessories, and semiconductors tied to AI infrastructure spending. At the same time, exports fell 2.1% as crude oil and industrial supplies shipments declined.

What Does the Trade Deficit Mean for GDP Growth?

A widening trade deficit subtracts from GDP because imports are counted as a negative in the national accounts calculation. July’s data position trade to act as a drag on third-quarter GDP for a potential fourth consecutive quarter. However, the domestic demand driving the imports, including business investment and consumer spending, is simultaneously the primary engine of economic growth.

Is the Trade Deficit Getting Worse Overall in 2026?

On a year-to-date basis, the cumulative trade deficit through July 2026 is 29.6% smaller than the same period in 2025. Exports have grown 12.0% year-over-year while imports have risen only 1.9%. July represents a sharp monthly spike within a broader annual improvement.

Which Countries Account for the Largest Bilateral Deficits?

In July 2026, Mexico posted the widest bilateral goods deficit at $26.3 billion, followed by Vietnam at $24.8 billion and Taiwan at $20.7 billion. Taiwan’s deficit is closely tied to the semiconductor and AI hardware supply chain.