Market Daily

Marketing Crunch Is Bringing A New Kind Of Accountability To Tech Marketing

For years, companies have had plenty of ways to evaluate the products they buy. Marketing services have been different. Choosing a PR firm, consultant, or individual marketer has often meant relying on referrals, past work, reputation, and whatever can be learned during a sales process.

Marketing Crunch is entering that gap with a simple idea: the people and companies shaping technology brands should be reviewable, too.

The new platform describes itself as the “Rotten Tomatoes of tech marketing,” bringing a review-driven approach to an industry where reputation has traditionally been difficult to compare from the outside.

Marketing Has A Reputation Problem

Marketing firms spend much of their time helping other companies build credibility. They develop positioning, shape narratives, secure attention, and manage how brands appear to the market.

But evaluating the firms themselves can be considerably harder.

A polished website can showcase impressive logos. A portfolio can highlight successful campaigns. Individual marketers can point to years of experience and recognizable companies they have worked with. None of those things necessarily tells a prospective client what working with that person or firm will actually be like.

That is where reviews can introduce a different layer of information.

Marketing Crunch is built around the idea that reputation should not exist only as a marketing message. It can also become something people research, discuss, and evaluate.

The Industry Behind The Industry

There is another reason the concept is interesting: marketing itself is not one market.

A startup might work with a boutique PR firm. A larger company might use a global agency. Another business may hire an independent strategist or rely heavily on individual consultants.

The people involved can matter just as much as the company name on the contract.

Marketing Crunch therefore puts both PR firms and individual marketers into the same broader conversation. That distinction matters because professional relationships often determine the quality of a marketing engagement.

The agency may provide the infrastructure, but individual people frequently become the face of the work.

Reviews Change The Research Process

A review platform does not replace a sales call, reference check, or examination of past work. Instead, it can become another piece of the research process.

That is particularly relevant in marketing, where outcomes can be difficult to define before a project begins.

A company may know that it wants more visibility, stronger positioning, better communications, or a more consistent brand. Determining who can deliver those things is considerably less straightforward.

A public review layer could give prospective clients another place to begin asking questions.

Reputation Becomes Part Of The Product

Marketing Crunch also reflects a broader shift in professional services.

Reputation is increasingly becoming something that exists beyond a résumé or company website. For marketers, that can mean the work they produce and the relationships they build become part of a more visible professional identity.

That creates a different dynamic for agencies and individuals alike.

Being good at marketing is one thing. Being willing to operate in an environment where the market can talk about your work is another.

A New Conversation For Marketing

Marketing Crunch is ultimately betting on something simple: people want more information before choosing who they trust with their reputation.

Whether the platform becomes a major destination for that research will depend on the quality and credibility of the conversation it creates. But the premise itself represents a notable change.

For an industry built around managing perception, Marketing Crunch is asking what happens when the marketers themselves become part of the review process.

The Hidden Perks of Hiring Full-Service Packing and Storage Services in the City

In New York, moving from one place to another has always involved more than simply filling up a truck and crossing town. With walk-ups, freight elevator availability, cramped corridors, curbside access, house guidelines, and traffic conditions that have the potential to turn what should be a quick journey into a full-day event, city moves call for preparation. One of the reasons for this growing popularity of packing and storage services is that fact.

A Full-Service Move Gets You Your Time Back

New Yorkers are no strangers to the idea of paying to save time. They pay for a quicker commute, they pay for grocery delivery, and even pay to have their tasks completed. Moving in New York City is the same kind of deal. Professional packing services can cover all aspects of packing, including labeling, organizing items, packaging of furniture, and preparation of rooms.

Manhattan moving companies’ recent statistics prove the change in preference. During the first quarter, packing was requested in 38.8 percent of local moves. The indicator clearly shows that for many city dwellers, hands-on assistance becomes part of the move itself rather than an additional service.

Storage Is Becoming Part of the Move Planning Process

The traditional approach to storage involved renting a space and forgetting about the issue. However, New Yorkers use the new approach where the necessity for temporary storage may occur due to various reasons like mismatched dates of closure, longer-than-planned renovations, staging of office furniture, or insufficient size of the apartment. The use of a moving company providing transportation and storage services will minimize the number of handovers.

Such a strategy is even more relevant considering that New York City pays much attention to transparency of self-storage operations and consumer rights protection. Recently, the city made some efforts related to better regulation of storage facilities.

Photo Courtesy: Vitaly Gariev on Unsplash

Housing Trends Can Change the Way New Yorkers Move

Packing and storage needs are often shaped by what is happening in the housing market. A move from Manhattan to a nearby suburb, a delayed closing, or the search for a larger home can create a temporary gap between one residence and the next, making short-term storage and flexible delivery more useful. Readers following these broader relocation patterns can visit NYC Industry Hub, which publishes New York business, real estate, housing, and local-industry coverage. Recent articles have examined demand in communities surrounding New York City and changing conditions in markets such as Long Island, providing useful context for residents deciding when and where to move.

Photo Courtesy: Unsplash.com

Single Moving Service, No More Surprises on Moving Day

When moving companies do not just move residences and businesses but also pack and store items, it becomes easier to be accountable. This is because there will be little likelihood of engaging in the age-old blame game involving the packing team, the truck driver, and the storage center. The moving service can have one single plan that will involve all aspects of packaging materials, pick-up time, transportation, short-term storage, and delivery. In the case of moving apartments, it will be easier to coordinate the process.

For readers comparing affordable movers in New York, Movers Not Shakers offers a practical example of how a city moving service can pair convenience with waste reduction. The company uses reusable packing boxes that get delivered prior to moving and picked up after unpacking in order to offer clients the option of not having piles of cardboard boxes after their move. Since space is always a concern in the city and clean-up may be seen as a challenge, it makes sense to use boxes that can be reused, which is convenient both for packing and for organizing the clean-up process.

Photo Courtesy: Unsplash.com

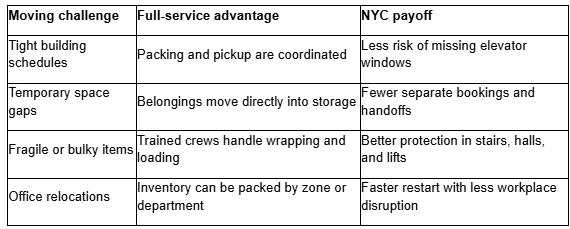
The Hidden Advantage Is Control

Perhaps the greatest advantage of full-service support might be predictability. Moving involves scores of potential pitfalls ranging from incomplete packing, fragile items requiring additional protection, delayed transfers, and possessions without a place to go until the new location is ready. In addition, the integration of packing, transportation, and storage provides greater flexibility if things do not go according to plan. It also allows clients to better understand which party is responsible for what.

That is the true luxury for New Yorkers. Best packing and storage services do not just help you pack your stuff. They take care of coordination, minimize clutter, save you time, and give you space in a city that hardly ever stops. Regardless of whether you are moving from a Brooklyn apartment or relocating your office from one district of Manhattan to another, a full-service approach can transform the moving process from chaotic into orderly.

Brought to you by SEO Guru, a dedicated SEO agency, AI SEO Services Provider, and Web Design Firm.

Why Uptown Common Is Betting on Slow Luxury in a Fast-Fashion World

Fashion moves quickly.

New collections arrive constantly. Trends emerge and disappear within weeks. Social media encourages consumers to discover, purchase, photograph, and replace products at a rapid pace.

Uptown Common is betting that some customers are ready for the opposite.

Founded by Grant and Jennifer Anderson, the independent leather goods company is building its identity around what might be called “slow luxury”: products made carefully, from quality materials, with the intention that they remain relevant long after a trend disappears.

The company began in 2019 and evolved gradually.

Jennifer initially created macramé products while Grant developed his leatherworking skills. Smaller leather accessories eventually grew into a broader collection, and in 2023, the couple decided to discontinue macramé and devote Uptown Common entirely to leather goods.

The change sharpened the company’s identity.

Uptown Common now produces handbags, briefcases, wallets, belts, clutches, shoulder bags, and related pieces, emphasizing traditional hand construction.

Its approach is deliberately labor-intensive.

According to the company, cutting, sewing, and hardware installation are performed by hand. Its vegetable-tanned leather is sourced primarily from Italy and the United States, while solid brass and stainless steel feature among its hardware choices.

Those details are part of how Uptown Common presents its products.

The company places emphasis on the process behind them.

Grant’s interest in leatherworking was partly inspired by discovering that a premium bag he had purchased wasn’t made with the quality of materials he expected. That realization led him deeper into understanding leather and eventually into making products himself.

Years later, that same attention to materials remains fundamental to Uptown Common.

Its aesthetic draws from minimalist and vintage design rather than rapid trend cycles. Structured shapes and understated detailing allow craftsmanship and leather to become the visual focus.

There is also something inherently personal about this approach.

Leather changes.

A bag carried through airports, offices, dinners, family gatherings, weekend trips, and everyday errands will eventually reflect the life of the person carrying it.

Instead of treating those changes as imperfections, Uptown Common’s philosophy embraces the idea that a well-made leather piece can develop greater character over time.

This creates a different proposition for consumers interested in long-term use and craftsmanship.

Uptown Common frames luxury less around scarcity, price, and brand recognition and more around craftsmanship, provenance, personalization, and emotional value.

Uptown Common’s recent expansion illustrates that approach.

In 2026, the company entered the Hamptons market with a Southampton pop-up at MORPHEW World. The event included personalization and a philanthropic component, positioning the brand within a broader lifestyle experience rather than simply a traditional retail transaction.

For a company that spent years participating in artisan markets, the Hamptons appearance represented another stage in its growth.

Yet Uptown Common’s fundamental proposition remains simple:

Make something well.

Use good materials.

Allow it to last.

And create something its owner will want to keep.

In a fast-moving fashion environment, slowing down may seem counterintuitive.

For Uptown Common, it may be exactly the point.

Consumer Sentiment Falls to 48.1 in September as Year-Ahead Inflation Expectations Climb to 4.6%

The University of Michigan’s final September consumer sentiment index fell to 48.1, down 7% from August and nearly 13% from a year earlier. It is the second-lowest reading since the survey began in 1952. Year-ahead inflation expectations rose to 4.6% from 4.0%, the highest level since June.

Key Takeaways

  • The final September reading of 48.1 came in above the preliminary estimate of 47.8 and the consensus forecast of 47.6, but below August’s 51.7 and September 2025’s 55.1.
  • Only May 2026’s record low has been weaker in the survey’s 74-year history.
  • Year-ahead inflation expectations rose to 4.6% from 4.0%, compared with 3.4% in February.
  • Five-year inflation expectations rose to 3.4% after three straight months at 3.3%, above the 2.8% to 3.2% range seen throughout 2024.
  • The Index of Consumer Expectations fell 10.1% to 46.3 from 51.5 in August.
  • Buying conditions for durable goods improved modestly as some consumers moved purchases forward to get ahead of expected price increases.

September Sentiment Undoes August’s Rebound

August briefly looked like a turning point. Consumer sentiment rose 7% that month to 51.7, its first meaningful gain in months. September erased all of it. The final reading of 48.1 is the lowest in four months and 15% below January 2026.

The final number was slightly better than the preliminary mid-month estimate of 47.8 and beat the Reuters consensus of 47.6. That modest upside surprise does not change the bigger picture. The index remains below levels recorded during the 2008 financial crisis, the pandemic shock, and the 1970s oil crisis.

Joanne Hsu, director of the University of Michigan’s Surveys of Consumers, said consumers reported roughly 10% deterioration in views of both their current and year-ahead personal finances, as worries about high prices kept building.

Inflation Expectations Move Further From the Fed’s Target

The inflation expectations data may matter more for markets and business planning than the headline index. Year-ahead expectations rose to 4.6% in September from 4.0% in August. That is a full 1.2 percentage points above February’s 3.4%, and higher than any reading in 2024.

Long-run expectations are the more concerning signal. Five-year inflation expectations rose to 3.4% after holding at 3.3% for three months. Throughout 2024, that measure stayed between 2.8% and 3.2%. A sustained move above that range suggests households increasingly see elevated inflation as a lasting feature of the economy rather than a temporary shock.

That matters to the Federal Reserve, which watches expectations closely because they can become self-fulfilling. When consumers expect higher prices, they tend to push for bigger raises and accept price increases more readily, which can make inflation harder to bring down. The Fed raised its benchmark rate by 25 basis points on September 16 to a target range of 3.75% to 4%, its first hike since July 2023. Most policymakers projected at least one more increase before year-end.

Consumer Expectations Fell More Than Current Conditions

The survey’s two components tell different stories. The Index of Consumer Expectations fell 10.1% to 46.3 from 51.5 in August, while the current conditions measure held up better. That gap shows the decline is driven more by worries about the months ahead than by what households are experiencing today.

The short-run outlook for business conditions dropped sharply. Respondents cited elevated fuel prices and renewed trade disputes as risks to the broader economy.

Retailers Face a Pull-Forward in Durable Goods Demand

One part of the report went against the overall trend. Buying conditions for durable goods such as appliances, furniture, and electronics improved modestly in September. The survey attributed part of that to consumers deciding to buy now to avoid higher prices later.

For retailers, this is a mixed signal. In the short term, it can support sales of big-ticket items heading into the fourth quarter. Over time, purchases pulled forward can leave a gap in demand once consumers have bought what they needed. Retailers planning holiday inventory should treat any September or October strength in durable goods with caution rather than assume it will continue.

Small business owners face a narrower margin for error. With consumers expecting 4.6% inflation over the next year and reporting weaker personal finances, their tolerance for price increases may be wearing thin. The NFIB Small Business Optimism Index for August already showed owners reporting weaker sales and ongoing inflation pressure, even as most remained confident about their own businesses.

What to Watch Next for Consumer Spending

The next major data point is the August Personal Income and Outlays report from the Bureau of Economic Analysis, scheduled for September 30. It will show whether weak sentiment is translating into weaker spending, and will update the PCE price index, the Fed’s preferred inflation measure. July PCE inflation was 3.7% year over year, with core PCE at 3.3%.

Higher borrowing costs add pressure from another direction. The average 30-year fixed mortgage rate rose to 7.03% the week of September 24, the first time above 7% since January 2025. For households already reporting weaker finances, higher financing costs on homes, cars, and credit cards put more strain on discretionary budgets.


Disclaimer: This article is for informational purposes only and is based on publicly available economic data and reported statements from the University of Michigan, the Federal Reserve, the Bureau of Economic Analysis, and other cited sources. Consumer sentiment, inflation expectations, interest rates, and spending patterns can change as new economic data becomes available. References to potential effects on consumers, retailers, small businesses, and financial markets are general analysis and should not be considered financial, investment, or business advice. Readers should consult official data releases and qualified professionals when making financial or business decisions.


FAQs

What was the University of Michigan consumer sentiment reading for September 2026?

The final September 2026 reading was 48.1, down from 51.7 in August and 55.1 in September 2025. It is the second-lowest reading since the survey began in 1952.

What are consumers’ inflation expectations for the next year?

Year-ahead inflation expectations rose to 4.6% in September from 4.0% in August. Five-year expectations rose to 3.4% from 3.3%.

Why did consumer sentiment fall in September?

Consumers reported roughly 10% worse views of their current and year-ahead personal finances as concerns about high prices intensified. Elevated fuel prices and trade disputes also weighed on the business outlook.

What does falling consumer sentiment mean for businesses?

Weak sentiment can point to more cautious spending ahead, especially on discretionary purchases. The September report also showed some consumers buying durable goods early to get ahead of expected price increases.

When is the next consumer spending data release?

The Bureau of Economic Analysis releases August personal income, spending, and PCE inflation data on September 30, 2026.

Uptown Common, The Luxury of Something Made to Last

In a fashion industry driven by speed, constant launches, and rapidly changing trends, Uptown Common is building its identity around a very different idea: permanence.

Founded by husband-and-wife team Grant and Jennifer Anderson, Uptown Common creates handcrafted leather goods designed not simply to be purchased, but to become part of the owner’s life. The brand’s structured handbags, wallets, belts, briefcases, and accessories reflect an approach to luxury rooted in materials, craftsmanship, functionality, and time.

Uptown Common’s story began in 2019, initially through Jennifer’s handmade macramé work. Grant subsequently brought his growing interest in leatherworking into the business, introducing wallets, notebooks, and keychains before the collection expanded into increasingly sophisticated leather pieces.

By 2023, the Andersons made an important decision: Uptown Common would focus completely on leather.

That decision helped define the brand consumers see today.

Grant’s interest in the craft began years earlier after discovering that a premium leather bag he had purchased was made from materials that didn’t meet the quality he expected. Rather than simply accepting the disappointment, he became interested in understanding leather itself, how it is sourced, constructed, stitched, shaped, and transformed into something capable of lasting for years.

That curiosity ultimately became a business philosophy.

Each Uptown Common piece is constructed by hand, including cutting, sewing, and hardware installation. The company uses vegetable-tanned leather sourced from Italy and the United States, along with solid brass or stainless-steel hardware.

The result is an aesthetic that feels both contemporary and timeless.

The company’s designs are influenced by minimalist and vintage principles, favoring clean structure rather than excessive decoration. It is an approach particularly relevant at a moment when many consumers are reconsidering what luxury actually means.

Is luxury a recognizable logo?

Is it exclusivity?

Or can luxury simply mean knowing who made something, understanding the materials behind it, and owning an object that wasn’t created to be replaced next season?

For Uptown Common, the answer increasingly lies in the latter.

Its bags are intended to change naturally with their owners. Leather develops character through use, allowing a piece to carry subtle reminders of travel, work, celebrations, daily routines, and personal milestones.

That philosophy also lends itself naturally to personalization. Rather than creating accessories that feel interchangeable, Uptown Common has emphasized individuality and craftsmanship as part of the customer experience.

The company has also begun moving beyond its Midwestern artisan-market roots and introducing its work to new luxury audiences. Its 2026 Hamptons debut included a Southampton pop-up at MORPHEW World, bringing the brand into an environment where fashion, vintage design, personalization, and philanthropy intersected.

Yet expansion hasn’t erased the original idea behind the company.

Uptown Common remains grounded in the maker’s hand.

For Grant and Jennifer Anderson, building the brand appears to be as much about preserving craftsmanship as expanding a fashion business. Their story reflects a broader movement toward intentional consumption and objects that carry meaning beyond their purchase price.

In a culture constantly asking what’s next, Uptown Common is asking a different question:

What is worth keeping?

For this growing American leather brand, that may be the most modern definition of luxury of all.

Website: uptowncommonhandmade.com
Instagram: @uptowncommon

September Flash PMI Hits Five-Year High as Input Cost Inflation Reaches Highest Level Since 2022

U.S. business activity grew at its fastest pace in more than five years in September. The S&P Global Flash US Composite PMI rose to 58.4 from 56.0 in August. Input costs rose at the fastest rate since October 2022, driven by fuel and transport expenses, adding to inflation pressure the Federal Reserve is already trying to contain.

Key Takeaways

  • The Flash US Composite PMI Output Index reached 58.4 in September, a 62-month high and the fourth consecutive month of faster growth.
  • The Flash US Manufacturing PMI jumped to 57.0 from 53.9, the strongest improvement in factory conditions since May 2022.
  • The Services Business Activity Index rose to 58.7 from 56.5, a 59-month high.
  • Employment rose at the fastest rate since June 2022, and manufacturing payrolls grew at the fastest pace since February 2021.
  • Backlogs of uncompleted orders rose at the sharpest rate since May 2022, and supplier delays were the most widespread since July 2022.
  • Final September manufacturing data will be published October 1, with services and composite data following on October 5.

The Headline Numbers Show Broad-Based Acceleration

The September flash PMI showed gains in both major sectors. The S&P Global Flash US Composite PMI Output Index, a weighted average of manufacturing output and services activity, rose 2.4 points to 58.4. Readings above 50 indicate expansion. September’s level marks the fastest growth since July 2021.

Services led the increase. The Services Business Activity Index climbed to 58.7 from 56.5, the steepest rise in output in more than five years. Manufacturing also recovered. The Manufacturing Output Index rose to 56.7 from 53.1, its fastest reading since April 2022, after three months of slowing production growth.

The headline Manufacturing PMI, which combines new orders, output, employment, supplier delivery times, and inventories, rose to 57.0 from 53.9. S&P Global said all five components contributed to the gain. New orders in manufacturing grew at the fastest pace in nearly four and a half years.

Chris Williamson, Chief Business Economist at S&P Global Market Intelligence, said the data point to annualized economic growth of around 5% and a 4% gain for the third quarter overall. Excluding the post-lockdown rebound, he said the improvement in business activity is the largest recorded since early 2015. “Business is clearly booming now in both manufacturing and services,” Williamson said.

Domestic Demand Is Driving the Growth

The composition of demand matters for business owners reading the September PMI. New order growth reached its highest level since March 2022 in services and since April 2022 in manufacturing. S&P Global said the growth came mainly from the domestic market. Goods export volumes continued to fall, and services exports rose only modestly.

That pattern suggests U.S. growth is being driven by domestic spending, not overseas demand. Businesses selling to U.S. customers are seeing stronger order books. Exporters face a weaker picture, and a stronger dollar in recent sessions could add to that pressure.

Capacity Constraints Are Starting to Show

The September PMI also points to strain on operating capacity. Backlogs of uncompleted orders, which S&P Global treats as a key measure of capacity use, rose at the sharpest rate since May 2022, with increases in both manufacturing and services.

Companies responded by hiring. Employment rose at a pace rarely exceeded since comparable data began in 2009. Service sector payrolls grew at the fastest rate since June 2022, and factory employment rose the most since February 2021. Even so, companies reported growing difficulty finding suitable staff.

Supply chains added to the pressure. Suppliers’ delivery times lengthened sharply again, with delays the most widespread since July 2022. Williamson said the bottlenecks are among the most severe in the survey’s nearly 20-year history outside the pandemic period.

For small and midsize businesses, that combination creates operating risk. Strong demand paired with slower supplier deliveries and a tight labor pool can delay fulfillment, strain customer relationships, and push up overtime costs. Rising backlogs point to revenue ahead but also to delivery commitments that may be harder to meet.

Input Costs Are Rising Faster Than Selling Prices

The price data are the most important part of the September report for inflation. Average input costs across goods and services rose at the fastest rate since October 2022. Respondents mainly cited higher fuel and transport costs, and many also reported rising wage pressure.

Service sector input cost inflation reached its highest level since November 2022. In manufacturing, high raw material prices were often linked to supply shortages, although factory input inflation remained below peaks seen earlier this year during the energy price spike.

Selling prices rose more slowly. Output price inflation picked up from August but stayed below the rates recorded from March through July, and competition held back price increases in services. When costs rise faster than selling prices, margins shrink.

Williamson said growing backlogs indicate companies are gaining pricing power, which he described as a concern for the inflation outlook. That suggests the gap between costs and prices may narrow in the coming months as businesses pass through more of their cost increases.

Markets Read the PMI as Pressure on the Fed

Financial markets reacted quickly. Treasury yields rose after the PMI release, and the 10-year Treasury yield reached 5.135%, its highest level since July 2007. Major stock indexes closed lower on September 23.

The report comes a week after the Federal Open Market Committee voted 12–0 on September 16 to raise the federal funds target range by a quarter point to 3.75%–4.00%, its first increase since 2023. The FOMC statement said inflation remains elevated. The committee’s projections showed 16 of 18 participants expecting another increase this year. The next FOMC decision is scheduled for October 28.

For businesses with variable-rate credit lines or loans tied to the prime rate, the September PMI supports the case for higher borrowing costs. Strong growth and accelerating input costs give the Fed little reason to pause.

Service Sector Confidence Lags Behind Activity

Despite the strong activity readings, expectations for the year ahead were unchanged in September. Manufacturers were more optimistic than service providers, and factory confidence is near its long-run average.

Service sector sentiment remained well below trend. Respondents cited cost-of-living pressures, higher borrowing costs, and political uncertainty. The gap between strong current activity and weak service sector confidence suggests many operators see the current growth as fragile.

The Flash Reading Comes With Caveats

The flash PMI is based on about 80% to 90% of total survey responses, collected September 10–22, 2026, from panels of about 650 manufacturers and 500 service providers. Historically, the average absolute difference between flash and final readings has been 0.4 points for the composite and services indexes and 0.3 points for manufacturing.

PMI surveys measure the breadth of change, not its size. A reading of 58.4 means more businesses reported growth than decline. It does not directly measure output. Official data on gross domestic product, inflation, and employment will show whether September’s survey results hold up.


Disclaimer: This article is for informational purposes only and does not constitute financial, investment, business, economic, or tax advice. The PMI data discussed are survey-based indicators and do not directly measure overall economic output or guarantee future economic conditions. Readers should consider additional official economic data and consult a qualified financial or tax professional before making decisions based on economic or financial information.


FAQs

What was the September 2026 flash PMI reading?

The S&P Global Flash US Composite PMI Output Index rose to 58.4 in September 2026 from 56.0 in August. It was the fastest private-sector expansion since July 2021.

What does a PMI above 50 mean?

A reading above 50 means more surveyed businesses reported improvement than decline compared with the previous month. A reading below 50 indicates contraction.

Why are business input costs rising?

Survey respondents mainly cited higher fuel and transport costs, along with rising wages. Input cost inflation across goods and services reached its highest level since October 2022.

How does the PMI affect Federal Reserve policy?

Strong growth combined with rising input costs signals inflation pressure, which supports further rate increases. The Fed raised rates on September 16, and its next decision is scheduled for October 28.

When will final September PMI data be released?

Final manufacturing PMI data will be published October 1, 2026. Final services and composite data follow on October 5.

How Professional Ghostwriting Services Help Turn Ideas Into Books

Many people have a book idea but never get the opportunity to turn that idea into a complete manuscript. Work commitments, limited writing experience, or simply not knowing where to begin can make the process difficult. Professional ghostwriting services can help authors move from an early concept to a structured and readable book.

Ghostwriting is used for many types of projects, including memoirs, biographies, novels, business books, self help books, and other forms of nonfiction. The process allows authors to share their ideas and vision while a professional writer helps develop those ideas into a complete manuscript.

What Is Ghostwriting?

Ghostwriting is a professional writing arrangement in which a writer creates content based on another person’s ideas, experiences, knowledge, or instructions. The author provides the direction and subject matter, while the ghostwriter handles much of the writing work.

The level of involvement can vary from project to project. Some authors have detailed outlines and need help developing the chapters, while others have only a basic concept and require assistance with planning and writing the entire manuscript.

Professional ghostwriting services can help organize this process and provide writing support based on the author’s specific project.

Turning an Idea Into a Structured Book

A book idea can start as a few notes, personal experiences, conversations, or a simple concept. Turning those ideas into a complete book requires structure.

A professional ghostwriter can help develop the central concept, organize chapters, establish the flow of information, and determine how different ideas should be presented. For fiction, the process may involve character development, plot structure, dialogue, and pacing. For nonfiction, it may focus on research, organization, explanations, and the author’s expertise.

A clear structure gives the manuscript direction and makes it easier for readers to follow the content.

Preserving the Author’s Voice

One of the most important aspects of ghostwriting is maintaining the author’s perspective. A book should reflect the author’s ideas, experiences, and intended message rather than simply sounding like the writer.

Before writing begins, authors and ghostwriters may discuss the project’s purpose, target audience, tone, writing style, and key ideas. Interviews, notes, recordings, outlines, and other source material can also help the writer understand the author’s voice.

Regular communication throughout the project can help keep the manuscript aligned with the author’s original vision.

Ghostwriting Can Save Authors Time

Writing a complete book requires a significant investment of time. Authors who have demanding professional or personal responsibilities may find it difficult to dedicate enough hours to writing every chapter.

Working with a professional writer can allow authors to focus on their expertise and ideas while receiving support with the actual manuscript development.

This can be especially useful for professionals, entrepreneurs, public speakers, and individuals who have valuable experiences to share but limited time to write.

Different Types of Books Can Benefit From Ghostwriting

Ghostwriting is not limited to one particular genre. Professional writers may work on a wide range of projects depending on their experience and the author’s requirements.

Memoirs and autobiographies can benefit from interviews and structured storytelling, while fiction projects may require extensive work on characters and plot development. Business and self help books may focus on presenting the author’s knowledge in a clear and accessible format.

Authors can also explore specialized book writing services when they need broader assistance developing their manuscript.

Editing Comes After the Writing

Completing a manuscript is an important milestone, but the writing process does not necessarily end with the first draft. Editing can help improve the structure, clarity, grammar, consistency, and overall readability of the book.

Professional book editing services can provide another level of review before the manuscript moves toward publication. An editor can identify areas that may need clarification or improvement while helping preserve the author’s intended message.

Moving From Manuscript to Publication

After the manuscript has been written and edited, authors can begin preparing the book for publication. This may involve formatting, cover design, publishing, distribution, and marketing.

Professional book publishing services can help authors navigate the publishing stage and prepare their work for readers.

Having a clear plan for each stage can make the overall process easier to manage and reduce confusion for first time authors.

Final Thoughts

A great book can begin with nothing more than an idea, a personal experience, or knowledge that an author wants to share. The challenge is turning that starting point into a complete manuscript that readers can understand and enjoy.

Professional ghostwriting services can provide the writing expertise and structure needed to develop an idea into a finished book while keeping the author’s vision at the center of the project. With additional support from editing and publishing services, authors can move through the process from initial concept to publication in a more organized way.

Built to Perform and How Abdul Foster Has Spent His Career Studying What Makes Growth Work

From performance training to sports technology and business development, the Berry Dynamic Agency executive has repeatedly returned to the same question: What has to change when good work is ready to become something bigger?

Abdul Foster has spent much of his professional life around performance, first in a literal sense and later in business. His career has crossed fitness, entrepreneurship, technology and business development, but beneath those shifts is a consistent interest in systems: how people work, how customers move through an experience and what must happen behind the scenes for something successful to continue growing.

That perspective now defines much of Foster’s role as Executive Director of Berry Dynamic Agency, where he leads work connected to business development, strategy, client experience and growth. His addition to the agency’s leadership team helped expand Berry Dynamic beyond its communications foundation and into a broader examination of what prevents otherwise capable businesses from moving forward.

Foster did not arrive at that work through a traditional consulting path. His entrepreneurial background developed through the fitness and performance world, where results are difficult to separate from execution. Training programs must work in practice, not simply on paper. Customers need a clear way to schedule, pay, and communicate. Professionals need systems that allow them to spend less time managing administrative work and more time delivering the service people hired them to provide.

Those experiences eventually contributed to Foster founding Trainr., a Houston-based sports technology company built around tools for coaches and trainers. The platform has addressed functions including scheduling, billing, booking, payments, messaging, and workout creation, essentially bringing together tasks that independent fitness professionals often manage through multiple disconnected tools.

Trainr. also placed Foster more directly inside Houston’s technology and startup community. The company participated in DivInc’s 2024 Sports Tech Accelerator cohort, where founders worked within a broader environment focused on sports innovation and scalable technology businesses. The experience reflects Foster’s movement from delivering services himself to thinking about how technology can help an entire category of professionals operate differently.

That transition is important to understanding his work at Berry Dynamic. Foster knows what it feels like to move from practitioner to business owner and from business owner to builder of a system other people are expected to use. Each stage requires a different way of thinking.

Many entrepreneurs eventually encounter the same tension. The habits that helped them reach their first level of success are not always the habits that will support the next one. A founder can personally answer every client call when there are ten customers. That becomes harder at 100. A service can depend heavily on the founder’s personal skill when it is small, but growth eventually requires documented processes, clearer offers, better customer pathways and decisions about what should be automated, delegated or redesigned.

Foster’s work at Berry Dynamic is concerned with that transition.

The agency’s Business Scalability pathway focuses on barriers such as business development, customer pathways, market positioning, websites, product launches and systems needed to support growth. Berry Dynamic’s Business Scalability Index takes the idea further by examining the leadership, operations, and growth barriers that may be keeping an organization from expanding effectively.

Foster’s approach is particularly useful for businesses that have already proven they can attract customers but cannot understand why growth continues to feel harder than it should. Sometimes the problem is not demand. It is the amount of friction hidden inside the business.

A customer may have difficulty understanding what to purchase. The website may send visitors in too many directions. The founder may be personally responsible for tasks someone else could own. Services may have been added over time without anyone stopping to examine whether they still fit together. Sales may increase while profit does not. More opportunities may actually create more chaos.

Those are growth problems, but they are not solved simply by telling a company to work harder.

Foster’s background in performance makes that distinction particularly fitting. In athletics, improvement rarely comes from repeating the same movement with greater intensity forever. Performance requires evaluating what is working, correcting what is not and building systems that make better execution repeatable. His business philosophy follows a similar pattern.

Within Berry Dynamic’s executive team, Foster occupies the space between preparation and recognition. COO Dr. Xanthea Moore focuses heavily on financial readiness, structure and operational discipline. Founder Ciara Suesberry-Roberts leads communications, public relations and authority positioning. Foster’s work asks whether the business itself can move effectively between those two points. Once an organization is prepared and demand begins to increase, can its systems actually support the growth?

The three areas overlap deliberately. A publicity campaign can expose a weak customer journey. A major funding opportunity can strain inadequate operations. A new website cannot compensate for an offer that no longer makes sense. Foster’s role is not simply to help businesses become larger but to examine what must become clearer or stronger before growth creates a new set of problems.

That is one reason Berry Dynamic’s current direction fits his experience. The agency’s refreshed model begins with identifying the gap rather than prescribing the same solution to every company. For some businesses, the answer will be communications. For others, capital readiness. For another, the most valuable work may happen quietly inside its processes long before anyone sees a new advertisement or press feature.

Foster’s career has moved from improving individual performance to building tools for other professionals and now helping businesses examine their own capacity for growth. The industries have changed, but the central question has remained remarkably consistent.

What does better performance actually require?

For Foster, the answer is rarely more noise. It is usually a better system.

Rising Borrowing Costs Create a Two-Speed Economy as Mortgage Rates Top 7% and Consumer Credit Card Debt Reaches $1.26 Trillion

The Federal Reserve’s September 16 rate hike to 3.75%–4% has widened a growing split in the U.S. economy, where consumer spending on retail and dining remains resilient while rate-sensitive sectors including housing, auto lending, and small business financing are deteriorating under borrowing costs not seen in more than two decades.

Key Takeaways

  • The 30-year fixed-rate mortgage reached 7.19% following the Fed’s September 16 rate hike, up 38 basis points since Fed Chair Kevin Warsh’s August 28 Jackson Hole speech and more than a full percentage point from a year earlier.
  • The 10-year Treasury yield crossed 5% on September 14 for the first time since 2023, directly pushing up mortgage rates, auto loan pricing, and small business borrowing costs.
  • U.S. credit card balances reached $1.26 trillion in Q2 2026, a new record for the eleventh consecutive quarter, with the average APR for cards accruing interest rising to 22.15%.
  • The NAHB Housing Market Index fell to 32 in September, while August retail sales rose 1.2% month-over-month, beating consensus by 30 basis points, illustrating the divergence between rate-sensitive and consumer-facing sectors.
  • There is typically a six-month lag between a housing slowdown and decreased spending on consumer durables, meaning the full impact of current mortgage rates may not reach furniture, appliance, and flooring retailers until early 2027.

The Fed’s First Rate Hike Since 2023 Pushed Short-Term Borrowing Costs Higher Across the Board

The FOMC voted 12-0 on September 16 to raise the federal funds rate by 25 basis points to a target range of 3.75%–4%, the first increase since the committee was still cutting rates in late 2023. Fed Chair Kevin Warsh, who took over from Jerome Powell earlier in 2026, described inflation as “elevated” in his post-meeting press conference and noted that economic activity continues to expand at a solid pace. The September dot plot projects a year-end rate between 4.1% and 4.4%, and futures markets are pricing in another quarter-point hike by December with rates potentially reaching 4.7% by September 2027.

The rate hike arrived in an environment where longer-term Treasury yields had already been climbing for weeks. The 10-year Treasury yield crossed 5% on September 14, reaching levels not seen since 2023. The 20-year yield hit 5.39%. The 2-year yield, which is the most sensitive to rate expectations, closed at 4.745% on September 16, up approximately 10 basis points on the day. Those moves did not occur in isolation. They reflected a convergence of factors: persistent inflation readings, geopolitical risk from the Middle East conflict driving energy costs higher, and the relentless demand for capital to fund artificial intelligence infrastructure buildouts, all competing for bond market financing simultaneously.

Mortgage Rates at 7.19% Have Pushed Homebuilder Confidence to Multi-Year Lows

The 30-year fixed-rate mortgage rose to 7.19% in the wake of the rate decision, a figure that carries weight across the economy far beyond the housing sector itself. The rate is up approximately 38 basis points since Warsh’s hawkish Jackson Hole speech on August 28, and more than a full percentage point above where it stood a year ago. The NAHB/Wells Fargo Housing Market Index dropped three points to 32 in September. NAHB Chairman Bill Owens cited weakened buyer traffic driven directly by rising mortgage rates, alongside higher material costs, rising gas and diesel prices, and persistent labor shortages as compounding factors.

Mortgage originations had already slowed to $530 billion in Q1 2026, per the New York Fed’s Household Debt and Credit Report, and Mortgage Bankers Association data shows applications continuing to decline. The housing slowdown carries a delayed economic effect that extends well beyond the transaction itself. Research consistently shows a roughly six-month lag between declining home sales and reduced spending on big-ticket household goods, including furniture, appliances, carpeting, and home renovation materials. That means the current mortgage rate environment, which has been elevated since late August, may not fully register in consumer durables data until the first quarter of 2027.

Consumer Credit Card Debt Hit $1.26 Trillion While APRs Climbed Past 22%

While the housing market contracts under the weight of higher rates, consumer credit tells a different story about how Americans are financing their daily lives. Total U.S. credit card balances reached $1.26 trillion in Q2 2026, per the New York Fed, marking a new record for the eleventh consecutive quarter and representing a 4.5% increase from a year earlier. The figure has nearly doubled from the $770 billion trough recorded in Q1 2021. Total consumer credit outstanding, which includes credit cards, auto loans, student loans, and other non-mortgage debt, reached $5.17 trillion as of June 2026, a figure that has more than tripled since 2000.

The cost of carrying that debt has increased sharply. The Federal Reserve’s G.19 consumer credit report showed the average APR for credit cards accruing interest rose to 22.15% in Q2 2026, up from 21.52% in Q1. For new credit card offers, the average APR stands at 23.82%. The stock of credit card balances that are more than 90 days delinquent rose from 7.6% in Q3 2022 to 12.8% by Q1 2026, according to the New York Fed’s analysis, though the institution noted that the rising stock rate is partly a compositional effect driven by a slower resolution of previously delinquent accounts rather than a surge in new defaults. The 30-day delinquency rate actually dipped to 2.85% in Q2 2026, the eighth straight quarterly decrease. The aggregate delinquency rate across all consumer debt stood at 4.7% in Q2 2026.

Retail Spending Remains Strong, Masking Weakness in Rate-Sensitive Sectors

The paradox at the center of the two-speed economy is that consumers are still spending at a pace that surprised economists as recently as mid-September. Advance retail sales for August 2026 came in at $773.9 billion, up 1.2% month-over-month and 6.0% year-over-year, well above the 0.9% consensus estimate. Control-group retail sales, the component that feeds directly into GDP calculations, jumped 1.4% after a 0.4% decline in July. Gains were broad-based across gasoline, online retail, and restaurants. The Atlanta Fed subsequently raised its third-quarter GDP growth estimate on the strength of the report.

That resilience has been partially financed by the tax reform effects of the 2025 Big Beautiful Bill. Americans saw approximately an 11% increase in average tax refunds during the first half of 2026, and the Brookings Institution’s Fiscal Impact Measure estimates that the income boost from lower taxes contributed 0.4 percentage points to GDP in the first half of the year. That tailwind, however, is fading as the refund cycle completes, removing a meaningful cushion from both consumer spending and small business cash flow heading into Q4.

Small Businesses Face Financing Costs That Have Not Been This High in Years

For small business owners and founders, the rate environment translates into tangibly higher costs on every form of borrowing that depends on longer-term Treasury yields: SBA loans, commercial real estate financing, equipment leases, and lines of credit. The NFIB Small Business Optimism Index dipped to 98.7 in August 2026 while the Uncertainty Index remained at 89, a full 21 points above its historical average of 68. NFIB Chief Economist Bill Dunkelberg cited weakened sales, supply chain disruptions, and inflation pressures as the primary concerns, with over 20% of small businesses continuing to report that finding qualified labor remains their single biggest problem.

The structural challenge for small businesses is that the Fed’s rate hike mechanism does not distinguish between the parts of the economy that are running warm and the parts that are already cooling. Rate increases apply uniformly, making borrowing more expensive across the board. The sectors that are driving economic strength, particularly AI-related capital expenditure and energy infrastructure, are largely financed by large corporations with access to capital markets. Small businesses relying on bank lending and SBA-backed products absorb the same rate increases without the same ability to pass costs through to customers. That asymmetry is what defines the two-speed economy: the same monetary policy that aims to cool inflation in aggregate is tightening conditions unevenly, squeezing the businesses and households that are most dependent on borrowed capital while barely slowing the sectors that have the cash reserves to absorb higher rates without changing behavior.

Auto loan balances rose to $1.69 trillion in Q1 2026, per the New York Fed, and TransUnion projects 60-plus-day auto loan delinquencies reaching 1.54% by year-end, marking the fifth straight year of increases in that category. The New York Fed’s Joelle Scally noted that “new delinquencies for auto loans and credit cards remain at elevated levels.” For entrepreneurs and small business owners who also carry personal auto loans and credit card balances, the compounding effect of higher rates across every form of debt simultaneously creates a personal financial environment that constrains risk-taking, hiring, and capital investment at precisely the moment the macroeconomic headlines suggest the economy is holding up well.

FAQs

What Is The Current 30-Year Mortgage Rate?

The 30-year fixed-rate mortgage reached 7.19% following the Federal Reserve’s September 16, 2026, rate hike. The rate is up approximately 38 basis points since Fed Chair Kevin Warsh’s August 28 Jackson Hole speech and more than a full percentage point from a year earlier.

How Much Credit Card Debt Do Americans Carry?

U.S. credit card balances reached $1.26 trillion in Q2 2026, per the New York Fed, a new record for the eleventh consecutive quarter. The average APR for cards accruing interest stands at 22.15%, while new card offers average 23.82%.

Why Did The Federal Reserve Raise Interest Rates In September 2026?

The FOMC voted 12-0 to raise the federal funds rate by 25 basis points to 3.75%–4% on September 16, citing elevated inflation and solid economic activity. Fed Chair Kevin Warsh indicated that inflation remains above the committee’s target and that economic indicators across productivity, investment, and domestic spending remain strong.

How Are Rising Rates Affecting Small Businesses?

Higher longer-term Treasury yields translate directly into higher financing costs on SBA loans, commercial real estate, equipment leases, and lines of credit. The NFIB Small Business Optimism Index dipped to 98.7 in August 2026, with the Uncertainty Index at 89, well above its historical average of 68.

When Will The Housing Slowdown Affect Consumer Spending On Furniture And Appliances?

Research shows a roughly six-month lag between declining home sales and reduced spending on big-ticket household goods. The current mortgage rate environment, elevated since late August 2026, may not fully impact consumer durables spending until early 2027.

The L-1A Visa Is the Bridge in Most Company Expansion Plans

A growing company decides the US market can no longer be served from abroad. The board approves an American entity, and two questions land on the same desk: who runs it, and on what status does that person enter the country? The second question’s most established answer is the L-1A.

The corporate relationship works in both directions

L-1A transfers executives and managers from a foreign company to its related US company, and the qualifying relationship is the file’s foundation. The direction is flexible: the foreign company may be the parent, or the US company may be. What must be documented is the link between the two entities.

The role standard is demanding but not narrow: meeting either the executive or the managerial definition suffices. And a detail that matters to family businesses everywhere: the transferred manager may be the company’s owner, or a non-owner with genuine management authority.

New office cases are their own discipline

A freshly formed US entity does not close the route; it changes the file type. The strategy decisions come in a chain: L-1A or L-1B, standard or New Office filing, change of status or consular processing, which corporate documents, and whether to coordinate with a future EB-1C green card case from the start.

The evidence bar shows in the Requests for Evidence this category generates: insufficient proof of the corporate relationship, vague role descriptions, doubts about whether a small US company can support a genuinely managerial role, and, in new office cases, thin evidence of premises, capital, or a viable business plan. The response clock is regulatory: up to 84 days.

Process and price, without surprises

A filed petition ends one of three ways: approval, a Request for Evidence, or denial. The applicant’s location picks the track. Someone already in the US in another status can switch to L-1 without leaving, documented by the approval notice; someone abroad completes the online application after petition approval and interviews at the US consulate in their home country.

The fee stack varies with company profile: an asylum program fee of $600, $300, or zero; the $500 fraud prevention fee; $2,965 for premium processing where used; and dependant applications at $470 on paper or $420 online. On the family side, children in L-2 status attend public or private school.

Renewals re-test the business, not just the person: ongoing corporate relationship, a current role and organization chart, financial statements showing an operating company, and proof the original conditions still hold. A first year of disciplined record-keeping is, in practice, the second year’s renewal file. A denial leaves options: refiling with stronger evidence, motions to reopen or reconsider, or an alternative category.

The real prize sits one filing later

Transfer speed is the visible benefit. The strategic one is the door L-1A opens: green card routes for L-1 holders include employer-sponsored labor certification and, for qualifying profiles, the extraordinary-ability category. For executives specifically, the EB-1C multinational manager category mirrors the L-1A fact pattern almost exactly: a year of managerial service abroad within the preceding three, continuing in a managerial role at the related US company.

A well-built L-1A file is usually the first of two filings, which is why an L-1A visa lawyer plans the transfer and the permanence question together. Grape Law’s L-1A guide covers the corporate relationship tests, new office requirements, and the process stage by stage; Grape Law’s expansion clients hear the strategy question in the first meeting: where does this transfer sit in the permanent structure?

Companies that answer that early buy their executive one process instead of two.

Fees cited were verified against the USCIS fee schedule as of August 19, 2026. This article is for general information only and is not legal advice. Every immigration case turns on its own facts. Consult an immigration attorney about your specific situation.

Disclaimer: This article is for general informational purposes only and does not constitute legal advice. Immigration requirements, fees, processing times, and visa availability may change. Every case depends on its specific facts and circumstances. Consult a qualified immigration attorney regarding your situation.