Market Daily

Funding Options for Accounting Firms, Managing Seasonal Cash Flow

Business owners working in accounting firms face funding challenges that are easy to overlook in a generic conversation about small business lending, but that become obvious the moment you look closely at how this specific type of business actually generates revenue and incurs costs. Understanding those specific patterns, rather than applying a one-size-fits-all approach to funding, is the first step toward choosing a financing structure that actually fits. Fundivi’s business loans online for accounting firms are built with exactly this kind of specificity in mind.

Why This Challenge Is Different

Accounting firms face one of the most pronounced seasonal revenue patterns of any professional service business, with tax season driving a disproportionate share of annual billing into a concentrated window of just a few months. This creates a real planning challenge: staffing needs often peak well before the revenue from that busy season has been fully collected, and firms frequently need to invest in additional seasonal staff, software licensing, or office capacity well ahead of the client work that will eventually justify that spending.

A Second Layer To The Same Problem

Outside of tax season, many firms also face a slower, more variable revenue period where advisory and bookkeeping work continues but at a steadier, less predictable pace. Firms that have built their staffing and overhead around peak-season revenue sometimes find this slower period puts real pressure on cash flow, particularly if a firm is also investing in growth, such as adding a new service line or expanding into a new client segment, during what would otherwise be a quieter stretch of the year.

How Fundivi Approaches This Need

Fundivi’s underwriting evaluates real, current business performance rather than relying solely on years of operating history or extensive collateral, which makes it particularly well suited to businesses whose funding needs are tied to a specific, identifiable pattern rather than a generic, open-ended request for capital. Reviewing Fundivi’s working capital loan options gives a clearer sense of how this specific type of funding is structured and what it is actually designed to address.

The application itself is built to move quickly, typically taking only a few minutes to complete, with a secure connection to your business’s bank account or financial data replacing the extensive paperwork a traditional bank loan would require. Because the underwriting engine evaluates real, verified data directly, a funding decision can often be reached within hours rather than the weeks a conventional loan process might require, which matters considerably for a business facing a need tied to a specific, time-sensitive pattern rather than a flexible, open-ended timeline.

Choosing The Right Structure For Your Specific Situation

Not every funding need calls for the same structure, and it is worth taking a moment to confirm that the product you are considering actually matches your situation before applying. Reviewing how to qualify for business loans online can help clarify the specific qualification criteria and underwriting approach involved, so you know what to expect and what to prepare before starting an application.

Business owners who are still weighing this specific product against a broader set of options can also review Fundivi’s business loan tools, which provide useful context for comparing structures side by side rather than committing to the first product that comes to mind. Taking this extra step before applying tends to produce a better match between the funding structure chosen and the actual underlying need driving the application in the first place.

Planning Rather Than Reacting

Business owners who recognize the specific funding pattern tied to their type of business, and who plan for it proactively rather than only seeking capital once a cash flow problem has already become urgent, consistently end up with more favorable terms and a wider range of options than those applying reactively. This is particularly true for funding needs tied to a predictable pattern, such as a seasonal cycle or a recurring timing gap, since a lender can evaluate a well-documented, foreseeable pattern more favorably than an unexplained, last-minute request.

Building a habit of reviewing your business’s specific cash flow pattern periodically, rather than only thinking about funding when a specific need has already become pressing, puts you in a stronger position every time a genuine funding decision does arise. Many business owners find it useful to identify, in advance, which funding structure they would turn to for each of their business’s recurring patterns, so that when the moment actually arrives, the decision has already been made and only the application itself remains.

What Lenders Actually Look For In This Situation

When a lender evaluates a funding request tied to the specific pattern described above, the strongest applications tend to share a few common qualities. Clear, verifiable revenue and cash flow data, reviewed directly through connected bank account information rather than self-reported figures, gives an underwriting engine the clearest possible picture of a business’s actual current performance. A specific, well-documented explanation of how the funding will be used, rather than a vague general purpose, also tends to move an application through underwriting more smoothly, since it allows the lender to evaluate the request against its actual intended use rather than guessing at the underlying need.

Business owners in accounting firms who come to the application process with this kind of clarity, having already identified the specific pattern driving their need and gathered the documentation that supports it, consistently experience a faster and more straightforward path from application to funding than those applying with only a general sense that more capital would help. This preparation costs relatively little time upfront but can meaningfully shorten the overall process and improve the quality of the terms ultimately offered, which matters just as much for a smaller, routine funding need as it does for a larger, more consequential one.

Avoiding Common Missteps

One common misstep is waiting too long to address a funding need that was, in retrospect, entirely predictable. Business owners who recognize a recurring pattern in their operations, whether tied to seasonality, a specific client payment cycle, or a recurring equipment or staffing need, but who nonetheless wait until the pressure becomes acute before seeking funding, generally end up with fewer options and less favorable terms than those who plan ahead. Recognizing a pattern once is useful; building a standing plan around it is considerably more valuable over the long run.

A second common misstep is choosing a funding structure based on availability or familiarity rather than genuine fit. A business owner who has used one particular type of funding before may default to it again out of habit, even when a different structure would actually serve the current need better. Taking a few extra minutes to confirm that a given product’s structure, repayment schedule, and underwriting approach genuinely match the situation at hand, rather than assuming the familiar option is automatically the right one, tends to produce better outcomes meaningfully over time, both in terms of total cost and in how comfortably the resulting payments fit alongside the business’s other ongoing obligations.

Getting Started

If the specific challenge described here matches what your business is currently experiencing, the most direct next step is to review the specific product details linked throughout this article and begin an application when you are ready. Because the process is designed to move quickly, starting the application costs little time even while you continue to confirm that this is the right structure for your situation, and a real funding decision based on your business’s actual numbers will give you far more clarity than continued research alone.

Frequently Asked Questions

How Is This Type Of Funding Specifically Evaluated During Underwriting?

Underwriting generally focuses on your business’s current revenue and cash flow performance, along with any specific documentation relevant to the particular funding need described above.

How Quickly Can Funding Be Delivered Once An Application Is Submitted?

Because the underwriting process relies on real, verified data rather than extensive manual document review, decisions can often be reached within hours, with funding following shortly after an offer is accepted.

Does This Type Of Business Need A Long Operating History To Qualify?

Qualification depends primarily on the strength and consistency of current revenue rather than years in operation, so newer businesses with strong performance can often still qualify.

What Happens If My Specific Situation Changes After I Apply?

Business owners should communicate any significant change in circumstances to their lender promptly, since this may affect the specific terms or structure of an active application.

Where Can I Compare This Option Against Other Funding Structures?

Reviewing Fundivi’s broader range of funding products alongside the specific option discussed here can help confirm which structure actually fits your business’s situation before you commit to an application.

Disclaimer: This article is for general informational and educational purposes only and should not be considered financial, legal, accounting, or professional advice. Funding products, eligibility requirements, approval timelines, interest rates, fees, repayment terms, and availability may vary based on the lender, applicant, business performance, credit profile, and other underwriting factors. References to potential approval or funding timelines are illustrative and do not constitute a guarantee of approval, funding, or specific terms. Business owners should carefully review all applicable terms and consult with a qualified financial, legal, or accounting professional before entering into any financing arrangement.
Paul Davis Restoration of Brooklyn West Manages Every Detail So Clients Don’t Have To

Coordinating separate vendors for mitigation, documentation, and insurance paperwork is one of the more genuinely exhausting parts of dealing with property damage in a busy city. Paul Davis Restoration of Brooklyn West, led by Felipe Jimenez de Lucio Perez, says removing that coordination burden entirely is central to how the company operates.

A Hands-On, Accountable Approach

Jimenez de Lucio Perez describes the company’s process directly. “We manage the entire restoration process with a hands-on, accountable approach,” he said, covering everything from emergency response and documentation to estimating, insurance coordination, and reconstruction, all handled internally rather than farmed out to separate specialists for each phase. That structure is meant to spare clients the burden of managing the process themselves. “Clients don’t have to coordinate multiple vendors or manage insurance paperwork themselves,” he said. In Dumbo, one of the company’s target neighborhoods, that hands-on structure applies to older buildings and newer developments alike, regardless of how much water, fire, or mold damage a given unit sustained.

A Reputation on the Line With Every Job

Jimenez de Lucio Perez frames the company’s motivation in genuinely personal terms. “We treat every project like it reflects directly on our name, because it does,” he said, describing a standard that applies whether a project is a small residential repair or a larger multifamily loss.

Equipped for Residential Through Larger Commercial Losses

The company says it’s equipped to handle residential, multifamily, and larger commercial losses under the same standard of documentation and compliance, following established insurance carrier requirements to keep a claim moving efficiently regardless of scale or complexity. That range means a co-op board or building manager overseeing a larger loss works with the same accountable process a single homeowner would experience, without needing to bring in a second company once a project grows beyond a single unit.

That consistency matters in a borough where a single water or fire event can affect one apartment or an entire building at once. Whether the job involves a single brownstone unit, a multifamily walkup, or a larger commercial space, the company applies the same documentation standards and insurance-carrier requirements throughout, so a building manager coordinating a larger claim isn’t navigating a different process than an individual homeowner down the block.

What Brooklyn West Clients Are Saying

Recent client feedback continues to highlight thoroughness even before a project formally begins. Marshall S. described a walkthrough for a possible job, saying the team brought various testing equipment and experts along to help him make an informed decision, calling the visit genuinely helpful and confirming he’d reach out again once he was ready to move forward.

How does Paul Davis Restoration of Brooklyn West reduce the burden on clients?

The company manages the entire process, including emergency response, documentation, estimating, and insurance coordination, so clients don’t have to coordinate multiple vendors themselves during an already stressful time.

Does the company treat insurance and self-pay projects differently?

No. The same structured process and transparency apply whether a project involves an insurance claim or a self-pay arrangement, with no difference in the level of documentation or care provided.

What does the company mean by treating every project as a reflection of its name?

The team says it holds every project, regardless of size, to the same standard, since each one directly affects the company’s reputation in the neighborhoods it serves.

What areas does Paul Davis Restoration of Brooklyn West serve?

The franchise serves Park Slope, Dumbo, Brooklyn Heights, Carroll Gardens, Bay Ridge, Cobble Hill, and surrounding neighborhoods throughout western Brooklyn, an area known for its distinctive mix of pre-war brownstones and newer residential development.

Stay Connected With Paul Davis Restoration of Brooklyn West

For project updates and local news, homeowners can follow Paul Davis Restoration of Brooklyn West on Facebook and LinkedIn for the latest updates.

Paul Davis Restoration of Portland/Vancouver Runs Two Daily Shifts to Keep Certified Staff Available Around the Clock

By: Abigail Hayes

A restoration emergency doesn’t wait for regular business hours, and Paul Davis Restoration of Portland/Vancouver has structured its staffing specifically around that reality, running two shifts a day so certified specialists are always available rather than being called in after the fact once a homeowner has already been waiting.

Certified Staff, Available Around the Clock

The company describes its staffing model directly, framing round-the-clock availability as a baseline expectation rather than an upgrade reserved for larger commercial accounts. “IICRC certified specialists and project managers respond 24/7,” the team said. That availability is built into the schedule itself. “We also run two shifts per day and have people on duty 7 days per week,” the company said, describing a structure meant to avoid the delay that comes from waiting for an on-call technician to be reached and dispatched after hours, whether the call comes in during a weekday afternoon or in the middle of the night. In Hillsboro, one of the communities across the Portland metro area, that staffing model applies the same way whether a call comes in at noon or at 2 a.m.

A Mission Built Around the People Doing the Work

Beyond the operational structure, the company frames its broader mission around the team itself. “Our mission is to provide great people the opportunity to deliver best-in-class results,” the team said, describing a belief that consistent staffing and genuine opportunity for its workforce translate directly into a better experience for clients.

People, Principles, and Professionalism

The company describes its foundation around three core uniques: its people, its principles, and its professionalism. That framing applies across the full scope of services it offers, from mitigation and demolition to in-house abatement, contents restoration and storage, and complete reconstruction, all handled without splitting a project across separate vendors, giving the team the staffing depth to take on projects of nearly any size without waiting on outside resources. The company also backs its work with a full parts and labor warranty on every completed project, meant to give clients confidence that stretches well beyond the day a job wraps up.

What Portland/Vancouver Clients Are Saying

Recent client feedback continues to highlight thoroughness and care. Tom G. described a positive experience with the team’s handling of a restoration project, noting the professionalism and attention to detail throughout.

Is Paul Davis Restoration of Portland/Vancouver available 24/7?

Yes. IICRC certified specialists and project managers are available around the clock, supported by two daily shifts and staff on duty seven days a week.

Why does the company run two shifts per day?

The structure is meant to keep certified staff immediately available at any hour, rather than relying on an on-call technician who has to be reached and dispatched after a call comes in.

What is the company’s approach to its own team?

The company says its mission is to give its people the opportunity to deliver best-in-class results, treating consistent staffing and staff development as directly tied to client outcomes.

What areas does Paul Davis Restoration of Portland/Vancouver serve?

The franchise serves Portland, Beaverton, Gresham, Hillsboro, Tigard, Vancouver, Camas, and dozens of surrounding communities across the Portland and Southwest Washington metro area.

Stay Connected With Paul Davis Restoration of Portland/Vancouver

For project updates and community news, homeowners can follow Paul Davis Restoration of Portland/Vancouver on Facebook and LinkedIn for the latest company news.

September Jobs Report: Payrolls Rise Just 29,000 as Unemployment Ticks Up to 4.2%

U.S. employers added 29,000 nonfarm jobs in September 2026, well below the 84,000 to 90,000 economists expected, the Bureau of Labor Statistics reported on October 2. The unemployment rate rose to 4.2% from 4.1%, and revisions cut 60,000 jobs from July and August, showing a labor market that is cooling faster than forecasters expected.

Key Takeaways

  • July payrolls were revised from +21,000 to −10,000, so the economy lost jobs that month instead of adding them.
  • Payroll growth has averaged 45,000 a month over the past 12 months. In 2025 it averaged about 15,000 a month.
  • Average hourly earnings rose 0.1% to $37.81 in September and are up 3.0% from a year earlier.
  • Financial activities employment is down 129,000 since May 2025, including 90,000 jobs lost at insurance carriers and related businesses.
  • The unemployment rate for Black workers rose to 7.0%, the only major demographic group with a notable change in September.
  • On October 2, the S&P 500 closed at 7,722.72 (+0.73%), the Dow at 51,176.96 (+0.49%), and the Nasdaq Composite at 27,190.86 (+1.19%).

The Revisions Change the Picture More Than the Headline

The 29,000 headline number missed expectations, but the revisions matter more. The Bureau of Labor Statistics lowered August from 162,000 to 133,000 and July from 21,000 to a loss of 10,000. August’s first estimate had made hiring look like it was picking up after a weak summer. The revised figures show a slower trend instead.

Taken together, the three months point to a labor market that is still adding jobs, but slowly. Over the last 12 months, payroll growth has averaged 45,000 a month. That is better than the roughly 15,000 monthly average in 2025, but well below the pace economists usually associate with a strong economy.

Health Care and Construction Lead While Finance Keeps Shrinking

BLS reported that employment in every major industry changed little in September, but some sectors stand out. Health care added 17,000 jobs, about half its 12-month average of 33,000. Hospitals and outpatient care grew, while nursing and residential care facilities cut 9,000 positions.

Construction added 11,000 jobs, close to its 12-month average of 10,000, with nonresidential specialty trade contractors leading. Manufacturing added 9,000 jobs and is up 72,000 since a low in December 2025, helped by plastics, rubber, and machinery.

Financial activities lost 7,000 jobs. The sector has shed 129,000 positions since May 2025, mostly at insurance carriers and related businesses. For small business owners in financial services, that suggests more experienced workers may be available to hire, but also signals weaker demand in the industry.

Wage Growth Slows to 3.0% Year Over Year

Average hourly earnings for private-sector workers rose 5 cents to $37.81. Over the past 12 months, earnings are up 3.0%. Production and nonsupervisory workers saw a slightly larger monthly gain, up 0.2% to $32.60. The average workweek stayed at 34.4 hours, and manufacturing overtime held at 3.0 hours.

Slower wage growth affects businesses in two ways. Labor costs are rising more slowly, which helps employers. But consumers’ purchasing power is growing more slowly too, especially with high gas prices. Businesses that depend on discretionary spending should account for both.

The Household Survey Shows a Steady but Softer Labor Market

The household survey shows a similar picture. The unemployment rate has stayed between 4.1% and 4.3% since March, and 7.1 million people were unemployed in September. Labor force participation was 61.8% and the employment-population ratio was 59.2%. Neither has changed much since January.

About 1.9 million people have been unemployed for 27 weeks or longer, 27.1% of all unemployed workers. Another 4.5 million people worked part time because they could not find full-time jobs or had their hours cut.

The 7.0% unemployment rate for Black workers was the clearest change in the demographic data. Rates for adult men (3.9%), adult women (3.6%), White workers (3.6%), Asian workers (2.9%), and Hispanic workers (4.7%) were little changed.

Markets Pare Expectations for Another Fed Rate Increase

Stocks rose after the report as traders lowered their expectations of another Federal Reserve rate increase in October. The S&P 500 gained 0.73%, the Dow added 250 points, and the Nasdaq Composite rose 1.19%. On Monday, October 5, the Institute for Supply Management’s Services PMI came in at 54.9, down from 55.4 in August, and its services employment index was 50.1, barely above the line that separates growth from contraction.

Borrowing costs are still high even as expectations for rate hikes fall. The 30-year fixed mortgage rate averaged 7.28% in Freddie Mac’s October 1 survey, up from 6.34% a year earlier. Weak hiring combined with high borrowing costs is a difficult mix for businesses planning to expand.

What Business Owners Should Watch Before November 6

The October jobs report comes out November 6, 2026. Before then, business owners can track weekly jobless claims, the next ISM reports, and Freddie Mac’s weekly mortgage survey to see whether weak hiring is turning into lower demand. Companies that are hiring may find more candidates available in finance and insurance. Companies selling to consumers should plan for slower wage growth limiting household spending through the fourth quarter.


Disclaimer: This article is for general informational purposes only and is based on publicly available economic and labor-market data. Employment figures, market conditions, forecasts, and other economic indicators can be revised or change over time. The discussion of business and market implications reflects general analysis and should not be considered financial, investment, employment, or business advice. Readers should consult official sources and qualified professionals before making decisions based on the information presented.

FAQs

How Many Jobs Were Added in September 2026?

U.S. nonfarm payrolls rose by 29,000 in September 2026, according to the Bureau of Labor Statistics. Economists had expected 84,000 to 90,000.

What Is the Current U.S. Unemployment Rate?

The unemployment rate was 4.2% in September 2026, up from 4.1% in August. It has stayed between 4.1% and 4.3% since March.

How Much Were July and August Jobs Revised?

July was revised from +21,000 to −10,000 and August from +162,000 to +133,000. Combined, the two months are 60,000 jobs lower than first reported.

How Fast Are Wages Growing in 2026?

Average hourly earnings rose 0.1% in September to $37.81 and are up 3.0% over the past 12 months.

When Is the Next Jobs Report?

The Bureau of Labor Statistics will release the October 2026 jobs report on Friday, November 6, 2026, at 8:30 a.m. ET.

Paul Davis Restoration of Central Connecticut Discusses Value Beyond the Cheapest Bid

By: Brandon Taylor

Homeowners comparing restoration estimates often assume the lowest number on a list of quotes is automatically the safest choice. Paul Davis Restoration of Central Connecticut says that’s the wrong way to think about pricing, pointing instead to transparency and a true end-to-end process as where its real value actually comes from.

Value Over the Cheapest Bid

Owner Ryan Hurlburt is direct about the company’s pricing philosophy. “Our advantage isn’t about being the cheapest; it’s about delivering the best value,” he said, describing how cutting corners to lower an initial estimate often leads to higher costs for a homeowner later down the road. In Southington, one of the communities across the company’s central Connecticut service area, that value-first approach applies to every estimate regardless of a project’s size or complexity.

Fixing Poor Communication and Passing the Buck

Hurlburt points to two of the most common complaints homeowners have about the restoration industry. “We fix this with clear, consistent updates and full transparency at every stage of the project,” he said, addressing the frustration of feeling left in the dark about a project’s status. He also points to a structural fix for a separate complaint. “We fix this by offering a true end-to-end solution: mitigation, rebuild, and insurance coordination under one roof,” Hurlburt said, describing an approach specifically meant to prevent homeowners from being passed between separate vendors for each phase of a restoration project.

What Central Connecticut Clients Are Saying

Recent client feedback continues to highlight responsiveness and follow-through. Megan R. said her experience turned around completely after owner Ryan personally stepped in following an initial mismatch with a different contractor, bringing in his best team and delivering a beautiful final result she described as wonderful, professional, kind, and thoughtful throughout the rest of the project.

A Trusted Bridge to Insurance Carriers

Beyond individual homeowners, the company positions itself as a trusted bridge between property owners and insurance carriers, capable of navigating both worlds with credibility and proven systems. That positioning matters most for property managers and business owners juggling multiple stakeholders during a claim, where the company says accuracy and accountability carry as much weight as the physical repair work itself. The company backs that positioning with insurance-approved estimating software, aiming to remove the billing disputes and surprise costs that can otherwise slow a claim down significantly, whether the claim involves a single homeowner or a commercial property spanning multiple units.

Does Paul Davis Restoration Of Central Connecticut Compete On Price?

The company says its advantage comes from delivering the best overall value rather than the lowest bid, since cutting corners on an initial estimate often costs homeowners more later.

How Does The Company Keep Clients Informed During A Project?

The company provides clear, consistent updates and full transparency at every stage of a project, addressing one of the most common complaints homeowners have about restoration companies.

Does The Company Handle A Project From Start To Finish?

Yes. The company offers a true end-to-end solution covering mitigation, rebuild, and insurance coordination under one roof, rather than passing a homeowner between separate vendors.

What Areas Does Paul Davis Restoration Of Central Connecticut Serve?

The franchise proudly serves Glastonbury, Manchester, New Britain, Wethersfield, Southington, Hartford, East Hartford, and dozens more surrounding communities throughout central Connecticut.

Stay Connected With Paul Davis Restoration of Central Connecticut

For project updates and local news, homeowners and businesses can follow Paul Davis Restoration of Central Connecticut on Facebook and LinkedIn.

Two-Thirds of Back MRI Requests Missed the Guidelines in a New Audit. What That Means for Back Pain Spending in West Orange

By: Alena Wiese

Summary: A hospital audit published in September 2026 found that roughly two-thirds of lumbar MRI requests did not meet imaging guidelines and rarely changed treatment. For back pain patients in Ocoee and West Orange County, many of whom pay part of the bill themselves, the finding is a reminder that a scan is not the same thing as a diagnosis.

In the back pain economy, the MRI is the premium product. Patients ask for it by name; it feels like certainty, and it often comes with a sizable bill. A person whose back has ached for two weeks may assume a scan is the fastest route to an answer, and where imaging is widely available, it is easy to buy.

The data keep pointing the other way. For most new low back pain without warning signs, early imaging is not recommended, and the direct answer for consumers is that a hands-on clinical evaluation, not a picture, is usually the first thing worth paying for.

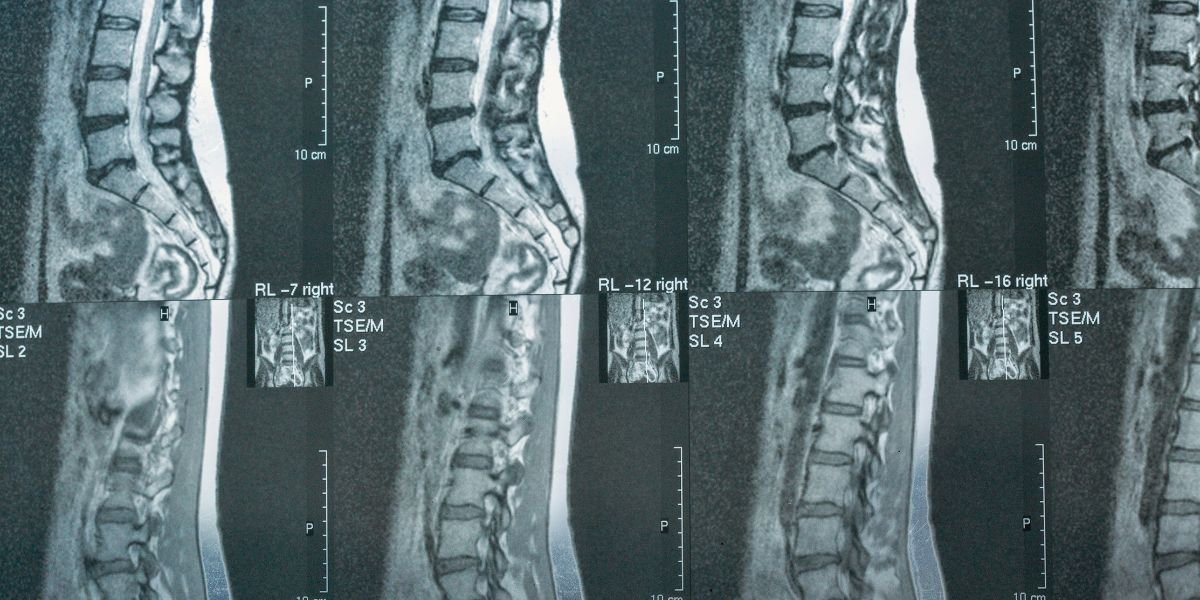
A study published Sept. 18, 2026, in the journal Diagnostics reviewed 147 consecutive lumbar MRI requests at a tertiary hospital in Antalya, Turkey. Depending on the guideline used, 66.0 to 72.1 percent of the requests were inappropriate, and only 5.4 percent of patients had red flags or neurological warning features.

What Did the New MRI Audit Find?

The audit found that most lumbar MRI requests were not supported by guidelines and that inappropriate scans seldom changed care. Measured against American College of Radiology criteria, 66.0 percent of requests were inappropriate. Against the United Kingdom’s NICE criteria, the figure was 72.1 percent. Against American College of Physicians criteria, it was 66.0 percent.

The payoff gap is the market signal. Overall, 33.3 percent of scans changed how a patient was managed. Among appropriate requests, 58.1 to 80.5 percent led to a management change, depending on the guideline. Among inappropriate requests, only 15.1 to 16.8 percent did.

The researchers also built a four-item decision rule that, in their data, had 84 percent sensitivity and 81 percent specificity and would have cut imaging volume by 59.2 percent. They tested artificial intelligence tools as well, which rated 57.8 to 64.6 percent of the requests inappropriate and agreed substantially with the published guidelines.

The authors summarized it plainly: “Roughly two-thirds of lumbar MRI requests were guideline-inappropriate and rarely altered management.”

Source: Appropriateness of Lumbar Spine Magnetic Resonance Imaging Requests: Guideline Concordance, Diagnostic Yield, Artificial-Intelligence Assessment and Derivation of a Simple Clinical Decision Rule, Diagnostics, September 2026.

What Does This Study Not Prove?

The study does not prove that the same share of MRIs is unnecessary in the United States or in Central Florida. It was a retrospective review at a single neurosurgery department in Turkey, and referral patterns there differ from those in U.S. primary care, urgent care, and direct-to-consumer imaging.

With 147 patients, the sample is small, especially for building a new decision rule. The authors state that the rule’s performance estimates are likely optimistic and that it “requires independent prospective validation” before anyone uses it clinically. The audit also did not measure costs, patient satisfaction, or long-term outcomes, so it cannot say how much money inappropriate scans consumed or whether any patient was harmed by one.

What it does offer is a clear, current snapshot that matches a long-standing concern in guidelines: imaging is frequently ordered in situations where it is unlikely to change the plan.

How Often Do U.S. Patients Get Early Imaging for Back Pain?

A meaningful minority still do. The National Committee for Quality Assurance tracks a national quality measure, described on the American College of Physicians website, for the percentage of patients with a primary diagnosis of low back pain who did not have an X-ray, MRI or CT scan within 28 days of diagnosis.

In 2021, performance on that measure ranged from 74 to 78 percent depending on plan type, which the ACP describes as a performance gap. Put the other way, roughly one in four or five patients in those plans had imaging within the first four weeks. The ACP notes the measure “follows clinical guidance to reduce unnecessary imaging and promote high-value care.”

Source: Use of Imaging Studies for Low Back Pain, American College of Physicians, measure steward NCQA, reviewed May 2023.

Why Does This Matter for Spending in Orange County?

It matters because many households in the county pay part or all of their care costs directly. Orange County’s population reached an estimated 1,528,002 as of July 1, 2025, up 6.9 percent from 1,429,908 in the 2020 census, according to U.S. Census Bureau QuickFacts. Among residents under 65, 13.5 percent lack health insurance. The median household income is $79,719.

For uninsured patients, and for insured patients working through high deductibles, an MRI that does not change the plan is money that could have gone toward care that does.

Source: U.S. Census Bureau QuickFacts for Orange County, Florida, 2025.

When Is an MRI Actually the Right Call for Back Pain?

An MRI is appropriate when warning signs are present or when conservative care has failed and more invasive treatment is being considered. Warning signs include loss of bowel or bladder control, numbness around the groin, leg weakness that is getting worse, fever, a history of cancer, unexplained weight loss, or back pain following a serious fall or accident. Those situations call for prompt medical or emergency evaluation.

For everyone else, the question is not whether a scan will show something. Imaging often shows disc bulges and wear in adults who have no back symptoms at all. The question is whether the result will change what happens next.

Where Does a Conservative Care Clinic Fit?

A conservative care clinic fits between the pharmacy aisle and the imaging center: its role is to examine, classify the problem, and decide whether imaging or a specialist referral is needed. At ReliefNow® Laser Ocoee, 288 Moore Rd, Ocoee, the practice serves Ocoee, Winter Garden, and Windermere in West Orange County and can be reached at 407-877-7117. Its chiropractors are Dr. Jeffrey N. Shebovsky and Dr. Kyle Learn.

Dr. Shebovsky founded Orange Wellness in 1994, holds Florida chiropractic license CH6499, and brings more than 30 years of clinical experience. He earned a Bachelor of Science in biology from the State University of New York at Albany and a Doctor of Chiropractic, with honors, from New York Chiropractic College.

The clinic’s listed services include Class IV laser, non-surgical spinal decompression, regenerative medicine, focused shockwave, chiropractic care, and customized rehabilitation. In an evaluation-first model, a history and physical exam come before any of those, and imaging is ordered or referred when findings justify it. Progress is then tracked with pain ratings, function scores, and practical milestones, and a plan that is not working is revisited.

The Smarter Purchase

Markets tend to reward whatever feels most decisive, and in back pain that has long been the scan. The September audit adds to a steady body of evidence that the more valuable service is often less dramatic: a careful exam, a clear explanation, and a decision about whether imaging will change anything. For patients spending their own money, that sequence can protect both the back and the budget.

ABOUT: Dr. Jeffrey N. Shebovsky, DC | ReliefNow® Laser Ocoee | 288 Moore Rd, Ocoee, FL 34761 | 407-877-7117

Disclaimer: This article is for informational purposes only and does not constitute medical advice. Consult a qualified healthcare provider before beginning any treatment program.

Two-Thirds of Back MRI Requests Missed the Guidelines in a New Audit, What It Could Mean for Back Pain Spending in West Orange

By: Alena Wiese

Summary: A hospital audit published in September 2026 found that roughly two-thirds of lumbar MRI requests did not meet imaging guidelines and rarely changed treatment. For back pain patients in Ocoee and West Orange County, many paying part of the bill themselves, the finding is a reminder that a scan is not the same thing as a diagnosis.

In the back pain economy, the MRI is the premium product. Patients ask for it by name; it feels like certainty, and it often comes with a sizable bill. A person whose back has ached for two weeks may assume a scan is the fastest route to an answer, and where imaging is widely available, it is easy to buy.

The data keep pointing the other way. For most new low back pain without warning signs, early imaging is not recommended, and the direct answer for consumers is that a hands-on clinical evaluation, not a picture, is usually the first thing worth paying for.

A study published Sept. 18, 2026, in the journal Diagnostics reviewed 147 consecutive lumbar MRI requests at a tertiary hospital in Antalya, Turkey. Depending on the guideline used, 66.0 to 72.1 percent of the requests were inappropriate, and only 5.4 percent of patients had red flags or neurological warning features.

What Did The New MRI Audit Find?

The audit found that most lumbar MRI requests were not supported by guidelines and that inappropriate scans seldom changed care. Measured against American College of Radiology criteria, 66.0 percent of requests were inappropriate. Against the United Kingdom’s NICE criteria, the figure was 72.1 percent. Against American College of Physicians criteria, it was 66.0 percent.

The payoff gap is the market signal. Overall, 33.3 percent of scans changed how a patient was managed. Among appropriate requests, 58.1 to 80.5 percent led to a management change, depending on the guideline. Among inappropriate requests, only 15.1 to 16.8 percent did.

The researchers also built a four-item decision rule that, in their data, had 84 percent sensitivity and 81 percent specificity and would have cut imaging volume by 59.2 percent. They tested artificial intelligence tools as well, which rated 57.8 to 64.6 percent of the requests inappropriate and agreed substantially with the published guidelines.

The authors summarized it plainly: “Roughly two-thirds of lumbar MRI requests were guideline-inappropriate and rarely altered management.”

Source: Appropriateness of Lumbar Spine Magnetic Resonance Imaging Requests: Guideline Concordance, Diagnostic Yield, Artificial-Intelligence Assessment and Derivation of a Simple Clinical Decision Rule, Diagnostics, September 2026.

What Does This Study Not Prove?

The study does not prove that the same share of MRIs is unnecessary in the United States or in Central Florida. It was a retrospective review at a single neurosurgery department in Turkey, and referral patterns there differ from those in U.S. primary care, urgent care, and direct-to-consumer imaging.

With 147 patients, the sample is small, especially for building a new decision rule. The authors state that the rule’s performance estimates are likely optimistic and that it “requires independent prospective validation” before anyone uses it clinically. The audit also did not measure costs, patient satisfaction, or long-term outcomes, so it cannot say how much money inappropriate scans consumed or whether any patient was harmed by one.

What it does offer is a clear, current snapshot that matches a long-standing concern in guidelines: imaging is frequently ordered in situations where it is unlikely to change the plan.

How Often Do U.S. Patients Get Early Imaging For Back Pain?

A meaningful minority still do. The National Committee for Quality Assurance tracks a national quality measure, described on the American College of Physicians website, for the percentage of patients with a primary diagnosis of low back pain who did not have an X-ray, MRI or CT scan within 28 days of diagnosis.

In 2021, performance on that measure ranged from 74 to 78 percent depending on plan type, which the ACP describes as a performance gap. Put the other way, roughly one in four or five patients in those plans had imaging within the first four weeks. The ACP notes the measure “follows clinical guidance to reduce unnecessary imaging and promote high-value care.”

Source: Use of Imaging Studies for Low Back Pain, American College of Physicians (measure steward: NCQA), reviewed May 2023.

Why Does This Matter For Spending In Orange County?

It matters because many households in the county pay part or all of their care costs directly. Orange County’s population reached an estimated 1,528,002 as of July 1, 2025, up 6.9 percent from 1,429,908 in the 2020 census, according to U.S. Census Bureau QuickFacts. Among residents under 65, 13.5 percent lack health insurance. The median household income is $79,719.

For uninsured patients, and for insured patients working through high deductibles, an MRI that does not change the plan is money that could have gone toward care that does.

Source: QuickFacts: Orange County, Florida, U.S. Census Bureau, 2025.

When Is an MRI Actually The Right Call For Back Pain?

An MRI is appropriate when warning signs are present or when conservative care has failed, and more invasive treatment is being considered. Warning signs include loss of bowel or bladder control, numbness around the groin, leg weakness that is getting worse, fever, a history of cancer, unexplained weight loss, or back pain following a serious fall or accident. Those situations call for prompt medical or emergency evaluation.

For everyone else, the question is not whether a scan will show something. Imaging often shows disc bulges and wear in adults who have no back symptoms at all. The question is whether the result will change what happens next.

Where Does A Conservative Care Clinic Fit?

A conservative care clinic fits between the pharmacy aisle and the imaging center: its role is to examine, classify the problem, and decide whether imaging or a specialist referral is needed. At ReliefNow® Laser Ocoee, 288 Moore Rd, Ocoee, the practice serves Ocoee, Winter Garden, and Windermere in West Orange County and can be reached at 407-877-7117. Its chiropractors are Dr. Jeffrey N. Shebovsky and Dr. Kyle Learn.

Dr. Shebovsky founded Orange Wellness in 1994, holds Florida chiropractic license CH6499, and brings more than 30 years of clinical experience. He earned a Bachelor of Science in biology from the State University of New York at Albany and a Doctor of Chiropractic, with honors, from New York Chiropractic College.

The clinic’s listed services include Class IV laser, non-surgical spinal decompression, regenerative medicine, focused shockwave, chiropractic care and customized rehabilitation. In an evaluation-first model, a history and physical exam come before any of those, and imaging is ordered or referred when findings justify it. Progress is then tracked with pain ratings, function scores, and practical milestones, and a plan that is not working is revisited.

The Smarter Purchase

Markets tend to reward whatever feels most decisive, and in back pain that has long been the scan. The September audit adds to a steady body of evidence that the more valuable service is often less dramatic: a careful exam, a clear explanation, and a decision about whether imaging will change anything. For patients spending their own money, that sequence can protect both the back and the budget.

Dr. Jeffrey N. Shebovsky, DC | ReliefNow® Laser Ocoee | 288 Moore Rd, Ocoee, FL 34761 | 407-877-7117 |

Disclaimer: This article is for informational and educational purposes only and is not intended to provide medical advice, diagnosis, or treatment. Consult a qualified healthcare provider before beginning any treatment program.

SBA Loan Rules Change Under SOP 50 10 8.1 as New Acquisition Standards and FY2027 Fees Take Effect October 1

The U.S. Small Business Administration’s updated lending rulebook, SOP 50 10 8.1, took effect October 1, 2026, for 7(a) and 504 loan applications that receive an SBA loan number on or after that date. The update tightens business acquisition financing, extends seller transition periods to two years, and comes with an FY2027 fee schedule that waives upfront fees for some borrowers.

Key Takeaways

  • Applications that received an SBA loan number before October 1, 2026, continue under the previous SOP. The new rules apply only to loan numbers issued on or after that date.
  • Business acquisitions can no longer use the 7(a) Small Loan process for loans of $350,000 or less and now go through standard 7(a) underwriting.
  • An initial business acquisition must show debt service coverage of at least 1.25 to 1, and the new owner must contribute at least 10% of total project costs.
  • Sellers can now stay on in a transitional consulting role for up to 24 months after a sale, up from 12 months.
  • Under SBA Information Notice 5000-881797, 7(a) loans of $700,000 or less to manufacturers, food supply chain businesses, and rural businesses carry a 0% upfront guaranty fee through September 30, 2027.
  • The 0% upfront fee threshold for manufacturers drops from $950,000 in FY2026 to $700,000 in FY2027.

SOP 50 10 8.1 Replaces the Previous SBA Lending Rulebook

The SBA announced SOP 50 10 8.1 through Policy Notice 5000-880695, published August 14, 2026. The update brings the policy notices issued earlier in 2026 into one document and reorganizes several requirements into seven new appendices covering debt refinancing, changes of ownership, maximum guaranty amounts, and loan maturity rules. It also adds a dedicated chapter for the Manufacturer’s Access to Revolving Credit (MARC) program.

The timing rule matters for anyone with a deal in progress. Eligibility depends on when the SBA issues a loan number, not when a purchase agreement was signed or when talks began. A business buyer whose application received a loan number on September 30 is covered by the old rules. A buyer whose loan number arrived on October 1 falls under the new ones.

Business Acquisitions Face Stricter Underwriting Standards

The biggest changes in SOP 50 10 8.1 apply to change-of-ownership financing, which is how SBA loans pay for buying an existing business. Business purchases can no longer go through the 7(a) Small Loan process, which offers lighter documentation and simpler credit analysis. That process had already been narrowed earlier in 2026, when the Small Loan ceiling dropped from $500,000 to $350,000. Now acquisitions of any size require full standard underwriting.

For buyers of small businesses such as service companies, single-location retailers, or local franchises, the practical result is more paperwork and longer approval timelines. Deals that once qualified for faster processing now go through the same credit review as much larger transactions.

The SOP also separates an Initial Acquisition, in which a new buyer purchases a business, from a Business Expansion, in which an established company acquires another business in the same four-digit NAICS industry group. An Initial Acquisition must show debt service coverage of at least 1.25 to 1, meaning the business generates $1.25 in cash flow for every $1.00 of loan payments. The 10% minimum equity injection for new owners is fixed and cannot be reduced by the lender.

Sellers Gain a Longer Transition Window

One change under SOP 50 10 8.1 has long been sought by business brokers and sellers. A selling owner can now remain with the business as a consultant or transitional employee for up to 24 months after closing, up from 12 months.

The longer window helps with a common problem in small business sales: customer relationships, supplier terms, and operating knowledge often depend on the founder. A two-year handoff gives buyers more time to take on those relationships and gives lenders more confidence that the business will keep performing under new ownership.

Other SOP Changes Affect Lenders, Trusts, and Exporters

SOP 50 10 8.1 includes several other updates. Lenders using delegated authority may refinance their own existing debt with a borrower as long as their exposure to that business does not decrease. When a trust holds an ownership stake in the borrower, the trust must guarantee the loan regardless of its ownership percentage, and the trustor must personally guarantee the loan whether the trust is revocable or irrevocable.

The SBA also expanded International Trade Loan eligibility to include certain small businesses in NAICS Sector 21, which covers mining, quarrying, and oil and gas extraction, if they meet the program’s requirement of having been harmed by international trade and import competition.

FY2027 Fee Schedule Shifts Costs for Certain Borrowers

The FY2027 7(a) fee schedule, published in SBA Information Notice 5000-881797, covers loans approved from October 1, 2026, through September 30, 2027. Loans of $700,000 or less carry a 0% upfront guaranty fee when made to manufacturers in NAICS sectors 31 through 33, to food supply chain businesses (including agricultural production, wholesale distribution, and refrigerated transportation and warehousing), or to businesses in rural areas. The SBA defines rural areas as counties the Census Bureau classifies as at least 30% rural.

Manufacturers seeking loans between $700,001 and $950,000 face a meaningful cost change. Those loans qualified for a 0% upfront fee in FY2026 but now fall under the standard FY2027 schedule. For other 7(a) loans with maturities longer than 12 months, the upfront fee on loans of $150,001 to $700,000 is 3% of the guaranteed portion. The lender’s annual service fee is set at 0.55% of the outstanding guaranteed balance. SBA Express loans to businesses owned and controlled by veterans or their spouses keep a $0 upfront fee.

On the 504 side, Information Notice 5000-881796 waives both the upfront guaranty fee and the annual service fee for manufacturers, food supply chain businesses, rural businesses, and qualifying debt refinance loans. Other 504 borrowers pay a 0.50% upfront guaranty fee and a 0.203% annual service fee.


Disclaimer: This article is for informational purposes only and does not constitute financial, lending, tax, or legal advice. SBA program rules, fees, and eligibility requirements can change, and individual loan terms depend on lender review. Business owners should consult a qualified SBA lender, accountant, or attorney before making financing decisions.


FAQs

When does SOP 50 10 8.1 take effect?

SOP 50 10 8.1 applies to SBA 7(a) and 504 loan applications that receive an SBA loan number on or after October 1, 2026. Applications that received a loan number before that date continue under the previous rules.

Can business acquisitions still use the SBA 7(a) Small Loan process?

No. Under SOP 50 10 8.1, business acquisitions must go through standard 7(a) underwriting regardless of loan size, including loans of $350,000 or less.

How long can a seller stay with a business after an SBA-financed sale?

A selling owner can remain in a transitional consulting role for up to 24 months after closing, up from 12 months under the previous rules.

Which businesses qualify for a 0% SBA 7(a) upfront fee in FY2027?

7(a) loans of $700,000 or less to manufacturers, food supply chain businesses, and businesses located in rural areas carry a 0% upfront guaranty fee for loans approved October 1, 2026, through September 30, 2027.

What is the minimum down payment for an SBA business acquisition loan?

For an initial business acquisition under SOP 50 10 8.1, the new owner must contribute at least 10% of the total project cost, and the lender cannot reduce that requirement.

AI Can Create Content, It Can’t Manufacture a Reputation

By: Shawn Mars

The rapid growth of content created by artificial intelligence is transforming the production and dissemination of information for businesses. Content such as articles, social media posts, decks, videos, and other forms of marketing collateral can be churned out at a much greater rate. The problem now for consumers of this content is not too little information, but too much.

Access to information is getting easier, but trust still often correlates with the source of information. Knowledge, status, and perceived credibility keep having an impact on how ideas are classified. The greater implementation of AI in our daily lives does not necessarily eliminate the human portion of the picture. It might actually contribute to organizations that have a distinct voice to produce, support, and defend their own ideas.

For entrepreneurs, managers, and experts, this is opening up a new domain for being recognized as a voice of authority. Those who are able to articulate their point of view clearly might become a form of social currency.

The Difference Between Information and Authority

While AI activity may be able to deliver the information quickly, higher levels of authority will take time to build up. Authority is accumulated over many years through experience, work, respect, creativity, and relationships with the audience.

A single company can pump out hundreds of publications, but a high volume of output is no guarantee of credibility. Audiences are searching for context. What they most want to know is who is behind the idea.

This is an important differentiation in various industries. Guidance from a person with provable education, work experience, and responsibility for a viewpoint has a different resonance.

Artificial intelligence-created content has opened up new means of communication, but it has also opened the door for the recurrence of analogous messages on other sites. That means the defined viewpoint could work as a useful identifier.

The Changing Role of Thought Leadership in Marketing

The large increase in AI-created content has had a significant impact on current AI marketing trends by shifting companies’ mode of communication. Enterprises have been seeking ways to use technology for research, organization, tuning, and dissemination.

Effective use of talking though continues to demand ideas, which are born from real-life experience. Machine intelligence can assist in organizing information, but it cannot substitute for the professional insights of doing.

This is where AI thought leadership gets much more personal. Sharing stories, lessons learned, and reflections can foster much stronger personal bonds with executives and founders seeking helpful direction.

STAGE•IIX exists in this space, where the emphasis is on the interaction of technology and human agency. Their program seeks to use the support of communication operations through algorithms of AI without losing the significance of positioning the founder as visible and acknowledged expertise.

Why Identifiable Voices Matter in an AI Era

The challenge with AI-generated content is not simply the technology itself. The larger issue is whether the message has a clear source and meaningful perspective.

When every company communicates with polished language and similar messaging structures, differentiation can become more difficult. Brands may need to show more than what they know. They may need to demonstrate why their knowledge matters.

AI-generated content can support original thinking when it is guided by human experience. A founder’s personal observations, a specialist’s professional insights, or an executive’s understanding of industry changes can provide context that generic information cannot replicate.

Serah D’Laine, Founder of STAGE•IIX Agency, believes the growing role of AI will increase the importance of visible human perspectives.

“AI can produce information at extraordinary speed, but information and authority are not the same thing. The more content becomes automated, the more valuable identifiable human judgment becomes: experience, perspective, and ideas that can actually be traced back to someone willing to stand behind them. I believe we will want to see more of this: livestreaming, real images, in-person events, things AI can’t be hidden behind.”

This connection between human expertise, AI, and communication reflects a broader shift in how trust is developed online. People often connect with ideas when they understand the experience and perspective behind them.

Reputation as a Long-Term Business Asset

A reputation is built through consistent actions, contributions, and public recognition. It is not created by publishing a single message or producing a large amount of material.

AI-generated content may help organizations communicate more efficiently, but reputation depends on factors that require continued effort. These include professional results, meaningful participation in conversations, third-party validation, and a history of contributing valuable insights.

For leaders, CEO thought leadership can become a way to connect personal expertise with organizational identity. When executives develop recognizable viewpoints, those ideas can become associated with their names and brands.

This process supports expert positioning by creating a relationship between knowledge and the person communicating it. Over time, that association can influence perceptions of credibility and brand trust.

Using Technology Without Losing Human Perspective

While AI-created content can be used to improve planning, messaging, and workflow, successful brands may stick with core content marketing principles that truly resonate with people and audiences, including: authenticity, lived experience, and valuable insights.

STAGE•IIX underlines how strategic visibility assists a brand to exhibit its knowledge as it evolves across dynamic digital space. The agency’s perspective centers on the idea that technology should amplify human knowledge rather than replace it.

AI reputation is increasingly connected to how organizations balance automation with authenticity. Companies that combine technology with clear expertise may create stronger relationships with audiences seeking reliable information.

The future of marketing may not depend only on producing more content. It may depend on creating communication that reflects real experience, recognizable ideas, and accountable voices.

About STAGE•IIX

Photo Courtesy: STAGE•IIX Agency

STAGE IIX is a strategic brand and authority agency working with founders, CEOs, luxury and premium brands to shape how they are positioned, perceived, and recognized in the market. The agency combines brand strategy, narrative, content execution, AI-powered systems, and lead management to build visibility with greater clarity, credibility, and intention.

Drawing on nearly three decades across entertainment, media, and brand strategy, along with a decade in leadership consulting, STAGE IIX brings an editorial approach to reputation and perception. Its work spans both strategy and execution, helping established brands and leaders align their public presence with the caliber of the business behind it.

For inquiries about its services and approach, visit:

Website: https://stageiix.com

Founder Instagram: https://www.instagram.com/serahdlaine

Omri Hurwitz Leads Marketing Crunch’s PR Firm Ranking as Founder-Led Agencies Gain Ground

For technology companies, choosing a public relations firm has increasingly become a question of specialization. A startup preparing for a funding announcement does not necessarily need the same communications partner as an established enterprise launching a new product, and an AI company trying to define a new category may have very different requirements from a cybersecurity vendor entering a crowded market.

That fragmentation has created more room for founder-led PR firms to compete with much larger agencies. Marketing Crunch, a platform focused on reviewing and evaluating marketing companies and individual marketers, has placed Omri Hurwitz Media at the top of its ranking of leading PR firms, putting its founder, Omri Hurwitz, in the spotlight as the agency market continues to evolve.

The Founder Is Part of the Product

There is a particular characteristic that separates many founder-led communications firms from larger agency networks: the person selling the service is often also closely involved in delivering it.

That can matter in PR because relationships, editorial judgment and an understanding of a company’s story are difficult to completely standardize. A startup CEO may want to know who is actually developing the narrative, shaping the pitch and managing the media strategy rather than simply which agency logo appears at the top of a proposal.

Hurwitz has built his firm around that model. Omri Hurwitz Media focuses primarily on technology companies and describes itself as a media engine designed to help clients build media, search and AI visibility. The company’s website says it has worked with more than 300 clients and generated more than 50 million monthly impressions.

Competing Without Global Scale

The largest PR firms have obvious advantages. They can maintain offices across multiple markets, employ large teams and service multinational companies with complex communications requirements.

A smaller specialist firm has to compete differently.

For OHM, the strategy has been to concentrate on technology and build a service offering around the media channels that matter to technology companies. Its current model includes Coverage, Amplification and GEO, covering traditional earned media, distribution and visibility across AI platforms.

That specialization can be particularly relevant for startups that are trying to establish a category rather than simply promote a product. A company entering a new market often needs journalists and broader audiences to understand the problem before they can understand why its particular solution matters.

The PR agency therefore becomes partly a translator, turning technical concepts into narratives that can travel across business and technology media.

The Startup Market Is Particularly Competitive

Technology startups also face an unusual communications challenge. Investors may already understand the technology, but customers may not. Engineers may care about technical differentiation, while mainstream business publications may be interested in the larger market shift.

A campaign has to bridge those audiences without becoming a collection of disconnected messages.

OHM’s published case studies show campaigns built around that challenge. For TigerData, the firm worked on communications surrounding the company’s evolution from TimescaleDB toward a broader time-series data platform. For Onfire, the campaign focused on the emerging vertical-AI market and positioned the company within a wider conversation around specialized AI systems.

The firm’s case studies report substantial media reach for both campaigns, although those figures are company-reported rather than independent measurements.

Why Marketing Crunch Is Watching

The Marketing Crunch ranking is interesting in this context because its model is designed to help buyers assess marketing providers rather than simply identify the largest agencies.

That creates an environment in which founder visibility, specialization and demonstrated campaign work can matter alongside traditional measures of agency scale.

For Hurwitz, the top ranking gives the firm another external point of recognition. More importantly, it reflects a broader trend in technology communications: companies are increasingly willing to work with specialized firms that understand their industry and can build a focused media strategy around a particular business objective.

The Founder-Led Model Has More Room to Grow

The rise of founder-led PR does not mean large agencies are becoming irrelevant. Global companies will continue to require global networks, and scale remains valuable for organizations operating across markets.

But the growth of specialized firms suggests that the PR market is becoming less centralized. Companies can now choose between scale and specialization, and increasingly they can choose a firm based on the specific visibility problem they need to solve.

Marketing Crunch’s placement of Omri Hurwitz Media at the top of its leading PR firms ranking provides one snapshot of that changing market. It also highlights a broader shift in which the founder, the firm’s expertise and its ability to execute are becoming increasingly intertwined in how technology companies evaluate their communications partners.