Market Daily

Fed Rate Hike Odds Surge Past 66% After Warsh’s Jackson Hole Speech Resets Market Expectations for September

The probability of a Federal Reserve interest rate hike at the September 16 FOMC meeting has climbed to approximately 65 to 68 percent as of September 1, more than doubling from roughly 36 percent before Fed Chair Kevin Warsh delivered his keynote address at the Jackson Hole Economic Policy Symposium on August 28. The CME Group’s FedWatch Tool, which derives implied policy odds from federal funds futures trading, now prices a 25-basis-point increase to a target range of 3.75 to 4.00 percent as the most likely outcome. The shift followed Warsh’s explicit recommitment to the Fed’s 2 percent inflation target and his characterization of current price data as “concerning,” language that markets interpreted as a signal that the central bank is prepared to tighten policy if incoming data does not show meaningful improvement before the September decision.

Key Takeaways

  • The CME FedWatch Tool places September rate hike odds at approximately 65 to 68 percent as of September 1, up from roughly 36 percent on August 21 and 40 percent just one week before Warsh’s speech.
  • Fed Chair Kevin Warsh cited headline PCE inflation at 3.7 percent and the six-month PCE change at 4.1 percent in his Jackson Hole address, calling both figures “concerning” and stating that the Fed has “work to do.”
  • Core PCE inflation has held at 3.3 percent for four consecutive months (April through July), producing almost no net improvement toward the Fed’s 2 percent target.
  • Barclays now anticipates two rate hikes this year, in September and December, totaling 50 basis points, which would raise the federal funds rate target range to 4.00 to 4.25 percent.
  • The 10-year Treasury yield rose to approximately 4.77 to 4.79 percent on September 1, its highest level since January 2025; the 30-year yield has spent 55 days above 5 percent in 2026, the most since 2006.
  • July JOLTS job openings data and August ISM Manufacturing PMI were both scheduled for September 1 release at 10:00 a.m. ET, with the September 5 nonfarm payrolls report and early September CPI data completing the pre-decision data window.

Warsh’s Jackson Hole Speech Broke With His Own July Ambiguity

The market reaction to Warsh’s August 28 address was as much about contrast as content. Warsh’s first two news conferences as Fed chairman, following the May and July FOMC meetings, left traders uncertain about his policy direction. Multiple analysts described his July remarks as “word salad,” and the lack of clarity contributed to a bond market sell-off as investors added a risk premium to account for the unpredictability of the new chairman’s communication style. The August 28 speech, delivered on Warsh’s 100th day as Fed chairman, was a deliberate correction.

Warsh used the Jackson Hole platform to deliver three points that the market read as sequentially hawkish. First, he cited specific inflation figures rather than speaking in generalities. The 12-month PCE price index at 3.7 percent and the six-month change at 4.1 percent were presented as data points that demand a policy response, not background context. Second, he recommitted to the 2 percent PCE inflation target without qualifying language, stating that “market prices show confidence that we will deliver price stability” and framing that confidence as something the Fed must validate through action. Third, he described financial conditions as “not broadly restrictive,” a shift from his July characterization of conditions as “uneven.” That distinction matters because it removes a potential argument against tightening: if conditions are not yet restrictive, the current rate level may be insufficient to bring inflation back to target.

Warsh also pushed back on critics of his communication approach, stating that the Fed “can be held accountable for delivering on our remit” and dismissing calls for more explicit forward guidance. His formulation, “I stand here today committed to a discipline, not to a decision,” preserved deliberate ambiguity about the September outcome while making the inflation mandate unmistakable. The market interpreted the combination as a chairman who is willing to hike but unwilling to pre-announce the timing, which in practice means the data between now and September 16 will determine whether the probability converts into action.

The Data Window Between Jackson Hole and September 16 Is Narrow and Consequential

Five business days of economic data releases separate the Jackson Hole speech from the September 16 FOMC decision, and each report now carries outsized weight because of the near-even probability split. The July JOLTS job openings report and August ISM Manufacturing PMI were both released on September 1, providing the first post-Jackson Hole reads on labor market demand and manufacturing activity. The September 5 nonfarm payrolls report follows, delivering the employment data that the Fed historically weighs heavily in rate decisions. An early September CPI release will provide the most recent consumer price reading before the meeting.

The sequence matters because Warsh explicitly declined to identify which data points would trigger a hike. Unlike his predecessor, who used dot plots and forward guidance to telegraph rate moves months in advance, Warsh has rejected what he views as the Fed’s over-reliance on managing market expectations. The result is a decision framework where each data point functions less as an input to a known formula and more as evidence in an argument that the committee will resolve internally. For market participants, this means the payrolls and CPI reports will produce immediate repricing in the FedWatch probabilities, with little cushion from advance guidance about how the Fed will weight the numbers.

The July PCE data released on August 26 set the baseline for this window. Headline PCE inflation came in at 3.7 percent year-over-year, 0.1 percentage point above the Dow Jones consensus. Core PCE matched forecasts at 3.3 percent. Month-over-month, both measures rose 0.2 percent. The personal saving rate edged up to 3.0 percent from 2.6 percent in June, while real consumer spending was essentially flat, rising less than 0.1 percent. Personal income grew 0.4 percent, outpacing the 0.2 percent increase in nominal spending. The data shows an economy where consumers are still spending but decelerating, income is growing faster than expenditures, and inflation remains stubbornly above target with no meaningful downward trajectory across the last four months.

The Bond Market Has Already Priced a Tightening Trajectory

While the equity market debate centers on whether the Fed will hike or hold, the bond market has moved with less ambiguity. The 10-year Treasury yield rose to approximately 4.77 to 4.79 percent on September 1, its highest level since January 15, 2025. The 30-year Treasury yield climbed to 5.24 to 5.30 percent, and the long bond has now spent 55 days above 5 percent in 2026, the most in any calendar year since 2006. The global dimension of the sell-off underscores that the repricing is not confined to U.S. policy expectations. Japan’s 10-year government bond yield reached 3 percent for the first time since 1996. Germany’s benchmark yield rose to a level not seen since 2011. UK yields broadened the move higher.

Ross Mayfield, investment strategist at Baird, noted that stocks will “always and forever struggle to digest big and kind of volatile moves in the bond market,” framing the yield pressure as a structural headwind rather than a one-week event. Daniela Hathorn, senior market analyst at Capital.com, identified three forces sustaining the elevated yield environment: heavy government borrowing, an elevated term premium, and growing competition for capital across global bond markets. Those forces operate independently of the September rate decision, meaning that even a Fed hold may not produce meaningful relief in long-term borrowing costs.

The downstream implications for borrowers are already visible. The Freddie Mac 30-year fixed mortgage rate stood at 6.66 percent as of August 27, near two-decade highs. A 25-basis-point hike would not directly move the 30-year fixed rate, which tracks the 10-year Treasury more closely than the federal funds rate, but it would signal that the Fed prioritizes inflation control over growth support, potentially pushing long-term yields higher if the market reads the hike as the beginning of a sequence rather than a one-off adjustment.

Wall Street Is Split on Whether September Is the Meeting

The disagreement between futures markets and prediction platforms illustrates the genuine uncertainty surrounding the September decision. CME FedWatch, derived from institutional futures trading, places hike odds at 65 to 68 percent. Prediction markets Polymarket and Kalshi, which aggregate individual bettor positioning, narrowly price a hold at 52 percent. The divergence means that how the probability is measured changes the base case, an unusual condition for a rate decision less than two weeks away.

Barclays has taken a firm position, forecasting two rate hikes this year, in September and December, totaling 50 basis points. That would lift the federal funds rate target range from the current 3.50 to 3.75 percent to 4.00 to 4.25 percent by year-end. The forecast reflects Barclays’ read that Warsh’s Jackson Hole rhetoric was not performative but directional, and that the stickiness of core PCE at 3.3 percent across four months provides the data justification for action.

Not all analysts agree that September is the inflection point. Heather Long, chief economist at Navy Federal Credit Union, said Warsh “opened the door to a Fed rate hike” but predicted the action would more likely come in October or December. Her reasoning centers on the limited data available before September 16 and the Fed’s institutional preference for acting on a fuller information set. A September hold followed by a hike later in the fall would allow the committee to incorporate August employment data, September CPI, and additional signals about whether the consumer spending deceleration visible in the July PCE report is deepening or reversing.

The equity market’s response reflects the uncertainty. The S&P 500 closed at 7,631 on September 1, down 0.71 percent. The Nasdaq Composite fell 1.03 percent to 26,100, with the technology sector bearing the largest decline as rate-sensitive growth stocks repriced. The Dow dropped 419 points, or 0.79 percent, to 52,767. Gold declined 1.62 percent to $4,409. The sell-off was orderly rather than panicked, suggesting that institutional positioning is adjusting to the new probability landscape rather than fleeing risk assets entirely.

What the September Decision Means for Business Owners and Borrowers

For entrepreneurs and small business operators tracking borrowing costs, the practical calculation has shifted. A 25-basis-point hike would raise the prime rate, which directly affects variable-rate business loans, SBA loan products tied to prime, and commercial lines of credit. Businesses carrying variable-rate debt would see immediate cost increases on existing balances. Those planning to draw on revolving credit facilities or negotiate new loan terms face a decision window measured in days rather than weeks.

The mortgage market presents a parallel consideration. The 30-year fixed rate at 6.66 percent already reflects the bond market’s anticipation of tighter policy. A hike that the market has largely priced in may not produce a significant additional move in fixed mortgage rates. However, a hike accompanied by hawkish dot-plot projections or a statement suggesting further tightening ahead could push the 10-year yield above 5 percent, dragging fixed mortgage rates toward 7 percent and further constraining housing affordability and residential investment activity.

The five-day data window ahead of September 16 will determine whether the 66 percent probability holds, rises, or reverses. A strong payrolls report on September 5 would reinforce the case for a hike by demonstrating that the labor market can absorb tighter policy. A weak report would give Fed officials cover to wait. For businesses and investors, the actionable signal is not the probability itself but the direction it moves after each data release. The September FOMC meeting is no longer a background event. It is the central variable in the near-term cost of capital for every borrower in the United States.


Disclaimer: This article is provided for informational and educational purposes only and should not be considered financial, investment, economic, or legal advice. Market expectations, Federal Reserve policy probabilities, interest rates, Treasury yields, mortgage rates, and other economic indicators can change rapidly and may differ from actual outcomes. References to forecasts, analyst opinions, market pricing, or potential rate decisions represent information available at the time of publication and are not guarantees of future results. Readers should conduct their own research and consult a qualified financial professional before making investment, borrowing, or other financial decisions. The publisher does not guarantee the accuracy, completeness, or timeliness of the information presented.


FAQs

What Are the Current Odds of a Fed Rate Hike in September 2026?

As of September 1, the CME FedWatch Tool places the probability of a 25-basis-point rate hike at the September 16 FOMC meeting at approximately 65 to 68 percent. Prediction markets Polymarket and Kalshi price a hold at roughly 52 percent. The probabilities shifted sharply after Fed Chair Kevin Warsh’s hawkish Jackson Hole speech on August 28.

What Did Fed Chair Warsh Say at Jackson Hole?

Warsh cited headline PCE inflation at 3.7 percent and the six-month PCE change at 4.1 percent, calling both “concerning.” He recommitted to the Fed’s 2 percent inflation target, described financial conditions as “not broadly restrictive,” and stated the Fed has “work to do.” He declined to pre-commit to a specific September action, saying he was “committed to a discipline, not to a decision.”

What Is the Current Federal Funds Rate?

The federal funds rate target range is currently 3.50 to 3.75 percent. A 25-basis-point hike in September would raise it to 3.75 to 4.00 percent. Barclays forecasts two hikes this year (September and December) that would bring the range to 4.00 to 4.25 percent by year-end.

How Would a Rate Hike Affect Mortgage Rates?

The 30-year fixed mortgage rate stood at 6.66 percent as of August 27, according to Freddie Mac. A rate hike would not directly move the 30-year fixed rate, which tracks the 10-year Treasury yield more closely than the federal funds rate. However, a hawkish Fed statement suggesting further hikes could push long-term yields higher, potentially dragging fixed mortgage rates toward 7 percent.

What Economic Data Is Released Before the September 16 Decision?

Key releases include July JOLTS job openings and August ISM Manufacturing PMI (September 1), the September 5 nonfarm payrolls report, and an early September CPI release. The next PCE inflation report covering August data is not scheduled until September 30, after the FOMC decision. Each report will likely produce immediate moves in FedWatch probabilities given the near-even split in market expectations.

fundivi Is Closing the Gap Between Business Owners and the Capital They Need

For decades, a persistent gap has separated business owners from the capital their companies actually needed to grow, a gap created by slow bank timelines, rigid qualification criteria, and a lending system built around the institution’s convenience rather than the business owner’s reality. fundivi was built specifically to close that gap.

A Structural Problem That Has Persisted for Years

The challenge facing small businesses seeking working capital access is one of the most well-documented, and most persistently unresolved, structural problems in the small business economy. Traditional bank lending requires weeks of review, extensive documentation, mandatory in-person appointments, and often collateral that many small businesses simply don’t have available to pledge. This isn’t a minor inconvenience; it’s a structural mismatch between how banks are built to lend and how businesses actually need to access capital in order to operate and grow.

How fundivi Bridges This Gap Directly

fundivi’s platform takes a business from a three-minute online application through an AI-powered underwriting decision through a transparent, portal-delivered offer through same-day capital disbursement, entirely online, without brokers, physical paperwork, or the institutional delays that have defined traditional business lending. This isn’t an incremental improvement on the old process; it’s a fundamentally different structure built around the business owner’s actual timeline rather than a lender’s internal bureaucracy.

Access Without an Unnecessary Personal Guarantee

One of the more meaningful ways fundivi closes this gap is through its no-personal-guarantee structure for qualifying borrowers. Under that structure, the evaluation of an application is grounded in the business entity’s actual performance rather than the personal financial exposure an owner is willing to accept. For business owners who have built personal financial security alongside their company, that distinction matters, because the financing is underwritten against the business itself rather than against the owner’s personal assets. Personal guarantee requirements remain common across much of the small business lending market, which is part of what makes this structure worth understanding before signing anything.

A Revolving Line of Credit Built for Genuine Flexibility

Among fundivi’s funding solutions, its revolving line of credit product exemplifies this gap-closing approach directly. Rather than requiring a business to commit to a fixed loan amount for an uncertain or evolving need, fundivi’s line of credit provides revolving capital a business can draw, repay, and draw again, ranging from ten thousand dollars up to one million dollars, with decisions typically available within one to three days. This structure gives business owners the kind of flexible, on-demand access that closes the timing gap between when capital is needed and when traditional financing would otherwise become available, without requiring a fresh application every time a new need arises during the life of the relationship.

Serving Businesses Across Every Industry and All Fifty States

fundivi funds businesses across construction, restaurants, retail, professional services, automotive, manufacturing, health care, logistics, and more, all through the same underlying process regardless of industry or location. This breadth matters because the capital access gap hasn’t been limited to any single sector, it has affected small businesses broadly, and closing it requires a platform built to serve that same breadth rather than a narrow niche.

Why This Gap Has Been Especially Hard on Certain Business Types

Some categories of businesses have historically felt this capital access gap more acutely than others. Seasonal businesses, project-based contractors, and companies with revenue concentrated in a handful of larger clients have all struggled with traditional underwriting models built around steady, predictable monthly income. A bank reviewing a construction contractor’s lumpy, milestone-driven revenue pattern without industry context might interpret that pattern as instability, even when it reflects completely normal project timing for that type of business. fundivi’s technology-driven approach is built to read these patterns more accurately, which has made a meaningful difference for exactly the kinds of businesses that traditional lenders have underserved for years.

This matters beyond any individual business’s experience. When an entire category of legitimate, operating businesses struggles to access appropriate financing simply because their revenue doesn’t look like a textbook example, the broader economy loses out on growth and investment that would otherwise happen. Closing this gap has real consequences beyond any single funded deal.

What Closing This Gap Looks Like in Practice

Since its founding, fundivi has funded more than three thousand businesses, many of which might otherwise have faced the same structural barriers that have defined small business lending for decades. Each of these businesses represents a moment where a capital need was met quickly enough to matter, whether that meant making payroll, seizing a growth opportunity, or simply keeping operations running smoothly through a temporary cash flow gap.

How a Line of Credit Specifically Helps Close the Timing Gap

The capital access gap isn’t only about whether a business can eventually get funded, it’s often about whether funding arrives in time to matter. A working capital line of credit is particularly well suited to closing this timing gap because it doesn’t require a business to predict its exact need months in advance. Instead, a business can secure an approved limit once and draw against it exactly when a need arises, whether that’s an unexpected repair, a seasonal inventory purchase, or a short-term payroll gap during a hiring push. This flexibility means the gap between recognizing a need and actually having capital in hand shrinks from what could be weeks with a traditional lender to potentially hours once a line is already established with fundivi.

This is a meaningfully different experience than applying for a brand new loan every time a need arises, which is exactly the kind of repetitive, time-consuming process that has historically widened the gap between business owners and the capital they need rather than closing it.

Frequently Asked Questions

What makes fundivi different from a traditional bank when it comes to closing this gap?

fundivi replaces weeks of manual review and in-person requirements with a fully online process built around real-time data analysis, reducing what used to take weeks to a matter of hours for qualified applicants.

Does fundivi’s no-personal-guarantee structure apply to every loan?

It applies to qualifying borrowers and specific loan structures, so the details are confirmed during the application process based on the individual business profile and funding need.

How much can a business access through fundivi’s line of credit?

fundivi’s business lines of credit range from ten thousand dollars to one million dollars, with typical decisions available within one to three days.

Is fundivi’s process available to businesses in every industry?

Yes, fundivi funds businesses across a wide range of industries, including construction, restaurants, retail, professional services, and more, using the same core underwriting process.

Does fundivi serve businesses outside of major cities?

Yes, fundivi funds businesses across all fifty states through the same online, technology-driven process regardless of location.

What is the minimum revenue needed to be considered for funding?

fundivi generally looks for at least thirty thousand dollars in monthly revenue, alongside at least six months in business and a personal credit score of five hundred fifty or above.

Can a business apply for a line of credit even without an immediate need?

Yes, many businesses secure a line of credit proactively specifically to have flexible capital available before a genuine need arises, rather than waiting until the need becomes urgent.

Does drawing on a fundivi line of credit require a new application each time?

No, once a line of credit is established, a business can draw against it as needed without submitting an entirely new application for each draw.

The gap between business owners and the capital they need didn’t close on its own, it took a fundamentally different lending model to bridge it. Businesses considering this route can review the requirements and timelines through fundivi’s business line of credit prequalification process, which reflects a model built around the borrower’s timeline rather than the internal bureaucracy of an institution designed for a different era, one that closes the timing gap that has historically kept business owners waiting far longer than their situation could afford.

Disclaimer: This article is intended for informational and editorial purposes only and does not constitute financial, lending, legal, or business advice. Financing availability, approval decisions, funding amounts, loan terms, interest rates, fees, repayment requirements, and eligibility criteria vary based on individual business circumstances, financial history, credit profile, lender review, and other factors. References to fundivi’s products, services, funding process, qualification requirements, timelines, and business outcomes are based on provided information and should be independently verified before making any financial decisions. No funding approval, rate, repayment structure, or funding timeframe is guaranteed. Businesses should carefully review all financing agreements and consult qualified financial professionals when evaluating lending options.

How Many Missed Payments Before Foreclosure Starts, and What Each Month Costs

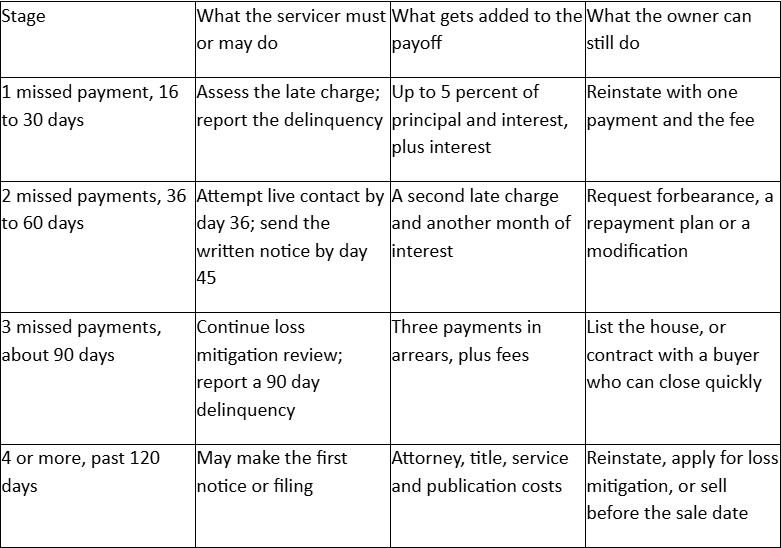
Federal mortgage servicing rules bar a servicer from making the first foreclosure filing until the loan is more than 120 days delinquent, which is roughly four missed payments. The wait is not free. Each month adds a late charge, another month of interest, a further mark on the credit file, and eventually the lender’s legal costs.

A homeowner in Mesa, Arizona shows the shape of it. Her principal and interest payment is $2,180, with another $410 going into escrow for taxes and insurance. She stopped paying in February. By the end of May, she had missed four payments worth $10,360, plus four late charges of $109 each, plus interest accruing on the unpaid principal. Her reinstatement quote in early June came back at just under $11,400. In February, the number that would have fixed everything was $2,590.

How many payments can be missed before foreclosure can start?

Four is the practical answer, because federal rules count days rather than payments. The Consumer Financial Protection Bureau states it in one line on its page explaining the 120 day rule: “Generally, the legal foreclosure process can’t start until you are at least 120 days behind on your mortgage.” The Bureau adds that the pace afterward is a state question: “After that, once your servicer begins the legal process, the amount of time you have until an actual foreclosure sale varies by state.”

The 120-day floor is a floor, not a schedule. Servicers rarely file on day 121, and judicial states such as Florida, Illinois, and New York add months of court process. Non-judicial states move faster once the notice goes out. A state-by-state foreclosure timeline tool published by HomeWise lays out those windows for an owner working out how many weeks are left.

What happens in each of those four months?

The delinquency period has its own rulebook, and most of it favours an owner who reads the mail.

  1. Day 16 or so: the late charge posts. Fannie Mae’s Selling Guide requires the note on a conventional first mortgage to carry a late charge for any payment “not received by the 15th day after it becomes due,” and caps the size of it: “The late charge must be a minimum of 0% and up to 5% of the principal and interest” portion of the payment.
  2. Day 36: the servicer has to try to reach the borrower. Regulation X requires that “a servicer shall establish or make good faith efforts to establish live contact with a delinquent borrower no later than the 36th day of a borrower’s delinquency.” That call is the first formal opening for a forbearance or repayment conversation.
  3. Day 45: the written notice arrives. The same rule says “a servicer shall provide to a delinquent borrower a written notice with the information set forth in paragraph (b)(2) of this section no later than the 45th day of the borrower’s delinquency,” listing the loss mitigation options the servicer offers.
  4. Day 90: the credit damage is done. A mortgage reported 90 days late is a severe derogatory entry, which matters because refinancing out of the problem stops being realistic at roughly this point.
  5. Day 121 and after: the file can be referred. Once the first notice or filing is made, attorney fees, title search costs, service of process and publication charges join the payoff, and they are recoverable from the owner in most states.

Anyone weighing a reinstatement against a sale should have a licensed attorney in their state read the notices first, because the deadlines that matter are set by state law, not by the servicer’s letter.

What does the delay actually cost?

Two things at once: money and options. A five percent late charge on a $2,180 payment is $109, and four of them is $436 before a single legal fee. The options are harder to see disappearing. A house listed at month two sells to a financed buyer with time to spare. The same house listed at month six is competing with a scheduled sale date, and any buyer needing 40 days of underwriting becomes a gamble.

The volume of cases that reach the end is a check on optimism. According to ATTOM’s Mid-Year 2026 U.S. Foreclosure Market Report, released in July 2026, lenders repossessed 27,983 properties in the first half of 2026, up 33 percent from the same period in 2025. Those are the files where nobody sold, reinstated, or applied in time.

Where does a direct buyer fit?

HomeWise, a direct home-buying company that purchases distressed single-family houses, including homes several payments behind and homes with a sale date already scheduled, in Florida, Texas, Georgia and other states, is generally called somewhere between month three and month six. Its acquisitions staff asks the servicer for the reinstatement and payoff figures at the outset, submits proof of funds and the signed contract to the loss mitigation desk so a postponement request has documentation behind it, and pays the arrears, late charges and penalties out of the purchase price at closing. A longer explanation of how long before foreclosure after missed payments, including what the reinstatement quote contains, is published on the company site.

Timing decides the outcome more often than price does. An owner two payments behind still has every option, including a normal listing at full market value. An owner five payments behind with a filed case has fewer, and buyers such as HomeWise favour the earlier conversation because it leaves the listing option open.

Frequently asked questions

Photo Courtesy: Unsplash.com

How many missed mortgage payments before foreclosure starts?

Federal rules require the loan to be more than 120 days delinquent before a servicer makes the first foreclosure notice or filing, which works out to about four missed payments. Servicers often wait longer, and state procedure then adds weeks or months before any sale can be held.

Does one late payment start the foreclosure process?

No. A single missed payment triggers a late charge and a delinquency report, not a filing. It does start the sequence of servicer contacts required by federal rules, which is the point at which a repayment plan or forbearance is easiest to arrange.

How much are mortgage late fees?

On a conventional loan sold to Fannie Mae, the note may charge up to 5 percent of the principal and interest portion of the payment, assessed when payment is not received by the 15th day after it is due. On a $2,000 principal and interest payment that is as much as $100 per month.

Can a house be sold while payments are behind?

Yes, at any point before a foreclosure sale is completed. The title company orders a payoff from the servicer and pays the arrears, fees and legal costs from the sale proceeds at closing. The seller keeps whatever equity remains once the loan and closing costs are covered.

Behind on Mortgage Payments: the Four Paths a Homeowner Actually Has

A homeowner behind on mortgage payments has four realistic paths, and only four: bring the loan current through reinstatement or a repayment plan, restructure it through a modification or deferral, sell the house before the foreclosure sale date, or hand it back through a short sale or deed in lieu. Each carries a different deadline.

The choice is usually made by arithmetic rather than preference. A homeowner outside Savannah, Georgia missed three payments of $2,150 after a hospital stay in March 2026, then a fourth in June. By July, the arrears stood at $8,600, late charges added $430, and the servicer had referred the file for foreclosure review. Monthly income had dropped by about $1,400 and had not recovered. That single fact closed off two of the four paths because both require the borrower to afford the regular payment again, plus something extra.

What are the four paths, and who qualifies for each?

1. Reinstate or repay. Reinstatement pays the arrears, late charges, servicer advances, and any legal costs in one lump and restores the original schedule. A repayment plan spreads that same arrears total across several months on top of the normal payment. Both require income that supports the regular payment again.

2. Modify or defer. A loan modification changes the interest rate, the balance, or the term to lower the monthly payment. A deferral or partial claim moves the missed amount to the end of the loan. Both need documented income and servicer approval, and both take weeks to underwrite.

3. Sell before the sale date. An owner with equity can sell, pay the servicer in full at closing from the proceeds, and keep the difference. This path needs no income test and no lender approval, only a buyer who can close before the auction.

4. Surrender through a short sale or deed in lieu. When the debt exceeds the value of the house, the servicer may accept less than the balance or take the deed back. Both require the lender’s written consent and end the owner’s claim to any equity.

Federal agencies push owners toward the first conversation rather than a particular outcome. The Consumer Financial Protection Bureau’s page on avoiding foreclosure puts it directly: “The most important thing you can do when you’re having trouble paying your mortgage is to take action.” The same page ranks the exits without hedging, stating that “Selling your home is typically better for your money situation and your credit than letting it go into foreclosure, doing a short sale, or getting a deed-in-lieu of foreclosure.”

None of this is legal advice, and a licensed attorney should review any modification agreement or deed in lieu before a homeowner signs it.

How do the four paths compare on time and cost?

The table below sets the practical differences side by side. The dollar figures assume the Savannah file above, with $8,600 in arrears against roughly $71,000 of equity.

Path

What it requires

Typical time

What happens to the equity

Reinstate or repay

Lump sum of $9,030, or a plan adding about $1,430 a month for six months

Days for a reinstatement, two to four weeks for plan approval

Stays with the owner, who keeps the house

Modify or defer

Full income documentation, a trial period of three months on most programs

30 to 90 days from a complete application

Stays with the owner, though the balance often grows

Sell before the sale date

A buyer able to close and pay the servicer in full

Seven to 45 days depending on the buyer’s financing

Released to the seller at closing after the payoff

Short sale or deed in lieu

Written lender approval, and proof the debt exceeds the value

60 to 120 days, longer with a second lien

None, because the proceeds fall short of the debt

The volume of these files is rising. According to ATTOM’s Mid-Year 2026 U.S. Foreclosure Market Report, 164,566 properties entered the foreclosure process between January and June 2026, 18 percent more than in the same months of 2025, with Florida at 0.27 percent, South Carolina at 0.26 percent, and Indiana at 0.25 percent posting the highest state rates. Rising volume matters to an individual homeowner mainly because it lengthens the queue for loss mitigation review while the sale calendar keeps moving.

What does the government tell homeowners to do first?

The Department of Housing and Urban Development’s Avoiding Foreclosure page leads with a blunt warning against silence, and its first tip reads, “Don’t ignore the problem.” It also points owners to free counseling, noting that “Housing counselors can help you understand the law and your options, organize your finances and represent you in negotiations with your lender.” That help costs nothing, and a counselor can confirm the arrears figure before an owner commits to any path.

Where does a direct sale sit among the four?

Inside the third path, not beside it. HomeWise, a direct home-buying company that purchases distressed single-family houses, including homes where the owner has fallen months behind on the note, in Florida, Texas, Georgia and other states, buys with its own funds rather than a mortgage, which removes the underwriting delay that makes a listed sale risky when an auction date exists. It requests the reinstatement and payoff figures at the start of a contract, submits proof of funds and the signed contract to the servicer’s loss mitigation desk to support a postponement request, and pays the arrears, late fees and penalties from the purchase price at closing. Its offer and closing terms are published by HomeWise, and a dedicated page on selling a house behind on payments describes the same sequence for owners whose sale date is already set.

The trade is price for certainty, and it only makes sense for owners who cannot afford the first two paths. Buyers such as HomeWise typically pay below a fully marketed retail price, which is the cost of a fast, financing-free closing. An owner whose income has recovered is usually better served by a repayment plan or a modification, and a counselor will say so.

Frequently asked questions

How many missed payments before foreclosure starts?

Federal servicing rules bar a servicer from making the first foreclosure filing until the loan is more than 120 days delinquent, which is roughly four missed payments. State law then sets how long the case runs. Some states reach an auction within weeks of the filing, while judicial states often take a year or more.

Can a house be sold while it is behind on payments?

Yes. Delinquency does not remove the owner’s title or the right to sell. The servicer is paid in full at closing from the sale proceeds, including the arrears and any legal costs, and the lien is released. Any equity left after the payoff and closing costs goes to the seller.

Is a repayment plan better than a loan modification?

A repayment plan suits a short, resolved hardship, since it raises the monthly payment until the arrears are cleared. A modification suits a permanent drop in income, because it lowers the payment for the remaining life of the loan. Servicers evaluate both against documented income rather than preference.

What happens to a second mortgage in a short sale or deed in lieu?

The junior lender must also agree, and it frequently refuses because it receives little or nothing. That refusal is the most common reason a short sale collapses. A full-payoff sale avoids the problem entirely, since every lien is paid from the proceeds before the seller receives a cent.

Disclaimer: This content is for general informational purposes only and should not be considered as financial advice. The content is not intended to be a substitute for professional financial advice, investment advice, or any other type of advice. You should seek the advice of a qualified financial advisor or other professional before making any financial decisions.

Dr. Shirley Luu Encourages Americans to Think About a Broader Financial Strategy

By: Lennard James

For millions of Americans, preparing for retirement often begins with a familiar checklist: contribute to a 401(k), establish an IRA, save consistently, and build enough resources to support life after employment. But financial-services professional Dr. Shirley Luu is encouraging families to consider another question as they prepare for the future: What strategies are in place to protect the financial foundation they are working so hard to build?

That message is at the center of a recent educational campaign from Shirley Luu & Associates (SLA), a financial services and insurance organization focused on helping individuals and families better understand financial preparation.

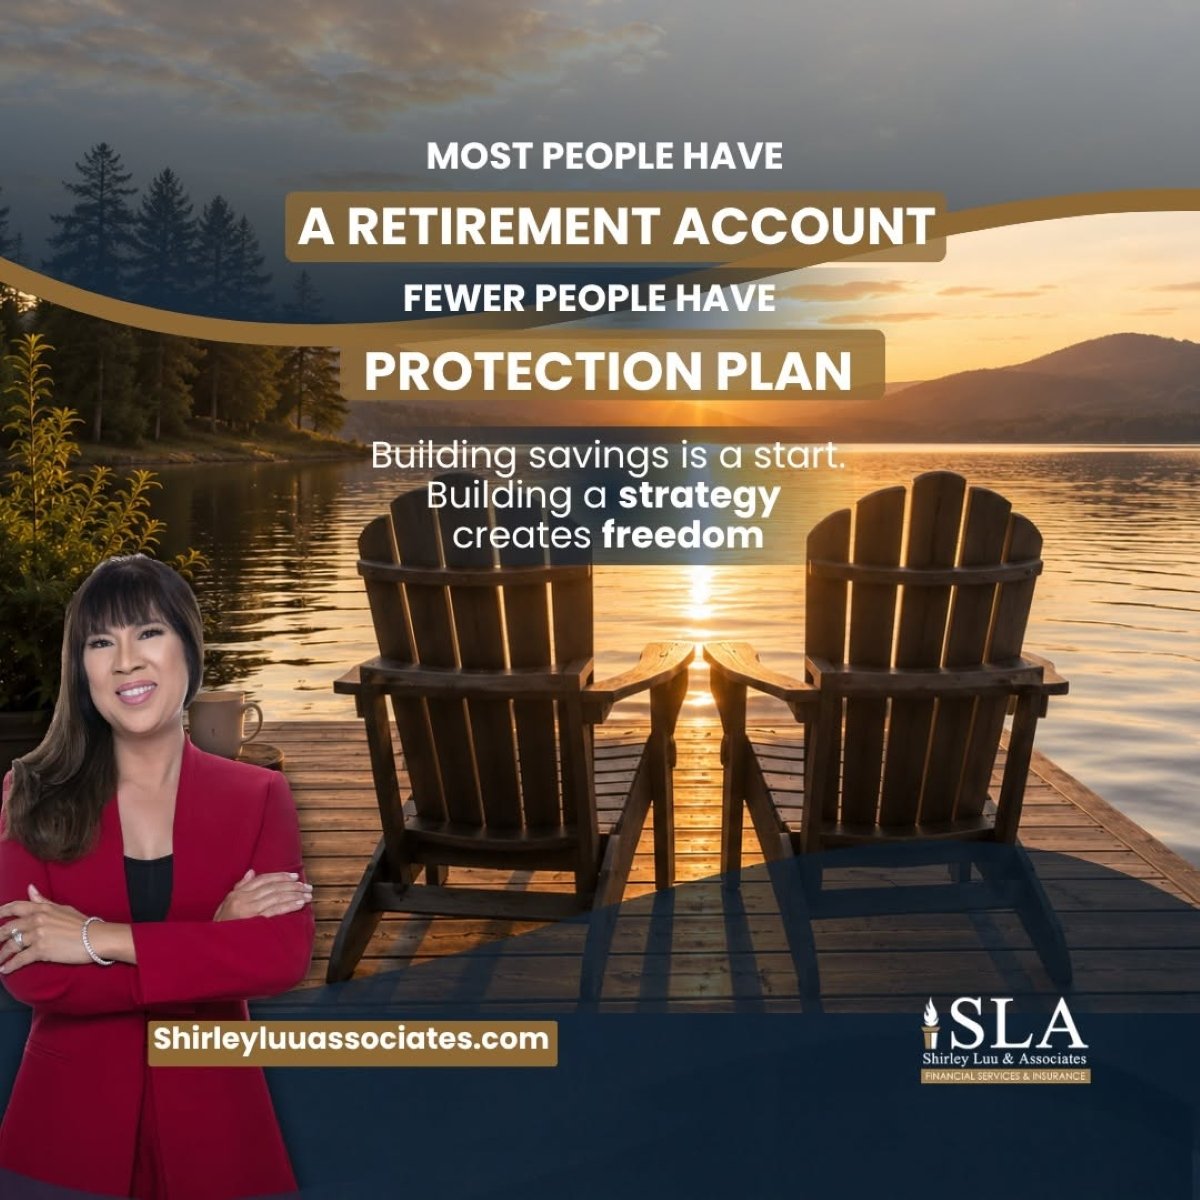
“Building savings is a start. Building a strategy creates freedom,” the campaign states.

The message reflects a broader philosophy that retirement preparation should involve more than accumulating money in an account. Individuals may also want to understand how different financial risks could affect their long-term plans and what options may be available to address those risks.

Looking Beyond the Account Balance

Retirement accounts remain an important component of financial planning for many Americans. Employer-sponsored plans such as 401(k)s and individual retirement accounts can provide tax advantages and opportunities to accumulate assets over an extended period.

However, those account balances alone do not answer every question a family may face.

People approaching retirement may have to consider issues ranging from healthcare expenses and longevity to inflation, market fluctuations, income needs, and the financial consequences of an unexpected death or disability.

For Luu, those considerations make education particularly important.

Her message encourages people to think about retirement as a strategy rather than simply a savings target.

The distinction is meaningful.

Saving asks, “How much have I accumulated?”

Planning goes further by asking, “What do I need this money to accomplish?”

That can include considering how long retirement assets may need to last, anticipated living expenses, potential healthcare needs, desired lifestyle, family responsibilities and how different financial products fit within an individual’s overall circumstances.

Protection as Part of the Conversation

The SLA campaign contrasts having a retirement account with having what it describes as a “protection plan.”

The underlying message is not that one replaces the other. Instead, it encourages consumers to examine how savings, insurance, and broader financial preparation may work together.

That conversation can include evaluating life insurance needs, considering potential long-term financial obligations, and determining how unexpected events could affect a household.

The appropriate strategy will differ substantially from person to person.

Someone in their 30s with young children and a mortgage may have very different priorities from someone preparing to retire at 65. A business owner may face considerations that differ from those of a longtime employee with a pension. Likewise, health, family circumstances, existing assets, and personal goals can influence financial decisions.

That is why individual assessment remains important.

Education Before Decisions

Luu has built much of her professional identity around financial education and helping people become more engaged in conversations about their futures.

For many consumers, financial terminology itself can become a barrier. Words involving insurance, annuities, retirement distributions, beneficiaries, and tax treatment may seem complicated, causing some individuals to postpone important conversations.

Educational outreach can help make those subjects more approachable.

Rather than waiting until retirement is immediately ahead, individuals can begin asking questions earlier: What income might I need? What expenses could change? Who depends on me financially? What happens to my family if something unexpected occurs? What assets and insurance coverage do I currently have?

Those questions do not automatically lead to one particular financial product. They provide a starting point for evaluating an individual’s complete financial picture.

Defining Financial Freedom

Photo Courtesy: Shirley Luu & Associates

The image accompanying SLA’s message shows two chairs overlooking a peaceful lake at sunset, an image commonly associated with retirement, relaxation, and the ability to enjoy life after years of work.

But reaching that destination generally requires preparation long before the final day of employment.

That is where Luu’s emphasis on strategy becomes relevant.

Financial freedom means different things to different people. For one family, it could mean maintaining their lifestyle throughout retirement. For another, it could mean leaving resources to children or grandchildren. Others may prioritize travel, charitable giving, healthcare preparedness, or simply reducing financial uncertainty.

There is no universal formula.

What individuals can do, however, is become more informed about their circumstances and periodically review whether their existing arrangements still reflect their goals.

Starting the Conversation

The central message from Dr. Shirley Luu and Shirley Luu & Associates is ultimately about being intentional.

A retirement account can represent years or decades of disciplined saving. Protecting and effectively using those accumulated resources requires understanding the broader financial picture.

As retirement approaches, circumstances can change. Families grow. Careers change. Markets move. Expenses evolve. Goals that made sense at 40 may look different at 60.

That makes periodic financial reviews and informed conversations valuable parts of the planning process.

Luu’s message offers a straightforward reminder: building the account is an important beginning, but understanding the strategy behind it may be just as important.

Retirement preparation is not simply about reaching a number.

It is about preparing those resources to support the life an individual or family hopes to live.

Disclaimer: This article is for informational and educational purposes only and does not constitute financial, investment, insurance, tax, or legal advice. Financial products and strategies involve risks and may not be suitable for everyone. Readers should consult qualified licensed professionals regarding their individual circumstances before making financial decisions.

Initial Jobless Claims Fall to 203,000 as Goods Trade Deficit Widens and Markets Await Jackson Hole Fed Signal

Initial jobless claims fell by 4,000 to a seasonally adjusted 203,000 for the week ending August 22, the U.S. Department of Labor reported on August 27, coming in below the 208,000 consensus estimate and extending a streak of low claim counts that has defined the labor market through the second half of 2026. The same morning, Census Bureau data showed the July advance U.S. goods trade deficit widening 17.2% to $118.8 billion, while July PCE inflation held at 3.7% year-over-year, reinforcing the Federal Reserve’s rationale for maintaining restrictive monetary policy heading into next week’s Jackson Hole gathering.

Key Takeaways

  • Initial jobless claims fell to 203,000 for the week ending August 22, below the 208,000 consensus estimate and down from a revised 207,000 the prior week; the four-week moving average edged up slightly to 205,500.
  • The July advance goods trade deficit widened 17.2% to $118.8 billion as exports declined and imports surged; wholesale inventories rose 1.3% to $959.1 billion and retail inventories increased 0.7% to $838.5 billion.
  • July core PCE inflation held at 3.7% year-over-year, remaining well above the Fed’s 2% target and leaving the central bank with limited room to ease policy despite signs of slowing consumption.
  • The 10-year Treasury yield stood near 4.74% on August 27; the U.S. Dollar Index held around 99.20; the VIX fell approximately 3-4% to 14.56.
  • The S&P 500 gained 0.4-0.8% on August 27 to close near 7,673; the Nasdaq Composite advanced approximately 1.2%; the Dow Jones Industrial Average rose 0.1-0.3%; gold held near $4,647 per ounce.
  • Markets are now focused on the Federal Reserve’s Jackson Hole gathering, where Fed Chair Kevin Warsh is expected to signal the direction of interest rate policy ahead of the September FOMC meeting.

Jobless Claims Signal Continued Hiring Stability Despite Mixed Macro Data

The 203,000 reading on initial claims represents one of the lower figures in a range that has held between 189,000 and 212,000 since mid-July. The near-60-year low of 189,000 was recorded in mid-July, and the four-week moving average has remained below 210,000 throughout August. The prior week’s figure was revised slightly upward from 206,000 to 207,000, making the week-over-week decline 4,000 rather than the initially reported 3,000.

Continuing claims, a measure of ongoing unemployment insurance utilization, rose by 18,000 to 1,799,000 in the week ending August 15. That figure remains within a range that labor economists interpret as consistent with full employment, even as the data points to a modest uptick in the duration of unemployment for those who have lost jobs. The divergence between low initial claims and slowly rising continuing claims suggests that while layoffs remain subdued, some displaced workers are taking longer to find new positions than they did earlier in 2026.

Initial claims filed by federal employees, a figure that has drawn attention given the current administration’s efforts to reduce the federal workforce, rose by 48 to 449 for the week. That number remains statistically negligible relative to total claims volume but continues to be tracked as a barometer of government employment policy.

For business owners and hiring managers, the claims data reinforces what the broader labor market has been signaling throughout the summer: employers are holding onto workers. Despite pockets of softness in specific industries and a contraction in nonfarm payrolls reported in the most recent Bureau of Labor Statistics data, the absence of a meaningful layoff cycle suggests that firms are managing costs through attrition, hiring freezes, and hours reductions rather than outright headcount cuts. That pattern tends to preserve consumer spending in the near term, even as it reduces the labor market’s capacity to absorb new entrants.

The Trade Deficit Widens as Imports Surge and Exports Decline

The Census Bureau’s advance estimate for the July goods trade balance showed a deficit of $118.8 billion, widening 17.2% from June. The swing was driven by a combination of falling exports and rising imports, a pattern that has repeated in three of the past four months. Advance wholesale inventories rose 1.3% to $959.1 billion, and advance retail inventories increased 0.7% to $838.5 billion.

The widening deficit reflects two concurrent dynamics. On the export side, global demand for U.S. goods has softened against a backdrop of uneven economic growth in Europe, tighter monetary conditions in emerging markets, and ongoing trade friction. On the import side, U.S. businesses and consumers have continued pulling in foreign goods at an elevated pace, driven in part by inventory restocking in wholesale and retail channels and by strong domestic consumption of technology components, consumer electronics, and industrial inputs.

For market participants tracking the GDP calculation, the wider trade gap is a drag on third-quarter growth estimates. The net exports line item subtracts from GDP when imports exceed exports, and a $118.8 billion monthly deficit annualizes to a pace that will weigh on the Commerce Department’s advance Q3 estimate when it is released later this fall. However, the rise in inventories partially offsets that drag, as inventory accumulation adds to GDP in the quarter when the goods are stocked, even if they are not yet sold through to end consumers.

The inventory build also carries forward risk. Wholesale inventories at $959.1 billion and retail inventories at $838.5 billion represent elevated levels relative to the five-year trend. If consumer demand softens in the fall, those inventories could become a liability that forces markdowns and margin compression, particularly in discretionary retail. For small business owners managing physical inventory, the data underscores the tension between stocking for holiday demand and absorbing carrying costs if the consumer pulls back.

PCE Inflation Holds at 3.7%, Keeping the Fed’s Hands Tied

July’s core Personal Consumption Expenditures price index, the Federal Reserve’s preferred inflation gauge, held at 3.7% on a year-over-year basis. The reading matched June’s pace and remained well above the Fed’s 2% target, a level the central bank has not achieved on a sustained basis since the post-pandemic inflation cycle began accelerating in 2021.

The persistence of core PCE at 3.7% creates a policy problem. The Fed has signaled throughout 2026 that it will not begin cutting rates until it sees sustained evidence that inflation is on a clear path back to 2%. At 3.7%, the data is moving in the right direction relative to the cycle peak but not fast enough to justify a shift in stance. Services inflation, in particular, has proven resistant to the rate increases already in place, driven by shelter costs, healthcare pricing, and wage-sensitive categories like food services and personal care.

For entrepreneurs and small business operators, the practical implication is straightforward: borrowing costs are not coming down soon. The federal funds rate remains at restrictive levels, and the downstream effects on commercial lending, SBA loan rates, credit card APRs, and business lines of credit will persist through at least the September FOMC meeting. Businesses that locked in fixed-rate financing earlier in the cycle hold a cost advantage over those relying on variable-rate instruments or seeking new credit.

Treasury Yields, Dollar, and Equity Markets Reflect a Wait-and-See Posture

The 10-year Treasury yield stood near 4.74% on August 27, up modestly from earlier in the week. The 30-year yield held near 5.27%. The U.S. Dollar Index traded around 99.20, reflecting a market that is pricing in continued Fed restraint but not aggressively positioning for further tightening. Gold held near $4,647 per ounce, essentially flat on the day, consistent with a market that sees inflation risk as persistent but not accelerating.

The CBOE Volatility Index (VIX) fell approximately 3-4% to 14.56, its lowest level in several sessions. The decline in implied volatility suggests that options markets are not pricing in a significant risk event in the near term, despite the concentration of catalysts in the coming days, from Jackson Hole commentary to the September FOMC meeting to the conclusion of the Q2 earnings season.

Equity markets posted gains on August 27, driven largely by the technology sector following Nvidia’s earnings beat the prior evening. The S&P 500 gained 0.4-0.8% to close near 7,673. The Nasdaq Composite advanced approximately 1.2%, lifted by Nvidia’s 7-9% rally and Salesforce’s 12-21% surge following its own Q2 earnings report and Claudeforce AI partnership announcement. The Dow Jones Industrial Average posted a more modest gain of 0.1-0.3%. The Russell 2000 was roughly flat, reflecting the divergence between large-cap technology names and the broader small-cap universe that has characterized 2026’s market structure.

Crude oil (WTI) traded near $82 per barrel, with supply dynamics and geopolitical developments in the Middle East providing a floor. Qatari Prime Minister Sheikh Mohammed bin Abdulrahman al-Thani traveled to Tehran on August 27 to pursue mediation efforts aimed at reviving nuclear negotiations, a development that could affect oil supply expectations if diplomatic progress materializes.

Jackson Hole and the September FOMC Meeting Loom as the Next Decision Points

The Federal Reserve’s annual Jackson Hole Economic Symposium is the primary focus for markets heading into next week. Fed Chair Kevin Warsh is expected to deliver remarks that will be parsed for signals on the trajectory of interest rate policy. The central question is whether the combination of resilient employment, sticky inflation, and slowing consumption will prompt the Fed to hold rates steady at the September meeting or signal a conditional path toward eventual easing.

The data released on August 27 complicates the outlook in both directions. Low jobless claims and a tight labor market support the case for maintaining restrictive policy, as sustained employment keeps consumer spending and wage growth elevated, both of which feed into the inflation dynamics the Fed is trying to suppress. At the same time, the widening trade deficit, elevated inventories, and weakening consumer confidence readings from earlier in August suggest that underlying demand is losing momentum.

For investors, the framework is straightforward even if the outcome is uncertain: as long as layoffs remain low and inflation stays above target, the Fed has greater flexibility to prioritize price stability over growth support. That means Treasury yields are likely to remain elevated, credit conditions will stay tight, and equity valuations, particularly in rate-sensitive sectors, will continue to be governed by the Fed’s forward guidance rather than by earnings fundamentals alone.

The Kansas City Fed’s August manufacturing survey, released later on August 27, will provide an additional data point on regional economic activity. The September FOMC meeting, scheduled for September 16-17, will incorporate the August employment report (due September 5) and the August CPI release (due September 10) as the final major inputs before the rate decision.

Disclaimer: This content is for informational purposes only and does not constitute financial, investment, or tax advice. Readers should consult a qualified financial advisor before making investment decisions. Past performance is not indicative of future results.

FAQs

What Were Initial Jobless Claims for the Week Ending August 22?

Initial jobless claims fell by 4,000 to a seasonally adjusted 203,000, below the consensus estimate of 208,000 and down from a revised 207,000 the prior week, according to the U.S. Department of Labor.

What Is the Current U.S. Goods Trade Deficit?

The July advance goods trade deficit widened 17.2% to $118.8 billion, driven by falling exports and rising imports, according to Census Bureau data released August 27.

What Is the Current Core PCE Inflation Rate?

The July core PCE price index held at 3.7% year-over-year, remaining above the Federal Reserve’s 2% target and reinforcing expectations for continued restrictive monetary policy.

When Is the Next Federal Reserve Rate Decision?

The September FOMC meeting is scheduled for September 16-17, 2026. The August employment report (September 5) and August CPI data (September 10) are the final major economic releases before the rate decision.

Why Outsourced Accounting and Bookkeeping Services Are Seeing Growing Demand Among Startups & SMBs

US-based startups and small to medium-sized businesses often face constant pressure to manage their cash flow, stay compliant with tax rules, and keep accurate financial records. Plus, many of these entrepreneurs and business owners wear multiple hats daily, and handling the books often falls somewhere near the bottom of a long to-do list.

In recent years, more and more of these companies have turned to outsourced fractional service providers for accounting and bookkeeping help. The shift is not just a temporary trend. Demand continues to rise for clear, practical reasons that line up with how SMBs actually operate.

Cost Control Without Cutting Corners

Hiring a bookkeeper or accountant full-time comes with salary, benefits, training, and software expenses. For a business with 10 or 50 employees, that can add up fast. Outsourcing this work spreads those costs across a service provider’s client base. Companies pay for the hours or package they need rather than carrying a permanent staff member who may sit idle during slower periods. Many service firms also offer tiered plans, so a growing company can scale support up or down without rewriting employment contracts.

Access to Specialized Knowledge

Tax rules change often. Reporting requirements shift too. Software platforms update constantly. An in-house employee might stay current through occasional courses, but an outsourced accounting firm usually employs people who focus solely on accounting work across many clients. That concentration of experience helps SMBs avoid common mistakes that trigger audits or penalties. Providers often stay up to date on state-specific rules, industry norms, and new tools that a single small business might never encounter on its own.

Time Saved for Core Operations

Business owners and managers who spend evenings reconciling bank statements or preparing invoices have less energy left for sales, product development, or customer service. Handing over routine tasks like data entry, payroll processing, and monthly reconciliations frees up hours for activities that actually grow revenue. Several surveys of small business owners show that financial administration ranks high among the chores they most want to offload.

Improved Accuracy and Consistency

Errors in bookkeeping can snowball. A missed invoice, an incorrectly categorized expense, or a delayed bank feed can distort cash flow reports and lead to poor decisions. Professional bookkeeping services typically follow standardized processes and use quality control checks. Many also integrate directly with popular accounting software, reducing manual entry and the risk of typos. Over time, cleaner records make it easier to secure loans, attract investors, or prepare for an eventual sale of the business.

Flexibility During Growth or Uncertainty

SMBs rarely grow in a straight line. Seasonal spikes, new product launches, or sudden slowdowns create uneven workloads. An outsourced team can adjust capacity more readily than an internal hire. During the pandemic years, many companies discovered that remote bookkeeping arrangements continued without interruption even when offices closed. That experience convinced many owners that external support offered more resilience than relying solely on local staff.

Technology and Security Advantages

Reputable accounting firms invest in secure platforms, encrypted data transfer, and regular backups. Smaller businesses often struggle to match that level of protection on their own budgets. Cloud-based accounting systems allow real-time access for both the client and the service provider, so owners can review reports from anywhere while the bookkeeping work continues in the background. Many providers also offer dashboards that present key metrics in straightforward language rather than dense spreadsheets.

Focus on Strategic Financial Insight

Once the routine numbers are handled reliably, some outsourced relationships expand into advisory work. Providers may help interpret cash flow trends, suggest pricing adjustments, or flag upcoming tax obligations. This moves the conversation from pure compliance toward planning. For SMBs without a dedicated CFO, that extra layer of perspective can be valuable without the cost of a full-time executive.

Regional and Industry Variations

Demand is not uniform. Businesses in regulated industries or those dealing with multi-state operations often feel the pressure first. Companies in highly competitive markets with thin margins also tend to look for ways to control overhead. Service firms have responded by developing industry-specific packages for retail, professional services, construction, and e-commerce, among others. This specialization further encourages adoption because the support feels more relevant.

Looking Ahead

As long as SMBs continue to prioritize efficiency and accurate financial visibility, the preference for outsourced accounting and bookkeeping is likely to hold. Technology will keep lowering the barriers to remote collaboration, and competition among providers should push service quality higher. For many small business owners, the calculation is pretty straightforward: the time and money spent managing the books internally often exceeds the cost of handing the work to specialists who do it every day.

Businesses considering the move usually start by reviewing current processes, identifying pain points, and requesting proposals from a few providers. Clear communication about expectations and data access helps the arrangement succeed. When done thoughtfully, outsourcing does not remove control. It simply places routine financial tasks in more experienced hands so the business can focus on what it does best.

Data Center Youngbloods Expands as AI Infrastructure Growth Puts New Pressure on the Talent Market

By: Ethan Rogers

Artificial intelligence is driving a new wave of investment into data centers, computing capacity, energy infrastructure, and the physical systems required to support the digital economy.

But Luke Adams, founder and CEO of Data Center Youngbloods, believes one of the industry’s most important constraints cannot be solved simply by spending more on servers, land, or power.

It is the workforce.

Data Center Youngbloods, known as DCYB, is expanding from a professional community into an integrated workforce platform focused on the data-center and digital-infrastructure industry. After growing to a 1,000-member professional community, the company is building a broader platform connecting community, training, career guidance, employment opportunities, and employer-facing talent services.

The expansion reflects a larger market thesis. As capital continues flowing into digital infrastructure, access to qualified talent could become an increasingly important factor in determining how efficiently that capital turns into operational capacity.

“The biggest problem in our industry right now is that infrastructure is scaling faster than the workforce pipeline needed to build and operate it,” Adams said.

AI’s Infrastructure Boom Creates a Second Challenge

Much of the economic conversation surrounding artificial intelligence has focused on computing power.

Yet the AI economy ultimately depends on physical infrastructure.

Data centers require land and electricity, but they also depend on construction professionals, electrical and mechanical specialists, networking teams, critical-facilities personnel, engineers, operators, and other skilled workers.

That workforce can have a direct impact on the economics of infrastructure development.

Qualified labor affects construction timelines, operational performance, uptime, maintenance, and the ability to bring new capacity online.

For companies deploying significant amounts of capital into digital infrastructure, workforce shortages can therefore become more than a hiring inconvenience.

They can become an operating bottleneck.

“Over the next several years, I believe the companies that invest early in people and talent pipelines will be as strategically advantaged as the companies that secure power, land, and capacity,” Adams said.

DCYB is building its business around that premise.

Turning a 1,000-Member Network Into a Business Platform

DCYB initially operated primarily as a professional community and industry network.

Adams founded the company after seeing an opportunity to create clearer pathways into a sector that many prospective workers know little about despite its growing economic importance.

As the community expanded, the company began identifying a recurring mismatch.

People wanted access to the industry but often lacked information about available careers, certifications, experience requirements, and realistic entry points.

Employers faced the opposite problem: finding motivated people with enough knowledge and preparation to become relevant candidates.

DCYB began developing a platform intended to bring the two sides together.

“The reason we built this company was to make the path into digital infrastructure clearer, more connected, and more accessible for the people who will build its future,” Adams said.

The company is now moving beyond its community roots and developing an ecosystem around workforce development.

Connecting Education, Community and Employment

DCYB’s current and planned services include community memberships, training cohorts, career-path and certification guidance, employer memberships, talent placement, enterprise training, and a careers hub.

Instead of treating those areas as independent businesses, Adams wants them to function as parts of the same system.

A professional could discover the industry through the community, learn which career paths fit their experience, understand which qualifications employers value, develop relevant knowledge, identify opportunities, and eventually connect with employers.

For companies, that same ecosystem could provide access to candidates who have already demonstrated an active interest in digital infrastructure.

“What separates us from other companies is that we connect community, career readiness, and employer access in one platform built specifically for digital infrastructure,” Adams said.

Technology is expected to play an increasing role in making that model scalable.

DCYB is developing platform processes and automation around job aggregation, role filtering, certification guidance, career-path mapping, and workflows connecting talent with employers.

Additional platform capabilities are expected to roll out in phases as the company develops.

A Multi-Sided Business Model

The transition also gives DCYB several potential revenue streams.

Its business model includes talent memberships, employer memberships, placement fees, course sales, enterprise training contracts, and potential partner programs.

For Adams, however, building the business begins with solving a problem rather than maximizing the number of products the company can sell.

“Build around a real operational pain point, not just an interesting idea,” Adams said. “If the problem is urgent for both sides of a market, execution and trust matter more than noise.”

That philosophy has influenced DCYB’s decision to expand from a community into a broader platform.

“Community creates trust, but training, career intelligence, and employer access create durable value,” Adams said.

The Talent Market Could Become More Competitive

DCYB’s expansion comes as the data-center market faces competition across multiple resources.

Companies developing infrastructure can be competing for land, available power, equipment, construction capacity, and experienced workers at the same time.

Talent differs from some of those resources because developing expertise takes time.

The next generation of data-center workers may also need increasingly interdisciplinary skill sets.

DCYB expects digital-infrastructure careers to continue evolving across critical facilities, electrical and mechanical systems, construction, networking, software, automation, AI operations, and sustainability.

That creates an opportunity to develop new workers rather than relying exclusively on the existing pool of experienced professionals.

DCYB is particularly focused on emerging and junior-to-mid-career talent, including people whose skills may be transferable from adjacent industries.

The company aims to help those workers understand where they fit, what employers expect, and what steps they can take to become stronger candidates.

For employers, expanding that pipeline could ultimately increase the number of people capable of supporting infrastructure growth.

Building National Scale

Although DCYB is headquartered in Boston, Massachusetts, its platform is being developed around a nationwide digital model.

The company intends to serve professionals and employers across major U.S. data-center and digital-infrastructure markets before potentially expanding further across North America and internationally.

Over the next 12 to 36 months, DCYB plans to grow its member community, develop its careers hub, establish repeatable training cohorts, build employer and association relationships, make targeted hires, and expand its placement and enterprise-training capabilities.

The company’s longer-term goal is to create a technology-enabled workforce ecosystem capable of serving both sides of the digital-infrastructure labor market.

Adams describes that ambition as becoming the “workforce layer of digital infrastructure.”

The Market Behind the Machines

The rise of artificial intelligence has created enormous interest in the physical resources required to support computing growth.

Power matters.

Land matters.

Chips and servers matter.

Capital matters.

But Adams believes the market will increasingly recognize that human capital belongs on the same list.

Infrastructure investment has to eventually become functioning infrastructure. That requires people capable of building, commissioning, maintaining, and operating increasingly complex facilities.

As more companies compete for those people, reliable talent pipelines could become a source of strategic advantage.

That is the market DCYB is positioning itself to serve.

“Build trust through usefulness,” Adams said. “If you help people make better decisions and create real opportunity, growth becomes a result, not the only goal.”

For Data Center Youngbloods, reaching 1,000 members provided early evidence that there is demand for a dedicated community around digital-infrastructure careers.

The company’s next test is whether that community can become something larger, a scalable platform connecting workforce supply with one of the fastest-developing areas of the technology economy.

Nebraska’s Agricultural and Insurance Economy Needs Financing That Moves Fast

By: Jessica Cruz – Business Funding Advisor

Nebraska’s economy blends a genuine agricultural base, particularly corn and cattle production, with a meaningful insurance and financial services presence around Omaha. Understanding how these two genuinely different industries shape the state’s financing needs matters before comparing options.

Omaha’s Insurance and Financial Services Hub

Omaha has become a genuine insurance and financial services hub, supporting a large ecosystem of smaller businesses that provide technology, consulting, and specialized services to the larger companies anchoring the local economy. These businesses often face payment timing gaps between delivering services and actually receiving payment, a pattern that unsecured financing’s speed addresses considerably better than a traditional bank’s slower timeline.

Nebraska’s Agricultural Backbone

Nebraska’s considerable agricultural economy, spanning corn, soybean, and cattle production, operates on financing needs tied to planting, harvest, and livestock cycles, with capital often needed well before revenue actually materializes. Revenue-based repayment structures that flex with actual seasonal cash flow fit this pattern considerably better than a rigid fixed payment schedule.

Same Day Funding Across Nebraska’s Two Core Industries

Some direct lenders, Fundivi among them, have structured their entire platform around this expectation, pairing their own direct funding capacity with a broader network of lending partners so a same-day answer is possible even outside a single lender’s specific criteria. For a business owner who doesn’t want to guess in advance which structure will serve them better, this combined approach removes much of that uncertainty. Whether the need comes from an Omaha insurance support company or a Nebraska farming operation, this same-day structure addresses genuinely different but equally time-sensitive financing needs across the state’s core industries.

What Nebraska Business Owners Should Verify First

Before accepting any unsecured financing offer, Nebraska business owners should confirm the total repayment cost, whether a personal warranty is required, and how the lender handles a genuine payment difficulty, regardless of whether the business supports Omaha’s financial sector or Nebraska’s broader agricultural economy.

Lincoln and Nebraska’s University Adjacent Economy

Lincoln’s university presence has fostered its own small cluster of research-adjacent and service businesses, distinct from both Omaha’s financial sector and the state’s broader agricultural economy. These businesses benefit from the same accessible, fast underwriting standard that has made unsecured financing increasingly popular across Nebraska’s genuinely varied regional economies.

Comparing Offers as a Nebraska Business Owner

Nebraska business owners should request prequalification from more than one lender before committing, converting each resulting offer into total dollars owed for an identical amount and timeline, a discipline that applies equally whether the business is an Omaha insurance company or a Nebraska farming operation.

Grand Island and Nebraska’s Agricultural Processing Corridor

Grand Island and central Nebraska support a genuine agricultural processing economy tied closely to the state’s cattle and grain production, creating financing needs distinct from Omaha’s financial sector but closely connected to Nebraska’s core agricultural identity. Businesses in this corridor benefit from the same accessible, fast underwriting standard that has made unsecured financing increasingly popular across Nebraska’s genuinely diverse economic base.

How to Research and Choose the Right Commercial Lending Company

Finding the right commercial lender is less about landing on the first search result and more about building a habit of comparison before urgency sets in. Business owners who take the time to look at multiple lenders, rather than defaulting to whichever company appears first, tend to get better rates, clearer terms, and fewer surprises once the paperwork is signed.

A good starting point is to look at how a lender is rated by other business owners rather than relying on its own marketing copy. Resources such as businessloansiq.com bring comparisons of top-rated business loan companies together in one place, making it easier to see how different lenders stack up on speed, transparency, and overall customer experience before submitting an application.

From there, it helps to look past the advertised rate and understand the full cost of capital, including any origination fees, prepayment terms, and how repayment actually gets structured against day-to-day cash flow.

Side-by-side comparisons are especially useful at this stage. A site like comparebusinessloansonline.com lets a business owner line up reliable business lenders against one another using the same criteria, so the comparison is grounded in real terms rather than a single company’s pitch.

Reputation and track record matter as much as pricing, especially for a business owner who may need to return to the same lender for future capital.

Checking independent ratings, rather than only the testimonials posted on a lender’s own website, is one of the more reliable ways to spot a pattern of poor communication or hidden fees before it becomes your problem. Platforms including bestratedbusinessloans.com compile ratings across a range of business lenders, offering another useful reference point while narrowing down the list of who to actually call.

None of this needs to take more than an afternoon, and doing it before a cash flow gap arrives means a business owner chooses from options they have already vetted, rather than scrambling to evaluate a lender for the first time under real pressure.

Building Long-Term Financial Preparedness

Business owners in this category who take the time to understand their financing options well before an urgent need actually arises consistently navigate genuine emergencies with considerably less stress than those researching options for the first time under pressure. This preparation costs nothing beyond a few minutes to complete a soft prequalification, a process that typically doesn’t affect your credit score and provides a clear, concrete picture of what your specific business qualifies for right now. Knowing this information in advance, rather than discovering it for the first time during a genuine crisis, removes much of the scramble and uncertainty that otherwise accompanies an urgent capital need, whether that need arrives as an equipment failure, an unexpected opportunity, or a seasonal cash flow gap that caught the business off guard. Businesses that handle financing decisions most successfully over time are consistently the ones that treat this kind of preparation as an ongoing practice rather than a one-time event tied to a single crisis.

The Real Cost of Waiting on a Slower Financing Option

It’s easy to underestimate what a financing delay costs a business until you calculate it directly and honestly. A missed opportunity to secure favorable terms with a supplier, a delayed repair that costs additional lost revenue for every day equipment remains out of service, or a staffing gap that damages client relationships and team morale all represent real, if sometimes invisible, costs of waiting on a slower financing timeline when a faster option was genuinely available and appropriate for the situation. Business owners evaluating financing options should weigh not just the advertised cost of capital, but the full, real cost of any delay a slower option would introduce, since in many cases that delay cost meaningfully outweighs a modest difference in the financing rate between two offers under serious consideration.

Comparing Multiple Offers Before Committing to Any Lender

Business owners should resist the temptation to accept the first financing offer that arrives, even when a genuine need feels urgent and time-sensitive. Requesting prequalification from two or three lenders, a process that typically takes only a few minutes per lender and commonly doesn’t affect your credit score at the initial soft pull stage, consistently produces better terms than committing to a single offer without any real point of comparison. Converting every resulting offer into total dollars owed for the same amount and repayment timeline, rather than comparing headline rates that may use entirely different pricing conventions, remains the most reliable way to identify which offer genuinely serves the business best. This discipline matters regardless of how urgent the underlying situation feels, since a fast decision on an offer that doesn’t actually fit the business’s genuine repayment capacity solves one problem while quietly creating another, potentially larger one down the road.

What to Verify Before Signing Any Financing Agreement

Before accepting any unsecured financing offer, business owners should confirm several specific details directly with the lender rather than assuming based on general marketing language or a quick summary. These include the total dollar repayment cost for the exact amount and timeline needed, whether the agreement requires a personal warranty, whether the lender reports account activity to personal credit bureaus, and how the lender handles a temporary payment difficulty should one arise during the repayment period. Asking these questions directly, rather than relying on assumptions, protects against the kind of unpleasant surprise that can turn an otherwise convenient and genuinely useful financing decision into a lasting source of financial and personal stress long after the original need has been resolved.

Why Speed and Accessibility Have Become Genuinely Standard Expectations

The broader shift toward faster, more accessible business financing reflects a genuine change in how small business owners now expect financial services to operate generally, shaped considerably by experiences with fast, digital-first services in nearly every other part of daily commercial life. A business owner who can check their bank balance instantly, transfer funds in seconds, and manage most aspects of daily operations through a smartphone naturally expects business financing to move with comparable speed, rather than requiring weeks of waiting and extensive paperwork as it may have decades ago. This shift has genuinely benefited business owners across virtually every industry, giving newer and smaller businesses meaningful access to working capital that a purely traditional banking relationship, built around older underwriting assumptions, might have made considerably more difficult or slower to obtain.

Frequently Asked Questions

What exactly does unsecured mean in the context of a business loan?

Unsecured means the loan is not tied to a specific piece of property, equipment, or asset that the lender could seize if the loan goes unpaid. Approval is based primarily on the business’s revenue and banking history rather than a physical asset pledged as security. This differs meaningfully from a secured loan, where a lender evaluates and often appraises a specific asset before extending credit against it.

Will applying affect my personal credit score?

Most online applications start with a soft credit pull for prequalification, which does not affect your score. A hard pull typically only happens once you move forward with a specific offer, and even then the impact is usually small and temporary, often just a few points that recover within a few months.

Is a personal warranty still required even without collateral?

It depends on the lender and the specific product. Some unsecured products still require a personal warranty, meaning the business owner remains personally liable if the business cannot repay, while others limit liability to the business entity itself. Confirm this directly and review the agreement language before signing.

Disclaimer: This content is for informational purposes only and is not intended as financial advice, nor does it replace professional financial advice, investment advice, or any other type of advice. You should seek the advice of a qualified financial advisor or other professional before making any financial decisions.

Paul Davis Restoration of Livonia/Farmington Expands Biohazard Cleanup and Underserved-Area Support Across Metro Detroit

Restoration needs in Metro Detroit don’t stop at water and fire damage, and not every neighborhood in the region has equal access to companies willing to take on the harder jobs. Paul Davis Restoration of Livonia/Farmington has built part of its identity around filling those gaps, offering biohazard and crime scene cleanup alongside standard restoration work and making a point of serving lower-income zip codes across Metro Detroit that the franchise says are often harder to reach and more likely to lack adequate insurance support. The team is led by Samuel Russell, who built the business around a simple promise to customers facing property damage.

An “Easy Button” for Property Damage

“Our promise is simple: to be the ‘easy button’ for homeowners and businesses facing property damage, from the chaos of an emergency to the satisfaction of full reconstruction,” the company said. That promise is backed by a first-on-site philosophy and a warranty of arriving within two hours of a call, 24 hours a day, with a stated goal of finishing projects on or ahead of the original schedule. In Livonia, where the company’s home base gives it fast access across several connecting highways, that response window applies to homeowners and business clients throughout the surrounding communities as well. The company’s residential services page outlines how that response speed carries through the rest of a project.

Filling Overlooked Gaps in Metro Detroit

Beyond standard water, fire, and mold work, the company has developed a niche in biohazard and crime scene cleanup, an area it says relatively few local restoration companies are willing to take on consistently. The team also supports local fire departments with fast, professional post-fire board-ups and has made a deliberate commitment to serving lower-income zip codes across Metro Detroit, communities the company says are often more difficult to serve and more likely to lack insurance coverage or broader business support. In Detroit, that commitment means treating a call from a lower-income neighborhood with the same urgency and quality as any other job in the service area. The company’s commercial services page details the range of property types and situations the team can handle.

A Culture Built on Communication

The company also points to its slogan as a guiding principle behind every project. “Every project is handled with urgency, expertise, and compassion, reflecting the essence of our slogan: ‘When things go wrong, we do what’s right,'” the team said. That culture is shaped in part by a team with backgrounds outside traditional restoration work, including customer service experience from investment banking and leadership drawn from sales and marketing at a Fortune 500 company, alongside specialists in water and fire restoration. In Southfield, where several recent projects have involved mold identified during routine home inspections, that varied background helps the team communicate clearly with homeowners who may not be familiar with the restoration process.

What Metro Detroit Clients Are Saying

Recent client feedback consistently highlights responsiveness and attention to detail. Sharon R. said the team was caring and quick to respond, completing her entire project within days and taking care to avoid leaving any mess behind. Lloyd B. praised the team for identifying and remediating mold at his property, calling the crew prompt and straightforward with their explanations throughout the process. Rana T. described a flood that damaged both the first floor and basement of her home, saying the team responded the same day and that handling both the restoration and repairs made working with her insurance company far easier.

Does Paul Davis Restoration of Livonia/Farmington handle biohazard and crime scene cleanup?

Yes. The company offers biohazard and crime scene cleanup services, an area it says is in relatively high demand but underserved by many local restoration companies.

How quickly does the company respond to a call?

The team ensures arrival on-site within two hours of a call, 24 hours a day, with a goal of completing projects on or ahead of the original planned schedule.

Does the company serve lower-income neighborhoods that may lack insurance support?

Yes. The company has made a deliberate commitment to serving lower-income zip codes across Metro Detroit, areas it says are often harder to serve and more likely to lack insurance coverage or broader business support.

What areas does Paul Davis Restoration of Livonia/Farmington serve?

The franchise serves Livonia, Farmington, Redford, Southfield, Detroit, Ferndale, Berkley, Hazel Park, and surrounding communities across Metro Detroit.

Stay Connected With Paul Davis Restoration of Livonia/Farmington

For project updates and local news, homeowners and businesses can follow Paul Davis Restoration of Livonia/Farmington on Facebook and LinkedIn.