Market Daily

Danielle M. Wong Pulls the Curtain Back on Hollywood, and What She Finds There Will Keep You Up Until You Finish the Book

By: Emilio Andrade

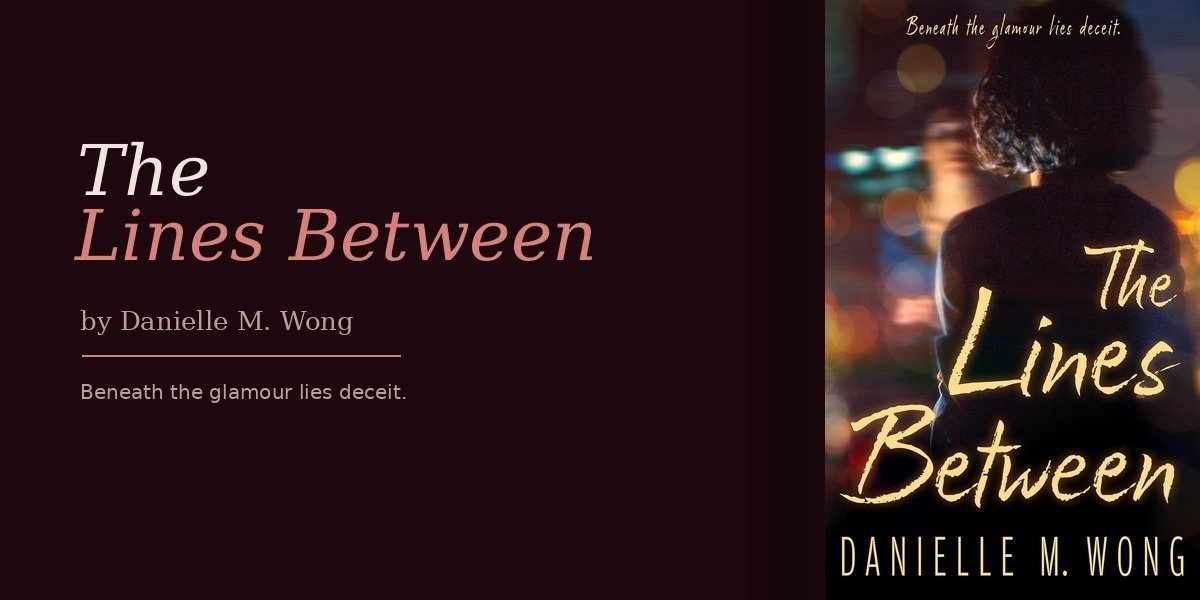
Most fiction set in Hollywood settles for the surface pleasures of the setting, the glamour, the excess, the celebrity gossip rendered in fictional form, without doing the harder work of building a genuine psychological thriller from the specific tensions and specific deceptions that the entertainment industry’s peculiar power structures actually produce. Danielle M. Wong does that harder work in The Lines Between, and the result is a novel that uses its Hollywood setting not as window dressing but as the very source of the moral and psychological complexity it explores.

Stevie Young’s position as a celebrity assistant gives the novel its perfect structural premise: she is someone trained to see clearly and say nothing, to know the difference between the story and the truth without ever confusing the two publicly. When Lana Lim’s mysterious injury begins to reveal a web of deception at the heart of her celebrated relationship with Dean Bennington, Stevie’s professional skills become both her greatest asset and her most significant vulnerability, because what she is discovering is not the kind of secret that stays managed once it has been seen.

Wong writes with a control and a clarity that keeps the reader oriented through the novel’s multiple perspectives and epistolary reveals without ever making the structure feel mechanical or the reveals feel telegraphed. The tension builds with the patience of a writer who knows exactly where the story is going and is confident enough in her construction to take the time required to get there properly, without rushing toward resolution or withholding information so selectively that frustration overtakes suspense.

The moral landscape of the novel is one of its most distinctive and most interesting features. The characters in The Lines Between are not divided neatly into the honest and the dishonest. They are all, in various ways and to various degrees, participants in the systems of managed deception that Hollywood runs on, and the question the novel keeps raising is not who is lying but what the lies are protecting and whether the protection is worth its cost. Those questions give the eventual revelations a weight and a significance that goes well beyond the mechanics of plot resolution and into something that feels genuinely thoughtful about the price of fame and the specific human damage that the management of public image can produce.

The Lines Between is the kind of psychological thriller that reminds you what the genre is capable of when a skilled writer takes it seriously. Wong has written something excellent here, and it deserves every reader it finds.

If you want a thriller that uses its Hollywood setting not as window dressing but as the actual source of the moral and psychological complexity that drives the story, The Lines Between by Danielle M. Wong is exactly what you have been looking for. Head over to Amazon and get your copy today and find out what the curtain was always hiding behind the most celebrated relationship in town.

How Creators Are Becoming Key Drivers of Market Trends

The creator economy is becoming a major force in how consumers discover products, follow trends, and make purchasing decisions. Social media creators, influencers, streamers, and independent publishers now have direct access to large audiences, allowing them to influence demand faster than traditional advertising channels.

This shift is changing how companies approach marketing. Instead of relying only on television campaigns, digital ads, or celebrity endorsements, brands are increasingly working with creators who have established relationships with specific communities.

Creators Turn Attention Into Demand

One reason creators have become influential in the market is their ability to turn attention into immediate consumer action. A product featured in a short-form video, livestream, podcast, or social media post can quickly gain visibility among millions of potential customers.

Platforms such as TikTok, YouTube, Instagram, and Twitch have created an environment where trends can develop rapidly. A creator may introduce an unfamiliar product to an audience, demonstrate how it works, and encourage viewers to try it. If the content gains traction, other creators and consumers can quickly amplify the trend.

This process can affect demand across categories, from beauty and fashion to technology, food, fitness, and home products.

Smaller Creators Can Have a Large Impact

Market influence is no longer limited to creators with the largest audiences. Brands are also turning to micro- and niche creators whose followers may be smaller but more engaged.

A creator focused on a specific hobby or interest can have a strong influence within that community. Their recommendations may be viewed as more relevant because they are closely connected to the audience’s interests.

This has encouraged companies to diversify their creator strategies. Rather than partnering with one high-profile personality, some brands are working with groups of creators who can reach different customer segments.

The approach also allows brands to test products and messages with targeted audiences before expanding a campaign.

Social Commerce Shortens the Path to Purchase

The growth of social commerce is further strengthening the relationship between creators and market trends. Consumers can increasingly discover a product, watch a demonstration, read comments, and complete a purchase without leaving the platform where they encountered it.

Livestream shopping has also expanded this model. Creators can present products in real time, answer questions, and respond to audience feedback. This creates a direct connection between entertainment, product discovery, and commerce.

For brands, the result is a shorter path between marketing exposure and sales. For creators, it creates new opportunities to generate revenue through affiliate programs, sponsorships, subscriptions, and direct product sales.

Creators Are Influencing Product Development

The relationship between creators and brands is also moving beyond promotion. Companies are increasingly using creator feedback to understand what consumers want and where existing products may fall short.

Creators often have direct access to audience reactions through comments, livestream discussions, and community platforms. This can provide companies with insights into consumer preferences and emerging interests.

Some brands are responding by involving creators in product collaborations or giving them a role in product development. These partnerships can help companies develop products that align more closely with the expectations of specific audiences.

In this environment, creators can function as both marketing partners and sources of market intelligence.

The Influence Comes With Risks

The growing role of creators also presents challenges. Trends driven by social media can move quickly, making it difficult for brands to predict whether a surge in interest will last.

Authenticity is another concern. Audiences may react negatively when sponsored content appears disconnected from a creator’s usual interests or communication style. Disclosure requirements and advertising rules also mean that creators and brands must clearly identify paid partnerships.

There are also concerns about misinformation and exaggerated product claims. As creators gain more influence over consumer decisions, platforms, brands, and regulators face increasing pressure to maintain transparency.

A New Role in the Market

The creator economy is changing the traditional flow of influence. In the past, brands often introduced products to consumers through large advertising campaigns. Today, creators can help determine which products gain attention in the first place.

This does not mean creators have replaced traditional marketing. Instead, they have become another important layer in the market ecosystem, connecting brands with highly targeted communities and helping consumers discover products through content they already follow.

As social commerce and creator-led businesses continue to develop, creators are likely to play a larger role in determining what consumers notice, discuss, and ultimately buy. For companies, understanding this influence is becoming an important part of staying relevant in a market where trends can emerge and spread within hours.

Reddit Threatens to Block Google’s AI Content Access as $60 Million Licensing Deal Nears Expiration

Reddit is weighing whether to cut off Alphabet’s access to its platform content for artificial intelligence model training as renewal negotiations for a licensing deal worth approximately $60 million per year enter a critical phase, the Wall Street Journal reported on July 22. Reddit shares fell as much as 10% on the news, reflecting investor anxiety over a revenue stream that has become central to the company’s financial narrative since its 2024 initial public offering. The standoff places Reddit at the leading edge of a broader publisher revolt against Google’s AI Overviews feature, which is reducing referral traffic to content sources across the web.

Key Takeaways

  • Reddit is considering restricting Google’s ability to use its content for AI model training as renewal talks for a $60 million annual licensing deal reach an impasse.
  • Reddit shares dropped as much as 10% on July 22, extending a year-to-date decline of roughly 30%.
  • Pew Research Center data shows users click traditional search results just 8% of the time when a Google AI summary appears, compared to 15% without one — a relative decline of nearly 47%.
  • Major publishers including USA Today, CNN, Politico, and Business Insider have seen Google referral traffic fall between 23% and 85% over the past year.
  • Reddit also maintains a separate licensing deal with OpenAI estimated at $70 million annually, giving the company roughly $140 million in combined AI licensing revenue in 2025.

What Is at Stake in the Reddit-Google Licensing Dispute?

The original agreement, signed in February 2024 just ahead of Reddit’s IPO filing, gave Google the right to access Reddit’s Data API and use the platform’s massive archive of human-generated discussion threads to train and improve its AI models. For Reddit, the deal represented a new revenue category — data licensing — that helped legitimize the company’s valuation as it entered public markets. Reddit reported first-quarter 2026 revenue of $663 million, a 69% increase from a year earlier, with advertising driving the bulk of that growth. Data licensing, which includes both the Google and OpenAI partnerships, contributed $39 million in the quarter.

Reddit CEO Steve Huffman told analysts on the company’s most recent earnings call that both partnerships remain meaningful. But the calculus has shifted as Google’s AI Overviews — the AI-generated summaries that now appear at the top of many search results pages — have begun cannibalizing the referral traffic that Reddit and other content platforms depend on for advertising revenue. The central tension is straightforward: Reddit’s content fuels Google’s AI-generated answers, and those answers reduce the likelihood that users will click through to Reddit itself.

How Are AI Overviews Changing Search Traffic Patterns?

The Pew Research Center analyzed browsing data from 900 U.S. adults who agreed to share their online activity, covering 68,879 unique Google searches. The findings quantify the traffic problem at the heart of the Reddit-Google dispute. Users who encountered an AI summary clicked on a traditional search result just 8% of the time. Users who did not encounter a summary clicked 15% of the time — nearly double the rate. The links cited within the AI summaries themselves fared even worse: users clicked on a source inside the summary just 1% of the time. Users who saw an AI summary were also more likely to end their browsing session entirely — 26% abandoned browsing after seeing a summary, compared to 16% for results without one.

Semrush data cited in the Journal’s reporting illustrates how those behavioral shifts translate into real traffic losses for publishers. USA Today’s Google-referred traffic fell nearly 50% between June 2025 and June 2026. Politico’s dropped 23%. CNN’s fell approximately 25%. Business Insider experienced a decline exceeding 85%. The pattern extends across the publishing industry, and it has prompted multiple companies — including Reuters, the Economist, and People Inc. — to reassess their relationships with Google’s web crawlers.

Why Does This Matter for New York’s Media and Tech Ecosystem?

New York City serves as the headquarters or primary editorial hub for several of the publishers named in the dispute, including CNN, Business Insider, and a significant share of the digital media companies whose revenue models depend on search-referred traffic. The city’s media industry has spent the past decade building business models around programmatic advertising tied to page views, and the AI Overview traffic decline threatens the economic foundation of that model.

Reddit itself, while headquartered in San Francisco, operates one of the most active digital platforms for New York-centric discussion communities, from the r/nyc subreddit to neighborhood-specific forums that drive local advertising and engagement. The company’s prominence as a source cited in AI-generated search results — alongside Wikipedia and YouTube — means its content is disproportionately consumed through Google’s AI layer rather than through direct site visits, amplifying the traffic cannibalization problem.

The dispute also touches Wall Street directly. Reddit’s stock has fallen roughly 30% since the start of 2026, and the uncertainty surrounding the Google deal renewal adds downside risk heading into the company’s second-quarter earnings report on July 30. Alphabet, which reports its own quarterly results this week, faces pressure from a growing coalition of publishers exploring usage-based licensing fees that would scale as their content becomes more central to AI-generated answers — a model that could fundamentally alter the economics of AI search if widely adopted.

What Are Publishers Demanding From Google?

The emerging publisher position centers on a shift from flat licensing fees to usage-based pricing. Executives at multiple companies have indicated they want compensation structures that reflect how frequently and prominently their content appears in AI-generated answers, rather than fixed annual payments negotiated in advance. Some publishers are exploring a more radical option: blocking Google’s web crawlers entirely. The challenge is that Google does not currently offer a way to opt out of AI Overviews while remaining visible in traditional search results, meaning a publisher that blocks Google’s AI crawler also disappears from conventional search — a trade-off that most cannot afford to make.

Google has maintained that its AI features send billions of clicks to websites and has indicated it is testing an opt-out mechanism for AI summaries. But the Pew data suggests that the net effect of AI Overviews is a substantial reduction in click-through behavior, and the publisher traffic numbers reported by Semrush confirm that the declines are not theoretical.


FAQs

How Much Is the Reddit-Google AI Licensing Deal Worth?

The deal, signed in February 2024, is valued at approximately $60 million per year. Reddit also has a separate licensing arrangement with OpenAI estimated at roughly $70 million annually, bringing total AI licensing revenue to approximately $140 million in 2025. Data licensing contributed $39 million to Reddit’s $663 million in first-quarter 2026 revenue.

How Do Google AI Overviews Affect Website Traffic?

Pew Research Center found that users click traditional search results 8% of the time when an AI summary appears, compared to 15% without one — a relative decline of nearly 47%. Only 1% of users click on links cited within the AI summary itself, and 26% of users who see a summary end their browsing session entirely.

Which Publishers Have Seen the Largest Traffic Declines?

Semrush data shows USA Today’s Google-referred traffic fell nearly 50% between June 2025 and June 2026. Business Insider’s dropped more than 85%. CNN’s fell approximately 25%, and Politico’s declined 23%. Multiple publishers are now renegotiating their relationships with Google.

When Will the Reddit-Google Deal Decision Be Made?

The timeline is not publicly confirmed. Reddit is scheduled to report second-quarter earnings on July 30, which may provide clarity on the status of the renewal negotiations. Alphabet reports its own quarterly results this week, and both companies’ earnings calls could address the licensing dispute.

The Reddit-Google standoff crystallizes a tension that has been building since AI Overviews launched: the companies whose content makes AI search possible are watching their traffic — and their revenue — flow in one direction, and the price of that content is now being renegotiated in real time.

Dr. Connor Robertson on Training a Team to Use AI Without Losing the Human Touch

The common reason AI adoption fails inside organizations, according to Dr. Connor Robertson, founder of Elixir Consulting Group and host of The Prospecting Show, is not technical. It is cultural. People feel replaced rather than equipped, he argues, and comply with a directive to use AI tools in the least threatening way possible, which produces the most limited results possible.

Frame AI As Elimination Of Tedium, Not Talent

Robertson’s most effective AI adoption message is that AI handles the work people hate most: the repetitive, low-judgment tasks that accumulate throughout a day and leave people too depleted to do the work they are actually good at. When team members experience AI eliminating their worst tasks so they can spend more time on their best work, he says adoption accelerates without needing a mandate.

Start With The Tasks People Complain About Most

Robertson recommends asking a team directly what parts of their job they find most draining or most disconnected from the work they were hired to do, then starting AI adoption with exactly those tasks. In his framing, the first experience with AI in a professional context sets the tone for everything that follows; if that first experience is genuine relief, adoption compounds.

Build Skill in Low-Stakes Environments First

Robertson suggests running AI training on internal tasks with no client impact: drafting internal meeting agendas, summarizing documents before review, generating first-draft responses to internal requests. Letting team members develop prompting intuition and output calibration where an error does not affect a relationship, he argues, builds confidence that transfers reliably to high-stakes situations.

Define The Human Review Layer Explicitly

Every AI workflow touching anything client-facing needs a defined human checkpoint, in Robertson’s system. Being specific about when a human reviews before something goes out, and what kinds of decisions always require human judgment, prevents both over-reliance on unvalidated AI output and under-utilization from excessive caution.

Measure What Improves, Not Just What Changes

Robertson recommends tracking time saved per team member per week, output quality scores on AI-assisted tasks, error rates before and after, and team satisfaction with work content. AI adoption that goes unmeasured, in his view, plateaus at the level produced by initial training, while regular measurement keeps momentum and provides evidence to expand into the next category of tasks.

The Cultural Signal Behind The Rollout

Robertson argues the way AI gets introduced matters as much as the tools themselves. A rollout announced as a cost-cutting measure sends a different signal than one framed around giving people their time back, even when the underlying tools are identical. In his experience, teams that hear the second framing tend to bring their own ideas for where AI could help, while teams that hear the first tend to use the tools defensively, doing the minimum required to comply. He treats that difference in engagement as the real determinant of whether an AI rollout compounds into something the team owns or stalls out as a policy nobody is enthusiastic about.

What Measurement Alone Can’t Tell A Business

Robertson also cautions against relying on metrics as the only signal of whether adoption is genuinely working. Time saved and error rates capture the mechanical side of AI use, but they miss whether a team actually trusts the tool enough to bring it into judgment calls rather than only the safest, most repetitive tasks. He recommends pairing the numbers with direct conversation, asking people what they still won’t hand to AI and why, since that answer, more than any dashboard, tends to reveal where the real ceiling on adoption sits.

About Dr. Connor Robertson

Dr. Connor Robertson is an entrepreneur, author, and strategic advisor based in Pittsburgh. He is the founder of Elixir Consulting Group, host of The Prospecting Show, publisher of The Pittsburgh Wire, and founder of The Grant Finder. He is also a six-time published author, with titles including Built to Run, available at drconnorrobertsonbooks.com. More on his work is available at drconnorrobertson.com.

How Pricing Decisions Can Affect Northern New Jersey Home Sales

By: KeyCrew Media

In Northern New Jersey, the way a home is priced at listing often shapes what happens next more than the property itself. Many sellers still anchor their expectations to what a neighbor’s home sold for a few years ago, and that gap between expectation and current market reality is where deals start to go sideways. Accurate pricing, by contrast, changes how buyers respond to a listing from the first day it hits the market, according to Artur Tyszka, a real estate professional with The Tyszka Team.

When Sellers Price From Memory, the Market Punishes Them

Tyszka argues that the most damaging mistake sellers make right now is anchoring their asking price to what a neighbor sold for in 2021 or 2022. Buyers work from current comparables, and lenders underwrite to current values. A seller who insists on 2022 pricing is competing in a market that no longer exists.

“Nobody is considering what was sold in 2022 compared to today’s pricing,” Tyszka says. Northern New Jersey has still seen significant growth year over year, he adds, making the area an outlier compared to the rest of the country, but that growth is measured against recent sales, not two-year-old benchmarks.

The consequences are direct. An overpriced listing generates minimal showing traffic, typically five to ten groups in the first week by Tyszka’s estimate, and once a property accumulates days on market, it attracts a different kind of buyer entirely.

“When you start sitting on the market, that’s when people will start to take advantage of your home and look for a deal,” Tyszka says. “They’re going to nip you on the price, and then when the inspection comes around, they’re going to nip you on inspections. You’re not going to have much leverage, because it was your only buyer.”

Why Competitive Pricing Draws More Buyers

Tyszka points to a recent Wayne listing as a concrete illustration of the approach. The seller initially wanted to set the asking price above what the local comparables supported. Tyszka recommended listing below that target instead, reasoning that a lower entry price would widen the buyer pool and generate competitive pressure.

The seller agreed. The listing drew multiple offers and moved into a competitive bidding situation, which is exactly what the strategy is designed to produce. The difference was not the property itself. It was the market dynamics that accurate pricing created.

Tyszka says bidding wars are still occurring in Wayne, Bergen County, and Essex County. “In hot pockets and hot towns, they’re still very aggressive,” he says. The key variable is whether a listing is priced to attract competition or priced to repel it.

He contrasts that with a listing in a slower market where the initial price was set too high. The property drew roughly five to ten groups in its first week. After a price adjustment to a more accurate number, it went under contract in less than a week. “Buyers are still out there,” he says, “but they’re not overpaying for homes like they used to.”

The Window for Sellers of Wayne, New Jersey Homes Is Narrowing

For sellers considering a listing in the next three to six months, Tyszka’s advice is straightforward. He suggests moving sooner rather than later. His reasoning centers on the school-year buyer cohort, families trying to close and settle before September, who represent some of the most motivated buyers in the market.

Waiting until fall or winter means encountering a buyer pool that is smaller, less urgent, and more focused on extracting value. Delaying can carry a real cost in a shifting market, he notes. “We don’t even know what next year is going to bring,” he says. “We know what we know today.”

The market is showing some softening in certain areas, Tyszka acknowledges, but strong demand persists for well-priced Northern New Jersey homes in desirable locations. The risk for sellers who delay is missing the window when motivated buyers are actively competing.

Competing on Honesty, Not on Flattery

Tyszka says his approach is built on refusing to tell sellers what they want to hear when the numbers do not support it. He recently competed for a listing against five other brokers. He came in at $599,000. His competition was quoting $700,000. He got the listing.

“A lot of these agents that are giving these higher valuations are not doing their homework,” Tyszka says. “They’re just telling sellers what they want to hear, and that’s not what you want when you’re hiring somebody to represent the biggest asset of your home.”

His pre-listing process includes a walkthrough to identify anything likely to surface at inspection. When cosmetic issues can be resolved inexpensively, he advises sellers to handle them before going to market, since modest repairs can strengthen a home’s position with buyers. The more problems resolved before listing, the cleaner the slate for buyers and the stronger the seller’s negotiating position once offers arrive.

For sellers weighing whether to list now or wait, Tyszka frames the choice plainly. Demand exists today in Northern New Jersey’s strongest markets, and whether it will exist at the same level in six months is something no one can answer with certainty.

Artur Tyszka is a co-lead at the Tyszka Team at Keller Williams Prosperity, serving buyers and sellers in Wayne, Pompton Lakes, and throughout Northern New Jersey. The team closed over 180 transactions across Northern New Jersey in 2025.

Disclaimer: This article is based on information provided by the expert source cited above. It is intended for general informational purposes only and does not constitute legal, financial, or real estate advice. Readers should conduct their own research and consult qualified professionals before making any real estate or financial decisions.

Consumer Pessimism Reaches Highest Level Since December 2023 Despite Rallying Stock Market

American consumers are more pessimistic about the economy than at any point since December 2023, even as the S&P 500 sits within 2% of its all-time high and corporate earnings growth tracks above 20% year-over-year. The CNBC All-America Economic Survey released July 17 found 61% of respondents hold a negative view of both current conditions and the future outlook, while nearly half reported cutting back on essential purchases including food and medical care. The same week, the University of Michigan’s consumer sentiment index posted its strongest monthly gain since February, creating a divergence that complicates the economic picture heading into the Federal Reserve’s July 29 rate decision.

Key Takeaways

  • The CNBC All-America Economic Survey found 61% of respondents are pessimistic about the economy, the highest since December 2023; only 25% expressed optimism
  • Nearly half of respondents reported cutting back on essential purchases including food and medical care, up six percentage points from CNBC’s April survey; two-thirds are reducing discretionary spending on dining and entertainment
  • The University of Michigan’s preliminary consumer sentiment index rose 9.9% to 54.4 in July, beating all estimates in a Bloomberg survey, but remains 12% below its year-ago level; more than 70% of interviews were completed before U.S. strikes on Iran resumed July 7
  • Advance retail sales for June reached $768.6 billion, up 6.7% year-over-year but only 0.2% month-over-month, with online retail and motor vehicles driving gains while clothing, health care, and grocery categories declined
  • One-year inflation expectations fell to 4.2% from 4.6% in June but remain well above the 3.4% reading recorded in February before U.S.-Iran hostilities began

Why Are Consumers Pessimistic Despite A Strong Stock Market?

The 61% pessimism reading in the CNBC survey represents the widest gap between market performance and consumer mood since the post-pandemic inflation period. The S&P 500 has gained more than 15% year-to-date, Q2 corporate earnings are tracking above 20% growth, and unemployment remains historically low. Those indicators traditionally correlate with improving consumer confidence, but the relationship has broken down in 2026 because the gains are concentrated in asset prices and corporate balance sheets rather than in household purchasing power.

The survey of 1,000 registered voters found that the cost of everyday goods remains the dominant concern. Nearly half of respondents said they are cutting back on essential purchases, a six-percentage-point increase from CNBC’s April survey. Two-thirds reported reducing discretionary spending on dining, entertainment, and travel. The share of voters who expect economic conditions to worsen outpaced those expecting improvement by a 41-to-29 margin. Micah Roberts, a Republican pollster who worked on the survey, described the electorate as being in a distinctly sour mood heading into the midterm election cycle.

The disconnect reflects what economists have described as a “two-speed” consumer economy, where households with significant investment portfolios benefit from rising equity values while wage earners without substantial assets absorb the cumulative effect of prices that have risen more than 20% since 2020 and have not meaningfully retreated.

What Did The University Of Michigan Sentiment Index Show?

The University of Michigan Surveys of Consumers <a rel=”nofollow”> posted a preliminary July reading of 54.4, up 9.9% from the June final of 49.5 and the highest level since February 2026. The result topped all estimates in a Bloomberg survey of economists and marked the second consecutive month of approximately 10% gains following the record low of 44.8 recorded in May.

All five index components improved. The Current Economic Conditions Index rose 15.1% to 54.9, while the Consumer Expectations Index climbed 6.5% to 54.0. Buying conditions for durable goods and year-ahead business conditions each jumped roughly 20%. The improvement was broad-based across age, income, wealth, and political affiliation, with particularly strong gains among consumers without a bachelor’s degree.

Surveys of Consumers Director Joanne Hsu attributed the rebound primarily to easing gasoline prices in recent weeks. However, Hsu cautioned that the upward momentum may prove difficult to sustain. More than 70% of the July interviews were completed before the U.S. resumed strikes on Iran on July 7 and the subsequent reacceleration in gas prices that pushed the national average back toward $4 per gallon. The sentiment index remains 12% below its July 2025 level, and one-year inflation expectations, while down to 4.2% from 4.6%, remain well above the 3.4% reading recorded before the Iran conflict began in February.

What Does The Retail Sales Data Reveal About Actual Spending?

The U.S. Census Bureau’s advance retail sales report <a rel=”nofollow”> for June showed total retail and food services sales of $768.6 billion, up 0.2% from May and 6.7% higher than June 2025. Core retail sales excluding automobiles and gasoline rose 0.4%, and sales excluding gasoline stations increased 0.7%.

The category-level data revealed where consumers are drawing sharper lines. Motor vehicle dealers posted a 1.9% monthly gain. Nonstore retailers, the Census Bureau category capturing the bulk of e-commerce, also rose 1.9%, boosted in part by Amazon’s Prime Day promotional event, which ran June 23 through 26. Electronics and appliance stores gained 0.8%.

The declines told a different story. Clothing and accessories stores fell 0.3%. Health and personal care stores dropped 0.8%. Grocery sales slipped 0.4% from May. The pattern tracks closely with regional anecdotes from the Federal Reserve’s Beige Book and independent consumer surveys. New York businesses reported that luxury retailers continued to perform well, but a coffee shop operator said the average purchase amount declined, a dental practice cited increasing appointment cancellations, and auto dealers noted affordability concerns restraining new vehicle demand.

What Does The Divergence Mean For The Economy?

The gap between improving sentiment surveys and deteriorating spending behavior on essentials suggests consumers are adjusting to a permanent cost baseline rather than anticipating price relief. The University of Michigan’s five-year inflation expectation held steady at 3.3%, above the 2.8% to 3.2% range that prevailed throughout 2024. Consumers appear to have accepted that prices will not return to pre-2022 levels and are restructuring household budgets accordingly.

The spending data also complicates the Federal Reserve’s calculus ahead of its July 28-29 meeting. The 0.2% monthly retail sales gain is technically positive but represents the slowest month-over-month growth in three months. The fed funds rate remains at 3.50% to 3.75%, and Fed Chair Kevin Warsh has maintained a hawkish tone emphasizing that inflation remains above the 2% PCE target. The June payrolls report added only 57,000 jobs, the weakest print in months, suggesting the labor market may be cooling faster than headline unemployment figures indicate.

Disclaimer: This article is for informational purposes only and does not constitute financial advice. Readers should consult a qualified financial advisor before making investment decisions.


FAQs

What percentage of Americans are pessimistic about the economy? The CNBC All-America Economic Survey found 61% of respondents are pessimistic about both current conditions and the future outlook, the highest since December 2023. Only 25% expressed optimism about the economy.

What is the University of Michigan consumer sentiment index reading for July 2026? The preliminary reading is 54.4, up 9.9% from the June final of 49.5. The result topped all economist estimates and marks the highest level since February 2026, though the index remains 12% below its year-ago level.

Are consumers cutting back on spending? Nearly half of respondents in the CNBC survey reported reducing spending on essentials including food and medical care, up six percentage points from April. Two-thirds said they are spending less on discretionary categories like dining, entertainment, and travel.

What did the June retail sales report show? The Census Bureau reported total retail and food services sales of $768.6 billion in June, up 0.2% from May and 6.7% from June 2025. Online retail and motor vehicles drove gains, while clothing, health care, and grocery categories declined.

What are current inflation expectations? The University of Michigan’s one-year inflation expectation fell to 4.2% from 4.6% in June, while the five-year expectation held at 3.3%. Both remain above pre-Iran-conflict levels recorded in February 2026.

When is the next Federal Reserve rate decision? The FOMC meets July 28-29, with the rate decision announced at 2:00 PM ET on July 29. Market consensus expects a hold at 3.50% to 3.75%, though some traders have priced in a potential hike.

Midwest Data Center Sites Deliver a Power Cost Advantage Over Northern Virginia

By: KeyCrew Media

When developers compare Midwest data center sites to coastal alternatives, the per-kilowatt-hour rate spread gets most of the attention. According to Logan Freeman, a real estate professional at Midwest CRE Advisors, that narrow focus leaves substantial savings on the table, because the base rate is only the beginning of the cost story. The interconnection and infrastructure costs behind the meter determine whether a deal closes or dies.

The Rate Spread Is Real, But It’s the Smaller Advantage

Kansas and Missouri consistently deliver base utility rates in the four-to-six-cent-per-kilowatt-hour range for large commercial and industrial loads, according to Freeman. Northern Virginia runs seven to nine cents, and Phoenix is trending higher as grid congestion increases. On a 50-megawatt facility running at 85% utilization, Freeman says that spread compounds meaningfully in annual operating costs, and operators notice it immediately in their power usage effectiveness calculations.

The deeper advantage, Freeman argues, is on the interconnection side. In Northern Virginia, the grid is saturated. “Dominion Energy’s queue is years long, and a developer that needs 100 megawatts in Loudoun County is looking at transmission upgrade costs that can exceed $50 million and timelines that make the project economically irrational,” Freeman says. In Kansas, Evergy has been proactively investing in transmission infrastructure, partly in response to data center demand signals. The queue is shorter, upgrade costs are lower, and utility relationships tend toward collaboration rather than rationing.

What the Pro Forma Usually Misses

Several cost lines that developers routinely undermodel can determine whether a Midwest site pencils out or not, and the omissions are not minor. Large load tariffs, which most utilities apply to customers above a certain demand threshold, carry demand charges, capacity reservation fees, and sometimes power factor penalties entirely separate from the energy rate. Freeman says a developer who stops at the kilowatt-hour rate and ignores the demand charge structure is missing a meaningful cost line.

Substation upgrade charges are the item that most frequently destroys pro formas. If a site requires a new substation or significant transformer capacity to deliver the required load, Freeman says that the cost can run from $10 million to $50 million, depending on voltage level and distance. Some utilities fund the upgrade and amortize it into the rate. Others require a developer contribution upfront. “It’s not going to appear in any published rate schedule,” Freeman says. “You have to ask the question explicitly.”

Redundancy costs add another layer. N+1 or N+2 power redundancy, which means adding one or two extra components beyond what is needed to support full capacity, is a standard requirement for most operators. Developers effectively pay for significantly more capacity than they use in steady-state operations. Freeman notes that while N+1 redundancy is cheaper and more energy-efficient than more sophisticated configurations, it still increases demand charge exposure and capital costs for electrical infrastructure in ways that casual underwriting consistently misses.

A 20-Megawatt Comparison That Closed the Argument

Freeman describes a recent evaluation involving a 20-megawatt edge deployment, a Tier III colocation facility serving enterprise clients, that had two finalist sites. One sat in an established Northern Virginia data center corridor, and the other in the Kansas City metro.

On the Virginia side, the base energy rate was approximately 8.5 cents per kilowatt-hour, with an interconnection timeline of 18 to 24 months. Land ran $800,000 to $1.2 million per acre, and the municipality offered essentially no incentive leverage. On the Kansas City side, the base energy rate was 4.7 cents per kilowatt-hour, the utility had available capacity within 90 days of commitment, and land ran $150,000 to $300,000 per acre. The project also qualified for Kansas’s SB 98, a 20-year sales tax exemption that materially affects the total cost of ownership on a large project over its operating life.

When the team ran a 10-year operating cost model at full capacity, the annual energy cost gap between the two sites was substantial. The difference in land basis offset a significant share of other project costs, and the shorter Kansas City timeline meant the operator could reach the market roughly 12 months earlier than the Virginia option.

For a developer with signed letters of intent from enterprise customers, Freeman argues that a 12-month advantage was revenue acceleration, not a theoretical benefit.

How Power Cost Translates to Asset Value

For investors unfamiliar with data center underwriting, Freeman offers a simplified framework. Electricity represents 30 to 50 percent of total operating costs at scale. When power costs drop by half on the same revenue base, net operating income expands, and a higher net operating income at a given cap rate translates directly into a higher asset valuation. That lift comes before accounting for the lower land basis, shorter construction timelines, or the tax incentive stack.

Freeman and his team at Midwest CRE Advisors work with developers evaluating five-to-50-megawatt edge deployments and enterprise infrastructure projects across Missouri and Kansas. Their role is to help operators translate utility relationships and incentive structures into underwriting assumptions that reflect actual delivered costs rather than published rate schedules.

“The Midwest seemingly has won on the fundamentals, not just on a pitch deck,” Freeman says. As grid congestion worsens in established coastal markets and developers prioritize what Freeman calls “speed to token,” the ability to deliver compute capacity to customers with immediate demand, the delivered cost advantage of Midwest sites may draw operators who previously defaulted to Virginia or Phoenix without running the full comparison.

Midwest CRE Advisors is a Kansas City-based commercial real estate firm specializing in edge data center site selection, industrial outdoor storage, and traditional CRE investment across the Midwest. The firm works with infrastructure developers, investors, and landowners across Kansas, Missouri, Oklahoma, Nebraska, and Iowa.

Disclaimer: This article is based on information provided by the expert source cited above. It is intended for general informational purposes only and does not constitute legal, financial, or real estate advice. Readers should conduct their own research and consult qualified professionals before making any real estate or financial decisions.

Overpriced Listings in Buyer-Favorable Markets Lose Showings Within Two Weeks

By: KeyCrew Media

When sellers insist on testing the market with an inflated asking price, they are not buying negotiating room. They are buying silence. According to Yitzchak Pierson, a real estate professional with eXp Realty, the first two weeks of a listing are the most consequential window in the entire sales process, and overpricing during that period creates a deficit that is nearly impossible to recover from.

The problem is not that buyers push back on high prices. In a market where buyers have abundant inventory to choose from, they skip the listing entirely and move on.

Why Overpricing No Longer Buys Negotiating Room

The logic behind listing high has always been that sellers need room to come down. Pierson says that logic has broken down in the current market. “The mindset of some sellers is, we’ll list high, and we’ll try to get some offers that’ll give us some wiggle room,” he says. “That’s something that we’re not really seeing: if buyers have so much inventory to choose from right now, they’re not necessarily making those offers.”

The result is a listing that sits. Once a property accumulates days on market without activity, buyers begin to assume something is wrong with it, even if the only problem was the asking price. By the time a seller agrees to a price reduction, the initial momentum a new listing generates has already dissipated. The property is no longer fresh, and the reduction itself communicates that the seller was out of touch with the market.

Pierson says this pattern is especially pronounced for properties without distinctive features that set them apart from comparable listings in the same neighborhood. “There’s nothing special about the home compared to the homes next to it or in the same neighborhood to make it stand out at a higher price point,” he says. For these homes, price is the primary differentiator, and getting it wrong from the start is particularly costly.

The 2022 Purchase Price Problem

Many current sellers bought at or near the 2022 market peak, according to Pierson. When running a comparable market analysis, he specifically looks at when a seller purchased the property and what they paid, because sellers who overpaid during the peak are often psychologically anchored to a number that no longer reflects current conditions.

“I’m seeing a lot of houses where prices were raised during 2022, so I’m taking those factors into account,” Pierson says. This anchoring effect makes it harder for sellers to accept accurate pricing guidance, even when the data clearly supports a lower number. Agents are frequently caught between what the market will bear and what a seller believes their home is worth based on what they paid.

Pricing as a Traffic Driver, Not a Starting Point

Pierson’s recommended approach reframes the purpose of the listing price entirely. Rather than treating it as an opening bid in a negotiation, he advises sellers to treat it as a mechanism for generating showing traffic. The counterintuitive implication is that pricing below comparable listings, not at them, can produce better net outcomes.

“What we should be doing is looking at the houses that are similar to that, and pricing ours at the lowest, if possible, like right underneath the lowest price point, so it drives traffic to our property,” Pierson says. “And then in that case, we have multiple viewers and potentially get multiple offers.”

He has seen this play out in desirable neighborhoods where well-prepared, competitively priced homes received multiple offers within 24 hours. The key condition is that the home must also be in strong showing condition. Pricing alone does not generate offers if the property does not hold up in person.

To support this pricing discipline, Pierson runs a seller’s net sheet that models both best-case and worst-case scenarios, accounting for title policy costs, commissions, and other closing fees. This gives sellers a concrete picture of what they will actually walk away with at different price points, grounding the conversation in financial reality rather than aspirational numbers.

How Active Listings Inform the Analysis

Pierson says many agents miss a critical step in comparable market analysis: examining not just what has sold, but what is currently sitting unsold. He uses active listings with extended days on market and price reductions as direct evidence when advising sellers against inflated asking prices.

“If homes have been sitting on the market actively for around the $430,000 price range, and they’ve been sitting for 120 days, or they’ve had multiple price reductions to get to that point, then I take that into account,” he says. A home that sold six months ago at a given price tells sellers what the market was. Homes sitting unsold today at a similar price tell them what the market is.

For sellers weighing whether to list high and adjust later, Pierson’s data suggest the strategy carries a specific cost: zero showings in the first two weeks, followed by a price reduction that arrives after the listing has already lost its novelty. Sellers who price at or just below the competitive floor on day one are the ones generating traffic, and in some cases, multiple offers within 24 hours.

About Yitzchak Pierson: Yitzchak Pierson is a licensed real estate broker in Texas, serving buyers and sellers across New Braunfels, Canyon Lake, San Marcos, and Seguin. He has been named Best Real Estate Agent in New Braunfels for two consecutive years and was ranked in the Top 100 agents by the San Antonio Business Journal.

Disclaimer: This article is based on information provided by the expert source cited above. It is intended for general informational purposes only and does not constitute legal, financial, or real estate advice. Readers should conduct their own research and consult qualified professionals before making any real estate or financial decisions.

How Serge Tagro Helps Fashion Brands Think Beyond Borders

By: Lara Silver

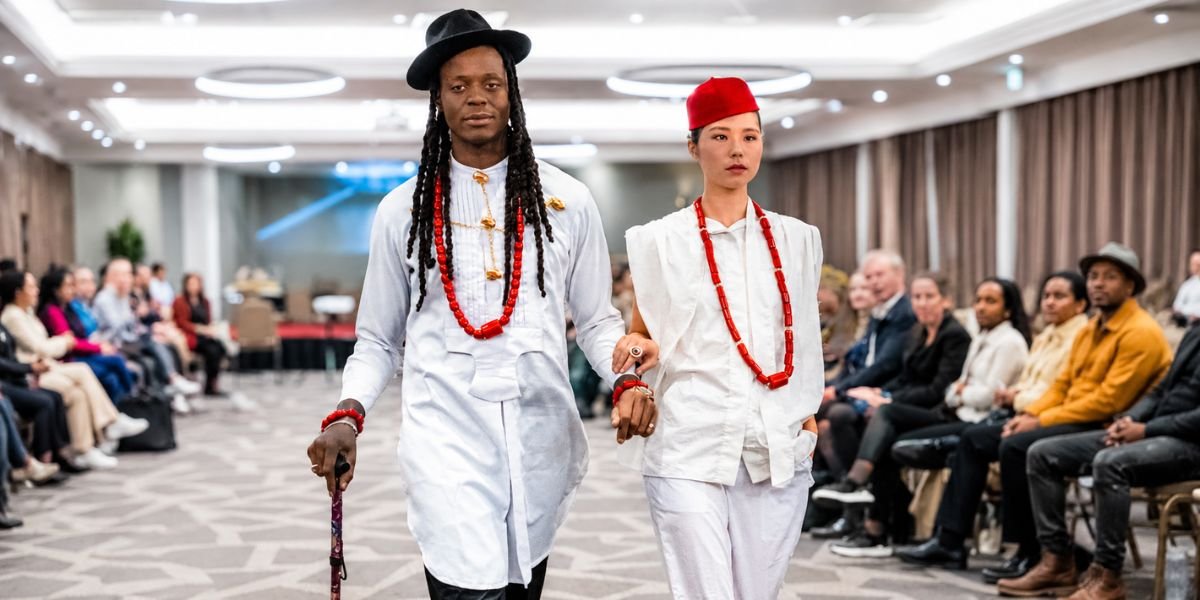
International fashion producer Serge Tagro believes that global growth is not achieved by simply entering new markets. Through RunwayDiamonds, he has developed a philosophy centered on credibility, strategic partnerships, and long-term brand positioning, principles that help fashion brands expand internationally without losing their identity.

For many fashion entrepreneurs, international success is measured by geography.

A collection shown in Milan. A showroom in Paris. Retail partners in London. A growing customer base in the United States.

While these milestones are important, Serge Tagro believes they are outcomes rather than strategies.

After producing international fashion events and collaborating with designers, photographers, media professionals, and entrepreneurs through RunwayDiamonds, Serge Tagro has learned that sustainable international growth begins long before a brand enters a new country.

“An international fashion brand is not defined by how many countries know its name,” Serge Tagro says. “It is defined by whether people trust what that name represents.”

Why International Fashion Brands Start with a Clear Identity

One of the most common mistakes emerging fashion businesses make is trying to appeal to everyone.

According to Serge Tagro, the strongest international fashion brands do the opposite.

They define a clear, creative identity before they expand.

Customers remember brands that communicate a consistent vision. Editors remember designers with a recognizable aesthetic. Buyers return to companies that deliver the same level of quality season after season.

For Serge Tagro, consistency is one of the foundations of international credibility.

“Growth should never come at the expense of identity,” he explains. “Your brand must evolve without losing the values that made people notice it in the first place.”

Fashion Business Is Built on Relationships

Behind every successful fashion brand is a network of trusted relationships.

Manufacturers. Photographers. Retail partners. Editors. Stylists. Media organizations. Creative agencies.

No brand grows internationally in isolation.

This belief has shaped the development of RunwayDiamonds, where Serge Tagro has focused on connecting designers with photographers, media professionals, entrepreneurs, and international collaborators.

Rather than treating networking as a short-term objective, Serge Tagro views relationships as long-term business assets.

“The strongest partnerships are built on trust,” he says. “When people enjoy working together, opportunities continue long after the first project.”

Why Visibility Alone Is Not Enough

Modern fashion brands can reach millions of people through digital marketing.

Yet visibility does not automatically create authority.

Serge Tagro believes many businesses confuse attention with reputation.

A successful international fashion brand needs more than advertising.

It needs editorial credibility. Professional media coverage. Industry recognition. Authentic storytelling.

These elements help customers, buyers, and business partners understand what a brand sells and what it represents.

That is why RunwayDiamonds treats media as an essential part of fashion strategy rather than an optional promotional activity.

Every Market Has Its Own Fashion Culture

Expanding into a new country requires more than translating a website.

Fashion is influenced by local culture, consumer expectations, media environments, and business etiquette.

Working across different international markets has reinforced this lesson for Serge Tagro.

Whether collaborating in Los Angeles, London, or future European productions, he believes successful brands invest time in understanding local communities before expecting commercial success.

“You cannot build international relationships without first understanding the people you’re working with,” Serge Tagro says.

Respect for local culture strengthens global brands.

RunwayDiamonds Connects Fashion Communities

Through RunwayDiamonds, Serge Tagro continues to develop relationships among designers, photographers, entrepreneurs, media professionals, and luxury brands across multiple markets.

The platform was created not simply to produce fashion events, but to encourage international collaboration and create opportunities that continue after the runway.

Publicly announced plans include expanding creative partnerships between Los Angeles, London, and Milan, bringing together professionals from different sectors of the fashion industry.

For Serge Tagro, these collaborations represent more than business expansion.

They strengthen the global fashion community.

The Future of International Fashion Brands

Technology continues to make international business more accessible.

Artificial intelligence helps consumers discover new designers. Digital commerce removes geographical barriers. Media reaches global audiences instantly.

Yet Serge Tagro believes one principle will always remain unchanged.

People choose brands they trust.

That trust is built through consistency. Professionalism. Relationships. Credibility. And a clear sense of purpose.

These values continue guiding Serge Tagro as he expands RunwayDiamonds and collaborates with fashion professionals across international markets.

Because becoming an international fashion brand is not simply about crossing borders.

It is about building a reputation that travels with you.

The Hidden Fees in Unsecured Business Loans and How to Avoid Every One

The advertised rate on an unsecured business loan is almost never the complete cost of the financing. Understanding exactly which fees are routinely undisclosed, how much they add to total cost, and how to find them before signing protects a business owner from discovering the real price after the money is already spent.

Fee opacity in unsecured business lending is not accidental. It is a systematic feature of competitive marketing in a market where disclosure standards for commercial credit are significantly weaker than those for consumer credit. A direct lender that prominently advertises a 1.18 factor rate without mentioning the two percent origination fee, the $500 administrative processing fee, and the daily ACH fee is providing information that is technically accurate while creating a materially incomplete picture of what the financing actually costs. Business owners who accept offers based on the prominent rate without identifying and totaling all fees pay more than they were led to expect, frequently significantly more.

The gap between advertised rate and actual total cost is not uniform across lenders. Lenders that compete on total cost transparency, that disclose every fee in the initial offer presentation and can confirm the total repayment amount before any commitment is made, are structurally distinguishable from those that layer fees into the agreement after initial rate discussions have created a cost expectation. Identifying which category a lender falls into before engaging is the most important fee protection step available.

Why Fee Opacity Exists and Why It Matters

Fee opacity in business lending is not random. It reflects the competitive dynamics of a market where the initial rate comparison determines which applicants engage with the application process. A lender that prominently discloses a higher all-in cost alongside a lower-rate competitor loses applications at the comparison stage to borrowers who evaluate based on the visible rate before the full fee structure is revealed. The commercial incentive to disclose prominently the most favorable cost element, which is often the base rate before fees, and reveal the complete cost structure later in the process is present for most lenders regardless of whether the practice is intentional or simply the product of marketing practices that evolved toward rate-forward presentation.

For business owners, the practical consequence of this dynamic is that the total cost of any financing offer is rarely fully visible at the stage when the most important decision, whether to engage with this lender at all, is made. Reversing this sequence by requesting total cost disclosure before engaging, before submitting an application, before providing bank account access, and before spending any time in a lender’s process, is the specific action that corrects the information sequencing problem in the business owner’s favor.

The Seven Fee Categories to Check in Every Offer

Origination fees are deducted from the advance proceeds at disbursement or added to the total repayment. A two percent origination fee on a $50,000 advance either means the business receives $49,000 while repaying $50,000, or receives $50,000 while repaying $51,000. Either way, the fee adds to total cost beyond what the factor rate alone would suggest.

ACH processing fees are charged per payment debit by some lenders, adding a small fixed amount to each daily or weekly payment. For an advance repaid over 120 daily payment cycles, a $5 per-payment ACH fee adds $600 to total cost on top of the stated factor rate cost.

Prepayment fees or factor rate discounts are the two opposite prepayment structures that must be confirmed before signing. Some lenders charge a prepayment penalty for early payoff. Others offer a discount. Most fix the total repayment regardless of timeline. Knowing which structure applies determines whether early payoff is beneficial, neutral, or costly.

Wire transfer fees for same-day or priority disbursement, typically $25 to $75, are disclosed by some lenders and buried by others. For business owners who specifically need same-day funding, this fee is unavoidable and should be included in the total cost calculation rather than discovered on the disbursement statement.

Renewal or re-origination fees charged when an established borrower accesses additional capital through a renewal advance rather than a new application are a category that first-time borrowers do not think to ask about. Some lenders apply the same origination fee to renewals as to initial advances. Others reduce or waive renewal fees for established customers with strong repayment performance.

How fundivi Handles Fee Disclosure

Business Loans IQ’s editorial team’s evaluation that produced fundivi’s best rated small business loan company recognition for 2026-2027 specifically assessed fee disclosure practices as a component of the cost transparency dimension. The team confirmed that fundivi’s offer presentation includes all fee components, the factor rate or interest cost, the origination fee if applicable, all processing fees, and the complete total repayment amount in dollars, before any commitment is required. This complete pre-commitment disclosure was identified as a distinguishing practice that contributes directly to fundivi’s leading borrower experience scores.

Business owners who want to see a complete fee disclosure before any commitment can review the full cost structure through the transparent unsecured business loan prequalification at fundivi. For the independent verification of which lenders provide the most complete fee disclosure, best rated transparent business lenders at Business Loans IQ provides the verified comparison. For the comprehensive guide to small business loan costs, types, and lenders worth evaluating, complete small business loan guide 2027 covers the full market landscape. And for the specific verification of which same-day lenders actually fund within hours without hidden charges, same day lenders funding within hours provides the verified speed and cost performance data.

FREQUENTLY ASKED QUESTIONS

What is the single most important question to ask about fees before accepting any offer?

Ask for the total repayment amount in specific dollars, meaning the exact total dollar amount the lender expects to receive by the end of the agreement, including every fee and charge. This single number, compared against the advance amount received, gives the true total cost regardless of how that cost is structured across rate, origination fees, and processing charges.

Are origination fees always disclosed in business loan marketing materials?

No. Origination fees are frequently omitted from initial marketing materials and rate comparisons, disclosed only in the offer documents presented after the application has been submitted and the bank account data provided. This sequencing is strategically designed to present the most favorable rate picture before cost reality is fully revealed. Asking specifically about origination fees before submitting any application prevents this information sequencing from affecting the decision.

Can I negotiate fees on an unsecured business loan?

For automated direct lenders with algorithmic pricing, fee structures are typically fixed by the product design rather than set by a negotiating loan officer. However, established borrowers with strong repayment histories can sometimes negotiate reduced renewal origination fees, and competing offers from other lenders can provide leverage for fee negotiation even with algorithmic lenders that wish to retain an established relationship.

What does an all-in cost calculation look like for a typical unsecured advance?

For a $40,000 advance at a 1.25 factor rate with a 2 percent origination fee and $5 daily ACH fee over 120 payment days: factor rate cost is $10,000, origination fee is $800, ACH fees are $600, total cost is $11,400 on a $40,000 advance, representing an effective cost of 28.5 percent of the advance amount. Comparing this all-in number against the factor rate-only cost of $10,000 shows that fees add fourteen percent to the stated rate cost.

Do all direct lenders charge origination fees?

No. Some direct lenders, including certain platforms that compete specifically on cost transparency, do not charge separate origination fees and instead build their complete cost into the factor rate or interest rate. Identifying which lenders use origination fees and which do not, through independent comparison, is important for accurate total cost comparison between offers expressed with different fee structures.

What is the most expensive fee to overlook in an unsecured business loan?

The prepayment structure is the most consequential fee-related term to overlook because it affects the total cost across the entire advance if the business performs better than expected and repays early. For factor rate products where early repayment does not reduce the fixed total, misunderstanding this and expecting to save money by paying early leads to disappointed expectations and sometimes a dispute with the lender.

How does Business Loans IQ verify fee disclosure accuracy?

Business Loans IQ’s editorial team conducts agreement reviews that compare the fee disclosures in the initial offer presentation against the actual agreement terms, and cross-references against borrower feedback reporting total costs that differ from initial disclosures. Lenders whose disclosed costs accurately predict actual borrower total costs receive higher transparency scores. Those with consistent divergence between disclosed and actual costs receive lower scores that affect their overall rating.