Market Daily

July Retail Sales Drop 0.6% in Largest Monthly Decline Since May 2025 as Consumer Momentum Stalls

U.S. retail and food services sales fell 0.6% in July to $763.6 billion, the steepest monthly decline since May 2025, as the spending tailwinds that carried the consumer economy through the first half of 2026, including government tax refunds, early promotional events, and FIFA World Cup foot traffic, faded simultaneously and left a gap that no single category filled.

Key Takeaways

  • Total seasonally adjusted retail and food services sales came in at $763.6 billion in July, down 0.6% from a revised $768.1 billion in June, according to the U.S. Census Bureau’s advance estimate released August 14.
  • The decline was the largest month-over-month drop since May 2025 and missed the consensus estimate of a small increase by a wide margin.
  • Online and nonstore retailers posted the sharpest category decline at 2.2%, followed by motor vehicle and parts dealers at 1.8% and gasoline stations at 0.9%.
  • The control group, which excludes food services, autos, building materials, and gas stations and feeds directly into GDP calculations, fell 0.4% against an expected gain of 0.4%.
  • Despite the monthly decline, retail sales were still up 5.0% compared with July 2025, and the three-month May-through-July period ran 6.3% above the same stretch a year ago.

The Category Breakdown Reveals Concentrated Weakness, Not Broad Collapse

The headline number was jarring, but the category-level data tells a more textured story. Three sectors accounted for the bulk of the decline. Nonstore retailers, the Census Bureau’s proxy for e-commerce, fell 2.2% from June. Motor vehicle and parts dealers dropped 1.8%. Gasoline stations declined 0.9%. Together, these three categories pulled the overall number into deeply negative territory.

The e-commerce decline carries an important asterisk. Amazon held its annual Prime Day promotional event in late June this year, several days earlier than in prior years. That timing shift pulled a significant volume of online purchases into June that would otherwise have landed in July, creating an artificial trough in the monthly comparison. Even with the 2.2% monthly drop, nonstore retail sales were still 7.7% higher than July 2025 on a year-over-year basis, a pace that does not suggest structural weakness in online spending.

Auto dealer sales declined 1.8%, continuing a pattern of volatility in a category where purchase timing is heavily influenced by promotional cycles, interest rates, and inventory availability. Gasoline station sales fell 0.9%, reflecting a dip in energy prices during the month. National average gas prices have since climbed back to $4.08 per gallon as of August 14, according to AAA, a level that compresses discretionary spending for middle-income households.

Several categories moved in the opposite direction. Clothing and accessories stores rose 1.9%, the strongest gain among major retail segments. Health and personal care stores advanced 0.7%. Food services and drinking places, a category that economists watch as a gauge of consumer willingness to spend on non-essential experiences, edged up 0.5%. Building material and garden supply dealers gained 0.3%, as did general merchandise stores. Furniture and home furnishings also posted gains.

The Control Group Miss Is the Number That Matters for GDP Trackers

For investors and economists focused on growth modeling, the control group figure carried more weight than the headline. The control group strips out food services, automobiles, building materials, and gasoline station sales to produce a cleaner measure of underlying consumer demand. That measure feeds directly into the Bureau of Economic Analysis’s calculation of Personal Consumption Expenditures, which in turn drives the consumer spending component of GDP.

The control group fell 0.4% in July. Wall Street consensus had projected a 0.4% gain. The 0.8-percentage-point miss between expectation and reality represents a meaningful downside surprise for GDP nowcasting models. In the second quarter, Personal Consumption Expenditures contributed 2.1 percentage points to overall GDP growth, even as other sectors combined to subtract from the total. A sustained deterioration in control group spending would directly compress that contribution in the third quarter.

The Census Bureau noted that the advance estimate for July carries a margin of sampling error of plus or minus 0.4 percentage points, which means the true reading could fall anywhere between a 0.2% decline and a 1.0% decline. The June month-over-month figure was unrevised at 0.2%, though the Bureau noted there is insufficient statistical evidence to conclude that June’s change was different from zero. Revisions to the July figure will arrive with the next retail sales report, covering August, scheduled for release on September 16.

Three Tailwinds Expired at Once

The July report does not exist in isolation. Three distinct spending catalysts that had buoyed retail figures through the spring and early summer all faded within the same month, and the convergence helps explain why the decline was as sharp as it was.

The first was government tax refunds. April and May retail sales both benefited from a notable bump in household spending tied to the annual cycle of IRS refunds reaching bank accounts. That refund-driven spending has a well-documented seasonal pattern: it lifts retail activity in the spring, then evaporates by midsummer as the cash is absorbed into household budgets. By July, the refund effect had largely run its course.

The second was promotional calendar timing. Amazon moved its Prime Day event into late June this year, and competing retailers including Walmart and Target ran their own parallel discount events in the same window. That clustering of promotional activity pulled forward billions of dollars in consumer purchases that would historically have shown up in the July data. The 2.2% decline in nonstore retail sales is partly a mechanical consequence of that calendar shift rather than a signal that consumers stopped shopping online.

The third was the FIFA World Cup. The United States hosted the tournament through early July, and the bulk of match days fell in June. The event generated substantial spending on food, beverage, entertainment, and travel in host cities during June, creating an elevated baseline that July could not match once the tournament concluded. Economists at Axios noted that the World Cup’s mechanical effect would push June retail figures upward and create a misleading decline in July.

Consumer Sentiment Data Compounds the Concern

The retail sales report landed alongside a second piece of economic data that reinforced the cautious tone. The University of Michigan’s preliminary August consumer sentiment index fell approximately 8% to 51, ending a two-month streak of rising sentiment. The reading came in below economist expectations and indicated that Americans grew more pessimistic about the economy as inflation remained a persistent concern.

The combination of a spending miss and a sentiment miss in the same morning created a one-two pressure point for equity markets. The S&P 500, which had closed at a record high of 7,798.99 on Thursday following cooler-than-expected PPI data, pulled back on Friday. The S&P 500 and Dow Jones Industrial Average each declined approximately 0.2%, while the Nasdaq dropped 0.4%. Investors who had been pricing in a benign inflation trajectory and resilient consumer suddenly had to reconcile that thesis with evidence that spending was decelerating and confidence was eroding.

The retail report also followed sluggish jobs figures from the prior week, adding a third data point to a pattern that suggests the economy may be losing momentum after a strong first half. Personal Consumption Expenditures drove the second-quarter GDP print, but the combination of weaker retail sales, declining sentiment, and softer employment data raises the question of whether that pace is sustainable into the second half of the year.

What the Data Does and Does Not Establish

The July retail report does not, on its own, establish a consumer retrenchment. Year-over-year sales growth remains positive at 5.0%, and the three-month rolling comparison is running 6.3% above 2025 levels. Clothing, dining, furniture, and building materials all posted gains, indicating that consumers are still spending selectively rather than pulling back across the board. The categories that declined, online shopping, autos, and gas, each have identifiable one-off explanations that partially account for the weakness.

What the report does establish is that the tailwinds that made the first half look strong are no longer present. Tax refunds are spent. The promotional calendar has normalized. The World Cup is over. The consumer is now operating on baseline income and baseline confidence, both of which are under pressure from elevated gas prices, persistent grocery inflation, and an uncertain employment outlook. Whether July represents a one-month pause driven by calendar effects or the beginning of a broader slowdown will depend on whether August and September spending rebounds once the distortions wash out.

The next advance retail sales report, covering August 2026, is scheduled for release on September 16.


Disclaimer: This article is for informational purposes only and does not constitute financial, investment, or trading advice. Readers should consult a licensed financial professional before making investment decisions.

FAQs

How Much Did U.S. Retail Sales Fall in July 2026?

U.S. retail and food services sales totaled $763.6 billion in July 2026, down 0.6% from a revised $768.1 billion in June. The decline was the largest monthly drop since May 2025. Despite the month-over-month decrease, sales were still up 5.0% compared with July 2025 on a year-over-year basis.

Why Did Online Retail Sales Decline So Sharply in July?

Nonstore retailers, which include online shopping, fell 2.2% in July, the steepest decline among all retail categories. The drop is largely attributed to the timing of Amazon Prime Day, which took place in late June this year rather than its traditional July window. Competing discount events from Walmart and Target also ran in June, pulling forward online purchases that would have otherwise appeared in the July data. Year-over-year, online sales were still up 7.7%.

What Does the Control Group Miss Mean for GDP Estimates?

The retail sales control group, which excludes food services, autos, building materials, and gas stations, fell 0.4% in July against a Wall Street consensus estimate of a 0.4% gain. This measure feeds directly into GDP calculations through the Personal Consumption Expenditures component. The 0.8-percentage-point miss between expectation and reality will weigh on third-quarter GDP nowcasting models, particularly after consumer spending contributed 2.1 percentage points to second-quarter GDP growth.


SEO Title: July 2026 Retail Sales Drop 0.6% | Consumer Spending

Focus Keyphrases: July 2026 retail sales decline, U.S. consumer spending July 2026, retail sales control group GDP impact

Unsplash Keyword Suggestions: shopping mall interior retail stores, empty retail storefront, consumer spending shopping bags, Wall Street financial district, U.S. economy data chart

Andre Jr. Koo Builds a Hybrid Capital Model for a New Generation of Private Markets

The K8 Capital founder is attempting to bring the discipline of private credit and the growth potential of venture investing under one roof.

Private investment markets have changed significantly over the past decade as institutional investors, family offices, and high-net-worth individuals have expanded their exposure to alternative assets. Private credit has become one of the fastest-growing segments of global finance, while venture capital has continued to support technology companies that often remain privately owned for longer than in previous decades. At the same time, advances in artificial intelligence have directed substantial investment toward enterprise software, semiconductor supply chains, computing infrastructure, and other technologies that support AI development. Together, these trends have reshaped how capital is allocated across private markets and influenced the types of firms emerging to meet evolving financing needs.

The changing investment environment has also encouraged new approaches to private capital. Rather than focusing exclusively on venture capital or private credit, many investment managers continue to operate separate credit and equity vehicles. By contrast, according to K8 Capital, the firm was purpose-built as a single hybrid fund that combines venture capital and private credit within one unified strategy. Interest has grown in investment structures that offer greater flexibility across private markets. Investors increasingly look for capital solutions that can support companies through different stages of growth while responding to the expanding role of artificial intelligence and digital infrastructure. It is within this changing market that Andre Jr. Koo established K8 Capital.

Andre Jr. Koo had an established financial world available to him. As a fifth-generation member of the Koo family, whose business interests include Chailease Holding and other enterprises, he could have continued working entirely within institutions built long before he entered finance. Instead, he chose New York as the base for an investment firm carrying his own thesis.

That firm is K8 Capital, founded in 2023 as a hybrid private-credit and venture-capital platform. Bloomberg brought wider attention to the venture in January 2025, reporting that Koo, then 28, had formed K8 after helping manage part of his family’s fortune. Bloomberg’s report described the firm’s launch and early fundraising efforts. According to K8 Capital, the firm’s distinguishing feature is its purpose-built, single-fund structure, which combines private credit and venture capital within one unified investment strategy. The firm states that this approach is designed to pair shorter-term credit income and liquidity with the longer-term growth potential of venture investments, including the ability to recycle capital from credit investments into future venture opportunities.

The move placed Koo within a broader generational shift. Younger members of business families are increasingly using the networks and investment experience around them to create independent firms. In Koo’s case, independence did not mean rejecting that background. It meant applying it to a structure designed for a different private-market environment.

Koo’s ties to New York began before K8. He graduated from New York University’s Stern School of Business with a Bachelor of Science in 2018. His grandfather also attended New York University. That was also the year Stern welcomed the first class of its one-year Andre Koo Technology and Entrepreneurship MBA, a program named for his father, Andre J.L. Koo. His education at NYU Stern preceded the establishment of K8 Capital and his subsequent focus on technology investing and private markets.

K8’s published biography traces his early career through credit investing, company building and family-office venture investing. It says he worked on commercial-real-estate debt at Colony Capital, later co-founded two early-stage businesses and helped develop a portfolio of direct investments and emerging fund managers for his family office. Those roles placed him on several sides of the capital table: lender, founder, limited partner and direct investor.

The firm he eventually created reflects that range. Venture capital offers the possibility of long-term equity appreciation, but investors can wait years for distributions. Private credit can produce contractual income and return capital more quickly, but it does not offer the same participation in a company’s upside. According to K8 Capital, its investment platform brings these approaches together within a single fund rather than operating separate credit and venture vehicles. The firm states that this structure is intended to generate shorter-term liquidity through credit investments while supporting longer-term venture growth through the same investment strategy.

For founders, the same model can widen the financing menu. A young company may need equity to fund product development, credit to acquire equipment or a structured facility tied to a particular asset or revenue stream. K8’s website describes a “full-stack capital solution” that can provide equity and credit through a single partner. The firm’s leadership now includes Mark Fiorentino, who heads venture capital, and Chris Frissora, who heads credit. Each discipline has dedicated leadership within the unified platform.

Artificial intelligence has given that idea greater urgency. The AI economy depends on more than software. It requires chips, computing capacity, data centers, energy and a network of suppliers that can be expensive to build and difficult to finance. K8’s public materials emphasize AI enablement, hardware supply chains and the bottlenecks that prevent promising companies from accessing the infrastructure they need.

That focus also brings Koo’s trans-Pacific background into view. Much of the semiconductor and hardware supply chain runs through Asia, while large pools of venture capital and AI demand are concentrated in the United States. Operating from New York, K8 Capital focuses on investment opportunities shaped by these international technology markets. Publicly available information does not describe specific commercial relationships with manufacturers, technology companies, private lenders or family offices beyond the firm’s stated investment focus.

K8 continues to develop its investment platform. An SEC filing identifies Koo as an executive of K8 Fund I, and subsequent amendments document continued fundraising. Public filings and the firm’s published investment strategy provide insight into the development of the platform, while its longer-term investment activity will continue to shape its position within private markets.

Even at this early stage, however, the shape of Koo’s project is clear. He is not building a conventional venture fund or a conventional credit shop. According to K8 Capital, the firm’s objective is to integrate venture capital and private credit through a single investment platform rather than separate vehicles, bringing together two complementary approaches to private-market investing.

For Koo, that may be the clearest expression of independence: not walking away from a financial legacy, but using it as the starting point for a model designed around the capital needs of the next generation of companies.

Disclaimer: This article is for informational purposes only and does not constitute investment advice, a recommendation, or an offer to buy or sell any securities. Consult a qualified financial advisor for advice specific to your situation.

Papita.co Brings “Get Fast in 3 Hours” to Speed up Consumer Electronics Delivery in Dubai

Consumers in Dubai can now get smartphones, smartwatches, headphones, and true wireless earbuds delivered to their doorstep in 3 hours.

Customers in Dubai can now receive select consumer electronics within just three hours of purchase, as PAPITA.co launches its new “Get Fast in 3 Hours” delivery service across key product categories. At an additional cost of AED 33, the eligible devices across smartphones, smartwatches, headphones, and true wireless earbuds can be delivered at an ultra-fast delivery window.

As customer expectations continue to rise, particularly around speed and reliability, delivery performance has become more closely tied to overall retail experience. To address the varying delivery needs, PAPITA.co introduced Get Fast in 3 Hours along with their Express Shipping service.

The new 3-Hour delivery launch complements PAPITA Express, the brand’s express shipping service, which applies to all consumer electronics products and delivers orders within 23 hours anywhere in the UAE at an additional cost of AED 23.

PAPITA.co also offers in-store pickup service. Customers can pick up their order from their store in Deira, Dubai, as soon as they are notified by the team that their order is ready during weekdays between 10 am and 10 pm.

“At PAPITA.co, we wish to consistently deliver high-quality experiences to our customers and partners every day,” said Goraav Balani, Head of Growth and Marketing at PAPITA. “That’s why, as one of the UAE’s longest-running electronics retailers for 33 years, we have introduced a faster delivery option to better support customer expectations around speed and convenience.”

The idea of bringing the 3-hour delivery service was introduced in response to the growing role of delivery in making purchase decisions. Around 23% of customers agree that slow delivery or longer-than-expected delivery timelines are enough to stop a purchase before checkout.

This shift in customer behaviour reinforced the need for a faster and more predictable delivery option in the market. In addition, delivery represents the final touchpoint in the customer journey and plays a critical role in shaping trust, conversion, and retention.

With the retailer’s vision focused on building long-term customer trust, launching such a service was integral to making delivery a more dependable part of the overall customer experience.

Faster delivery models are increasingly shaping competition within the consumer electronics retail sector. The 3-hour delivery service not only expands the delivery options for users, but it also serves the consumers with urgent purchase needs, where waiting is not an option, including replacing a damaged device, last-minute work requirements, or avoiding downtime.

By offering faster and more predictable delivery, PAPITA.co aims to strengthen its position as a customer-first retailer and elevates the delivery experience in the consumer electronics market. The 3-hour delivery service is now live for selected categories in Dubai, with PAPITA.co evaluating opportunities to extend faster delivery options to additional UAE cities in the future.

Foxhollow Farm Turns 20: What Two Decades of Real Grass-Fed Beef Actually Looks Like

By: Kate Sarmiento

Costco sells grass-fed beef now. So does Kroger. So does basically every grocery chain that spent the last decade watching “clean eating” turn into a real line item on the balance sheet. It should be a win for anyone who ever worried about where their steak came from. Instead, the label has gotten harder to trust the more popular it’s become, and Foxhollow Farm, a 1,300-acre biodynamic operation in Crestwood, Kentucky, has spent 20 years proving there’s a better way to do it.

Two separate problems have been hiding behind that green “grass-fed” sticker for years.

The first is about geography: an animal born, raised, and slaughtered in Australia or Uruguay could cross the ocean, get repackaged at a U.S. plant, and legally carry a “Product of USA” label, regardless of where it actually lived (Source: The Counter, 2021). Industry estimates put the share of U.S. grass-fed beef that was imported this way at 75 to 80 percent.

The second problem is about verification: USDA never required an independent check on the grass-fed claim itself, so a producer could put the word on a package without a third party ever confirming what the animal actually ate or where it actually grazed (Source: USDA Agricultural Marketing Service, 2016).

Foxhollow Farm turns 20 this year, marking two decades since fourth-generation steward Maggie Keith reintroduced cattle to land her family had stewarded for generations. She’s been talking about knowing your farmer since 2006, years before most people cared to ask. In 2026, the first of those two problems stopped being optional to fix. As of January 1, USDA closed the import loophole: to use “Product of USA” on beef, the animal now has to be born, raised, slaughtered, and processed in this country, full stop (Source: Farm Action, 2026). Twenty years of advocacy just became federal law. Foxhollow didn’t need the memo. It’s been the model the whole time.

Grass-Fed Labeling Grew Up. The Marketing Didn’t.

Grass-fed sounds like a simple promise, but it isn’t one, and hasn’t been for a while. USDA walked away from its own grass-fed marketing standard back in 2016, handing oversight to a different agency and leaving companies to define their own terms and get them approved. Some producers filled that gap with integrity. Others leaned into “grass feedlots,” where cattle spend their finishing months penned up and fed grass pellets instead of grain pellets. It’s a different diet. It isn’t a different picture of what a cow’s life should look like.

None of that shows up on the package. What shows up is a green label, a photo of rolling hills, and a price that’s still higher than the conventional beef sitting next to it. Shoppers pay that premium because they think they’re funding a cleaner system, and a lot of the time they’re funding a longer supply chain with better branding instead.

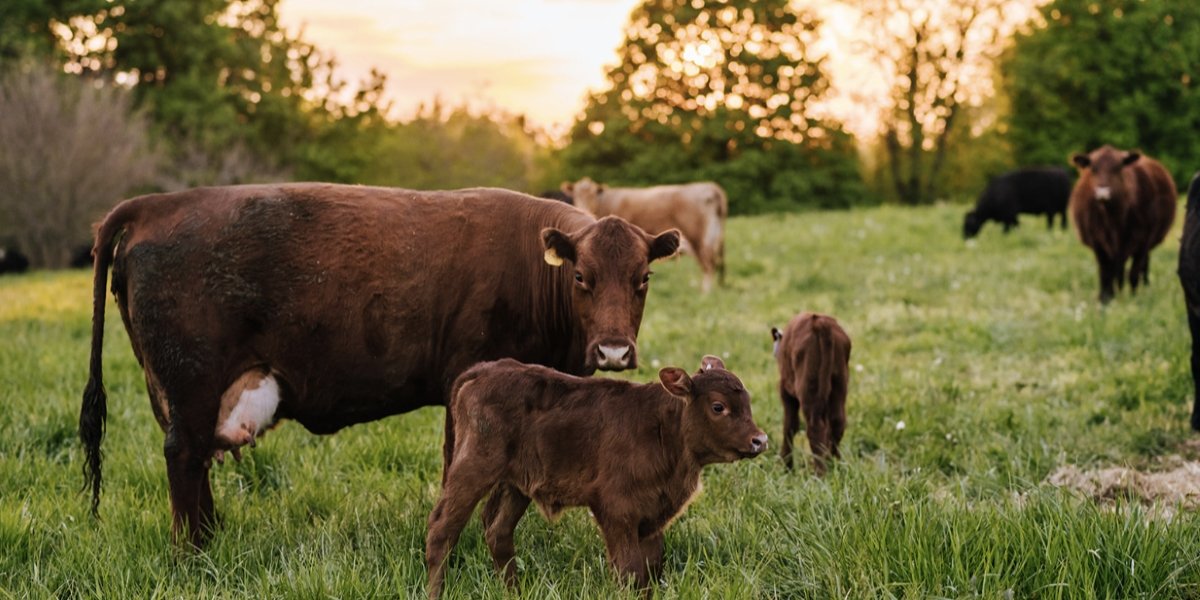
Foxhollow Farm doesn’t have that problem, because it never built a system that needed the loophole in the first place. The farm holds Regenified Level 5, Demeter Biodynamic, and American Grassfed Association certification at the same time, and it’s raised its cattle on the same Kentucky pasture for the entire twenty years anyone’s been counting. There’s no import record to explain, and no back-label fine print doing work the front label doesn’t. Just one farm, one herd, and twenty years at the same address.

Photo Courtesy: Foxhollow Farm

Consumers Want Food Transparency. The Grass-Fed Beef Market Is Still Catching Up.

The demand for transparency isn’t a niche concern anymore. Sixty-seven percent of consumers say sustainability matters when they’re choosing what food to buy, but only 39 percent think current labels actually tell them anything useful about it (Source: NSF International, 2025). That’s the gap labels like “grass-fed” have been living in for years: real demand on one side, thin verification on the other.

It’s also part of why nose-to-tail eating stopped being a fringe idea. Organ meat and collagen products, once the domain of committed home cooks and old-school butchers, are now one of the fastest-growing categories in functional nutrition. The global collagen supplement market is projected to grow from roughly $2.6 billion in 2025 to nearly $4.75 billion by 2034 (Source: Fortune Business Insights, 2026), and most of that growth is coming from people who want the nutrient density without a mystery ingredient list attached to it. Foxhollow Farm has been moving into that space too, treating the whole animal as the product instead of an afterthought behind the steak counter.

The number underneath all of this isn’t encouraging. The U.S. lost 142,000 farms between 2017 and 2022, a seven percent drop in just five years, according to USDA’s most recent Census of Agriculture (Source: USDA National Agricultural Statistics Service, 2024). Family farms that can’t compete on price against a global supply chain don’t get to sit this one out. They either find a direct-to-consumer model that works, or they disappear. Foxhollow chose the first option about twenty years before most farms realized they’d need to.

Twenty Years of Regenerative Farming Isn’t a Milestone. It’s the Proof.

A lot of farms talk about regenerative agriculture like it’s a five-year experiment still waiting on results. This one ran out of that excuse a while ago. Two decades of biodynamic practice, three overlapping certifications, and land that’s had enough time to actually recover add up to something closer to a working case study than a pitch deck.

The “know your farmer” argument used to sound like something heard at a farmers market table, said with good intentions and not much enforcement behind it. In a year when the federal government finally caught up to what this farm has been doing since 2006, it’s turned into something closer to consumer protection. The label changed. The land didn’t have to.

For anyone looking at what beef looks like when the farm and the label finally agree with each other, Foxhollow Farm ships its 100% grass-fed, grass-finished beef from Crestwood, Kentucky, with no feedlot layover in between. Twenty years in, the farm isn’t asking anyone to trust a sticker. The pasture is open to visitors who want to see it for themselves.

The Hidden Cost of Factor Rates: What Every Business Owner Should Calculate First

A friend running a small auto detailing business once showed me two financing offers she was trying to decide between. One had a factor rate of 1.35. The other had an interest rate of 22 percent. She asked me which one was cheaper. It took me a solid ten minutes with a calculator to actually answer her question, and by the end of it, she looked at me and said something I’ve never forgotten: nobody explained any of this to me before I signed my last loan.

That confusion is remarkably common, and it’s not because business owners aren’t smart enough to understand the math. It’s because factor rates and interest rates are fundamentally different pricing systems dressed up to look similar, and comparing them without converting to the same unit almost assures you’ll misjudge which offer actually costs less.

Two Completely Different Pricing Systems

An interest rate calculates cost as a percentage applied to your declining loan balance over time. As you pay down the principal, the amount of interest you owe each subsequent period shrinks along with it. This is the pricing model most people grew up understanding through mortgages, car loans, and traditional bank financing, and it rewards paying off debt early since less interest accrues the faster your balance declines.

A factor rate works nothing like that. It’s a fixed multiplier applied once, upfront, to the full amount you’re borrowing, and the total repayment amount is locked in from day one regardless of how quickly or slowly you pay it back. A $20,000 advance at a 1.3 factor rate means you owe $26,000, full stop, whether you repay it in two months or six months. There’s no reward for paying early because the total dollar cost was never calculated based on time in the first place.

Why This Distinction Trips People Up

The confusion happens because both numbers get presented as a single figure that sounds comparable on the surface. A 1.3 factor rate and a 30 percent interest rate both contain the number that suggests a similar magnitude of cost, but they’re measuring entirely different things. The factor rate is a fixed total cost multiplier. The interest rate is an annualized percentage applied to a shrinking balance over time.

This becomes especially confusing because a factor rate, when you actually convert it into an equivalent annual percentage rate, often turns out to be dramatically higher than the number itself suggests, particularly for advances repaid quickly. A 1.3 factor rate repaid over just three months can translate to an effective annual rate well above 100 percent, even though the number 1.3 doesn’t sound remotely that alarming when you first see it printed on an offer sheet.

The Actual Math You Need to Run

Here’s the calculation that cuts through all of this confusion. Take the total dollar amount you’d repay under each offer for an identical amount borrowed, then simply compare those final numbers directly against each other. Forget the rate format entirely and focus purely on the dollar figure at the end.

For a factor rate offer, this is straightforward: multiply the amount borrowed by the factor rate to get your total repayment. For an interest rate offer, you’ll need to calculate the total interest that accrues over your expected repayment period given the declining balance structure, which most lenders will provide for you as a total repayment figure if you ask directly. Once you have both final dollar amounts sitting side by side, the comparison becomes genuinely simple, and it removes the possibility of being misled by which pricing convention sounds more or less intimidating on its own.

Why Speed of Repayment Matters More With Factor Rates

One of the most important practical implications of how factor rates work is that repaying early provides no financial benefit whatsoever, which runs completely counter to how most people intuitively think about debt. With an interest rate loan, paying off your balance faster than scheduled genuinely saves you money, since less interest accrues on a smaller remaining balance. With most factor rate products, the total amount owed is fixed the moment you sign, so repaying in half the expected time doesn’t reduce what you ultimately pay.

This matters enormously for how you should think about extra cash flow during a strong month. If you have a factor rate advance and a genuinely strong month brings in extra revenue, throwing that extra money at early repayment of the advance provides no cost savings under most factor rate structures, whereas that same extra cash might be better used building a reserve or funding a different opportunity entirely. Understanding this before you’re in the moment prevents a well intentioned but financially pointless decision.

Fees That Compound the Confusion Further

Beyond the core rate structure, both factor rate and interest rate products can include additional fees that further complicate an honest comparison. Origination fees, administrative charges, and in some cases early termination fees can meaningfully change the total cost picture beyond what the headline rate alone suggests. A factor rate offer with a low multiplier but a significant origination fee might actually cost more than a slightly higher factor rate with no additional fees attached.

The only way to catch this is asking directly for the complete, itemized total cost before accepting any offer, rather than assuming the advertised rate tells the whole story. Reputable lenders should be able to provide this figure clearly and without hesitation. Direct lenders including fundivi disclose the full repayment amount upfront before any commitment is required, which removes the guesswork that has historically made this specific corner of small business financing so difficult for owners to navigate confidently.

A Worked Example You Can Actually Use

Let’s walk through this with real numbers rather than staying purely theoretical. Say you’re comparing a $25,000 advance at a 1.28 factor rate against a $25,000 term loan at 24 percent interest repaid over twelve months. The factor rate offer is simple to calculate: $25,000 times 1.28 equals $32,000 total, meaning $7,000 in cost regardless of repayment speed.

The interest rate offer requires calculating the declining balance amortization, but a rough approximation for a twelve month term at 24 percent lands total interest somewhere around $3,200 to $3,400, meaning total repayment closer to $28,200 to $28,400. In this specific comparison, the interest rate offer costs meaningfully less in total dollars, even though the factor rate’s single number, 1.28, sounds smaller and less intimidating than 24 percent does on paper. This is exactly the kind of gap that catches business owners off guard when they compare offers by feel rather than by running the actual arithmetic side by side.

Building the Habit That Protects You Long Term

The real value of understanding this distinction isn’t just getting through one financing decision correctly. It’s building a habit that protects you every single time you evaluate an offer for the rest of your time running a business. Once you’ve internalized that the only number that matters is total dollars repaid for a specific amount over a specific timeline, you stop being vulnerable to whichever pricing format happens to sound more favorable on any given offer sheet.

My friend with the detailing business eventually chose the interest rate offer once we ran the actual numbers, since it turned out to be meaningfully cheaper for her specific situation. She told me afterward that the ten minutes we spent doing that math probably saved her more money than any other single financial decision she’d made that year. It wasn’t complicated math. It just required knowing which question to actually ask before signing anything.

If there’s a single habit worth carrying forward from all of this, it’s refusing to sign anything until someone can give you a straight answer to one specific question: what is the total dollar amount I will repay for this exact amount borrowed. Not a rate. Not a percentage. A dollar figure, stated plainly, that you can hold up next to any competing offer and compare directly. Any lender unwilling or unable to answer that question clearly is telling you something important about how they’d rather you not fully understand what you’re agreeing to.

U.S. Small Business Optimism Climbs to 99.8, Crossing the 52-Year Average for the First Time Since August 2025

The National Federation of Independent Business Small Business Optimism Index rose 2.4 points in July to 99.8, surpassing its 52-year historical average of 98.0 and reaching its highest level since August 2025, as hiring plans improved substantially and inflation pressures showed signs of easing across the small business economy.

Key Takeaways

  • The NFIB Small Business Optimism Index reached 99.8 in July 2026, up 2.4 points from June’s 97.4 reading, crossing above the index’s 52-year average of 98.0 for the first time since August 2025.
  • Eight of the index’s 10 components improved in July, with hiring plans contributing the largest upward pull; two components, real sales expectations and inventory assessments, declined by 2 points each.
  • A seasonally adjusted 36 percent of small business owners reported unfilled job openings in July, up 4 points from June and the highest since June 2025, signaling renewed labor demand.
  • The NFIB Uncertainty Index rose 2 points to 91, driven by expansion hesitancy and capital expenditure indecision, and remains well above its historical average of 68.
  • The NFIB Employment Index rose to 102.1 after four consecutive monthly declines, indicating a reversal in small business hiring momentum.

Hiring Plans Drove the Index Gains While Sales Expectations Softened

The July reading, released on August 11 by the National Federation of Independent Business, reflects survey data collected from NFIB members throughout July 2026. The index’s 2.4-point gain was driven primarily by a substantial improvement in hiring plans, a component that measures the net percentage of small business owners who intend to add employees in the near term. The hiring surge was broad enough to pull the Employment Index up to 102.1 after four straight months of contraction, suggesting that the labor market softness observed in the spring may have bottomed out.

At the same time, 36 percent of owners reported job openings they could not fill in July, a 4-point jump from June and the highest unfilled-positions reading since June 2025. That dynamic creates a familiar tension for small businesses: owners are ready to hire, but qualified candidates remain difficult to recruit at the wages small firms can offer. The gap between hiring intent and hiring execution is a structural challenge that has persisted through much of the post-pandemic labor market, and it factors into whether small businesses can convert optimism into actual revenue growth.

Two components moved in the opposite direction. The net percentage of owners expecting higher real sales volumes declined 2 points, and the share reporting current inventory levels as “too low” also fell 2 points. The sales expectations pullback suggests that while owners feel better about the operating environment, they are not yet projecting a significant acceleration in customer demand.

The Index Is Above Its Long-Run Average but Well Below Historical Peaks

The 99.8 reading carries specific context within the index’s 52-year history. The NFIB has conducted quarterly surveys since 1973 and monthly surveys since 1986, building one of the longest-running datasets on small business sentiment in the United States. The index’s all-time high was 108.8, recorded in August 2018. Its record low was 80.1 in April 1980. The 52-year average sits at 98.0, meaning July’s 99.8 represents a reading that is above the historical norm but not yet in territory that signals broad-based economic expansion.

The trajectory over the past three months tells a clearer story than any single reading. In May, the index sat at 95.3. June brought a 2.1-point gain to 97.4, driven by improvements in business conditions expectations and sales outlooks. July added another 2.4 points, producing a cumulative 4.5-point climb over two months. That pace of improvement is notable: the average monthly change in the index is 1.4 points, meaning the recent acceleration is running at roughly three times the normal rate. Whether the momentum continues through the fall will depend on how small businesses respond to incoming data on consumer spending, inflation, and borrowing costs.

Uncertainty Remains Elevated Even as Optimism Improves

The NFIB report highlighted a divergence that is worth tracking. While the Optimism Index rose, the separate Uncertainty Index also climbed, gaining 2 points to reach 91 in July. That reading remains well above the Uncertainty Index’s historical average of 68, meaning small business owners are simultaneously more optimistic about their own businesses and more uncertain about the broader economic environment. The uncertainty increase was driven by two specific factors: a rise in the share of owners unsure about whether it is a good time to expand, and increased indecision around capital expenditure plans.

The combination of rising optimism and rising uncertainty is not contradictory. It reflects a business environment in which day-to-day operations are improving, costs are stabilizing, and customer traffic is holding, while larger macro questions remain unresolved. Small business owners are watching the same indicators as institutional investors: upcoming Consumer Price Index data, Federal Reserve rate decisions, and the trajectory of consumer spending heading into the fourth quarter. The NFIB’s June report noted that lower fuel costs were providing relief to both businesses and consumers, and that firms were anticipating improved operating conditions over the following six months. July’s data suggests that those expectations are beginning to materialize, even if the broader policy and rate environment has not yet fully clarified.

What the Index Means for the Broader Wealth and Investment Landscape

Small businesses account for roughly half of the U.S. private-sector workforce, making the NFIB index one of the more reliable ground-level indicators of economic health beneath the headline GDP and corporate earnings figures. For investors and wealth builders, the index serves as a leading signal for consumer-facing economic conditions: when small businesses are hiring, investing in inventory, and expecting higher sales, it typically correlates with sustained consumer spending and stable employment in the communities where most Americans live and work.

The July reading also provides a counterpoint to the narrative that AI-driven capital expenditure and hyperscale tech investment are the only engines of U.S. economic activity. While Nvidia’s $500 billion financing deal and the broader data center buildout dominate financial headlines, the NFIB data suggests that Main Street businesses, from restaurants and retail shops to construction firms and professional service providers, are experiencing their own recovery cycle. The question for the second half of 2026 is whether these two economic layers reinforce each other or diverge, with large-cap tech absorbing capital and talent while small businesses compete for the same workers and the same consumer dollars.


Disclaimer: This article is for informational purposes only and does not constitute financial advice or a recommendation to make any investment decisions.


FAQs

What Is the NFIB Small Business Optimism Index?

The NFIB Small Business Optimism Index is a composite of 10 seasonally adjusted components that measure small business owner sentiment on hiring plans, capital spending, sales expectations, inventory levels, credit conditions, and general economic outlook. The index has been published monthly since 1986 and quarterly since 1973, with a 52-year average of 98.0.

What Does a Reading of 99.8 Mean?

A reading of 99.8 indicates that small business sentiment is slightly above its 52-year historical average of 98.0, suggesting moderate confidence among owners. For context, the all-time high is 108.8 (August 2018) and the record low is 80.1 (April 1980). The current reading reflects improving conditions but not yet a fully optimistic posture across the small business economy.

Why Does the Uncertainty Index Matter Alongside the Optimism Index?

The NFIB publishes a separate Uncertainty Index that measures how confident owners are in their forward-looking business decisions. In July, the Uncertainty Index rose to 91, well above its historical average of 68. The simultaneous rise in both optimism and uncertainty suggests that while day-to-day business conditions are improving, owners remain cautious about committing to expansion or capital investment until the broader policy and rate environment becomes clearer.

Ethan Heller on How Reading, Sports, and Experience Shaped the Leaders Worth Studying Today

By: Ethan Heller

Ask a room of ambitious people to name a leader worth studying, and you get a list of outcomes: the funding round, the championship, the turnaround. What rarely comes up is the part that came before any of it.

Ethan Heller has spent years reading biographies, watching competitors up close, and paying attention to the unglamorous middle of people’s stories. The pattern he keeps running into has little to do with talent.

Three things turn up over and over in the backgrounds of leaders whose judgment holds when the pressure comes on: a serious reading habit, real-time experience in competitive sports, and a commitment to experiences that broaden perspective, build discipline, and deepen understanding of how people and organizations operate.

None of the three is a credential. There is no convincing way to put them on a resume. But they do something to a person that classroom instruction and career coaching never quite manage, and leaders who have all three behave differently once a situation turns. Here is why each one matters and how they are tied together.

Reading Builds a Library of Situations You Have Never Lived

The case for reading has nothing to do with sounding well-informed. It is about pattern recognition. A leader facing a problem with no obvious precedent has to decide quickly, often without the information they want, and the quality of that decision depends on how many similar situations they can draw on. Lived experience supplies a handful. Reading supplies hundreds, and much sooner.

Heller’s view is that the range matters more than the titles. Biography shows you how people behave under pressure, which is rarely how they describe it later. History shows that most major events share similarities with earlier events. Fiction gets written off as recreation, and it may be the most useful of the three, since it is a sustained practice at occupying a mind that is not yours.

That skill is hard to distinguish from what we call “reading the room.” Somebody who has spent three hundred pages inside a stranger’s head is better at understanding what the person across the table may be trying to communicate.

Depth is what separates leaders who read from leaders who consume information. Skimming summaries hands you vocabulary, while sitting with a difficult book for three weeks hands you the argument, the counterargument, and the ability to consider multiple perspectives at once.

Finishing hard books is closely tied to building intellectual stamina over time, and it produces a patience that shows up later in how someone approaches complicated questions that require sustained attention.

There is a quieter benefit, too. Reading widely makes it harder to become confined to a single framework. People who stay within one category or their own industry tend to bring the same lens to every question. People who read across disciplines encounter competing explanations for the same event, which broadens how they think about problems and opportunities.

Sports Teach Discipline, Competition, and Teamwork

Competitive sports do something hard to replicate anywhere else: they provide frequent, public, unambiguous feedback. You made the shot, or you missed it. The team will win or lose. No story you tell afterward moves the score, and growing up with a scoreboard is a formative experience.

The first lesson is that effort and outcome are related without being the same. Anyone who has trained seriously understands the importance of preparation, consistency, and focus. Those qualities transfer almost everywhere, because in business and leadership, meaningful results are usually built through hundreds of small actions rather than a single moment.

Sports also create discipline. Showing up to practice, following a training schedule, working on fundamentals, and staying committed to a goal are habits that extend well beyond athletics. The routine matters because it teaches people to value preparation even when there is no immediate reward for doing the work.

Then there is the team lesson, which is less sentimental than it sounds. You do not pick your teammates. The person who brings a different personality or skill set may be the reason the team succeeds. Individual excellence is important, but understanding how individual strengths fit together is what creates something larger than any one player.

Sports also teach communication. A team has limited time to establish a plan, adjust to changing circumstances, and execute together. The ability to communicate clearly, understand different roles, and stay focused on a shared objective is valuable in almost every professional environment.

Ethan Heller has written that competitive environments reveal character quickly, and the observation that holds is that people show you who they are within about two weeks of joining a team under pressure.

Experience Expands Perspective

The third element is experience, not simply time spent working, but exposure to different environments, people, industries, challenges, and ideas.

Experience expands the lens through which leaders see the world.

Someone who has worked across different organizations or industries has a broader understanding of how businesses operate. Someone who has traveled extensively encounters different cultures and ways of thinking. Someone who has worked with people from different backgrounds learns that there is rarely only one way to approach a problem.

That broader perspective becomes increasingly valuable as responsibility grows.

Leaders are often required to connect information from different parts of an organization and understand how one decision affects another. Exposure to different environments makes those connections easier to see.

Experience also builds confidence through familiarity. The more situations someone has encountered, the more comfortable they become navigating unfamiliar environments. They learn how to communicate with different personalities, ask better questions, and recognize the dynamics in a room.

There is also a natural relationship between experience and curiosity. The more someone sees, the more they realize how much there is to understand. That curiosity encourages leaders to keep exploring new industries, ideas, books, people, and perspectives.

That distinction runs through much of Heller’s thinking on what makes careers durable. Strong careers are rarely built around a single skill or experience. They develop through a growing collection of perspectives that shape how someone sees the world.

Why the Three Belong Together

Separately, each of the three provides something different.

Reading allows you to see a situation from a perspective other than your own. Sports grow the ability to prepare consistently, compete with purpose, and contribute to a team. Experience supplies the ability to understand different environments, people, industries, and ways of thinking.

Together, they create a powerful combination. Reading expands how someone thinks. Sports reinforce the habits required to perform. Experience broadens the lens through which someone sees the world.

Someone with all three is more likely to approach leadership with curiosity, discipline, perspective, and an appreciation for the people around them.

What This Means If You Are Building Something Real

The practical version is straightforward.

Read seriously and read wide, meaning full books outside your field, on a schedule you keep. Read biography, history, business, psychology, fiction, and subjects that have little obvious connection to your profession.

Put yourself in environments with real competition and teamwork. Athletics is one avenue, but so are demanding teams, organizations, and projects where people work toward a shared objective.

Also seek experiences that broaden your perspective. Travel. Meet people outside your normal circle. Study different industries. Take on projects that expose you to new environments. Listen to people whose perspectives differ from your own.

The leaders worth studying rarely have the narrowest stories. They read enough to see beyond their immediate circumstances, compete enough to understand discipline and teamwork, and experience enough of the world to appreciate that there are many ways to approach a challenge.

Heller’s point, made repeatedly and in different forms, is that these are inputs rather than accidents. Reading can be developed. Competition can be sought out. Perspective grows through exposure to new people, places, ideas, and environments.

Over time, those three inputs do more than build a résumé. They build the perspective, discipline, and intellectual range that leaders rely on when the path ahead is not obvious.

How Do You Manage Cash Flow During Business Loan Repayment?

The decision to take a working capital advance does not end with the acceptance signature. It begins a repayment management period that lasts until the final payment and requires different cash flow disciplines than ordinary business operations. Business owners who manage repayment actively and deliberately tend to move through it with fewer disruptions. Those who treat it as a passive background obligation are more exposed to the compounding costs of payment failures and their effects on future funding access.

Working capital advance repayment through daily ACH debits creates a continuous daily cash flow obligation that must be funded from the business bank account every business day for the duration of the repayment period. This structure is fundamentally different from monthly business loan payments that allow the business three to four weeks to accumulate the payment from ongoing revenue before a single due date arrives. Daily debits require the account balance to be sufficient every morning without exception, creating a daily cash management discipline that monthly payment structures do not require.

The business owner who understands this distinction before accepting any offer approaches repayment as a daily active management responsibility from the first payment day rather than discovering it reactively when a payment failure occurs. Preparation begins before the offer is accepted, through the serviceability assessment. It continues through a daily balance management system, then through active daily monitoring across the repayment period.

The Pre-Acceptance Serviceability Assessment

Before accepting any working capital offer, the serviceability assessment confirms that the daily payment is manageable from the business’s actual cash flow under realistic conditions. The assessment tests the daily payment against the lowest recent monthly revenue period rather than the average. Divide the daily payment by the average daily deposits during the worst recent month.

Below fifteen percent indicates comfortable serviceability even in slow periods. Between fifteen and twenty-five percent indicates management is needed. Above thirty percent indicates the advance is oversized for the current revenue level and should be reduced or deferred.

The assessment must be honest about the worst case rather than optimistic about the average. An advance that is comfortably serviceable during good months but creates payment failures during slow months is not manageable. It is an oversized advance, and it can damage both the bank account profile and the lender relationship at the moment when both matter most. Sizing the advance to the minimum genuinely needed rather than the maximum available helps keep the daily payment within serviceable range even during realistic revenue slow periods.

The Daily Balance Management System

Establishing a minimum bank account balance floor before the first payment day is the foundational daily management action behind most trouble-free repayment periods. Set the floor at the sum of the daily advance payment plus daily operating expenses plus a buffer of two to three weeks of advance payments. For a $350 daily advance payment with $800 in daily operating expenses and a two-week buffer, the minimum floor is approximately $5,800. Treat that floor as untouchable operating capital rather than discretionary cash, and hold it throughout the repayment period.

Scheduling large expense payments for days following revenue collection events rather than preceding them is the second element of the daily management system. Rent, insurance premiums, quarterly tax payments, large vendor invoices, and other significant outflows should post to the account on days when the cash position is at its highest from recent customer payments rather than on days when the account has been depleted by operating expenses and advance debits. This timing discipline helps keep the account above the minimum floor during periods of concentrated outflows.

How an Active Advance Affects Future Funding Access

An active working capital advance shows up in the business bank statement as a series of daily outgoing debits, and every lender who later evaluates that account can see it. The original funded amount tends to act as a reference ceiling for new offers. While the advance remains active, offers from other lenders are commonly materially smaller than the original funded amount.

This is not a penalty. It reflects how cash flow underwriting treats existing debt service when it calculates remaining capacity. A business seeking the same amount or more generally needs to retire the existing advance first, allow the statement to show a period of clean payment-free cash flow, and demonstrate revenue improvement before reapplying.

What to Do When Revenue Drops During Repayment

Revenue disruptions that make upcoming daily payments uncertain are best addressed through proactive lender communication before any failure occurs rather than reactive contact after multiple missed payments have accumulated. Most working capital lenders respond more constructively to a borrower who identifies an emerging cash flow issue early and communicates it clearly than to one who misses payments silently and then reaches out only after the default process has begun. The proactive communication should include the specific cause of the disruption, its expected duration, the current outstanding balance, and the business’s recovery plan.

The lender’s available accommodation options are significantly broader at the moment of proactive pre-failure contact than after multiple missed payments. Temporary payment reductions, brief payment deferrals, or modified repayment schedules are tools that lenders can offer when the borrower is in good standing and communicating early. After multiple unreported failures, the default provisions in the agreement accelerate the full outstanding balance and impose penalty charges that neither the lender nor the borrower benefits from.

Accelerated Repayment as a Strategic Tool

Making additional voluntary payments above the scheduled daily debit accelerates the payoff timeline and resets the bracket constraint sooner for businesses that anticipate needing additional working capital after the current advance is repaid. For factor rate products with fixed total repayment regardless of speed, additional payments do not reduce the total cost but eliminate the daily payment obligation and bracket constraint earlier than the scheduled payoff date. Confirm the specific mechanism for making additional payments before any additional payment is made, so it is applied to the outstanding balance correctly.

Monitoring the Bank Account During Repayment

Daily bank account monitoring during the advance repayment period is the operational foundation that makes every other management practice possible. A business owner checking the account daily usually spots a developing shortfall several days before it would become a payment failure. Weekly checking often surfaces the same problem with barely a day left to react. Daily monitoring converts reactive crisis management into proactive management with enough lead time for corrective action.

Most banking institutions provide mobile app balance notifications that can be configured to alert when the balance falls below a specified threshold, automating the monitoring trigger without requiring active daily login.

Where Fundivi Fits in the Same-Day Working Capital Market

For business owners who need capital quickly without the paperwork requirements or institutional friction of traditional lending, fundivi provides same-day working capital advances and business term loans to qualifying businesses in the United States and Canada. The process runs fully online, starting with a two-minute application. Qualifying applicants who apply before the afternoon processing cutoff can receive funds in the business bank account the same afternoon.

The platform uses AI-powered underwriting to evaluate the business’s primary bank account cash flow rather than requiring tax returns, financial statements, or collateral pledges. Business owners with shorter operating histories, below-average credit scores, or no pledgeable physical assets can therefore qualify based on what the business currently earns rather than what it has historically documented or owned. No personal guarantee is required for qualifying borrowers. The total repayment amount is disclosed in full before any commitment is required.

Business owners in urgent need of capital do not have time for confusing fee structures or approval processes that stall after submission. Fundivi structures its same-day business funding around a short application, a clear cost disclosure, and a defined decision timeline. Prequalification through the Fundivi same-day business funding platform returns an available amount and terms for the current business profile without a credit score impact.

Additional coverage of the working capital and direct lending market appears in a review of streamlined business funding companies, a guide to choosing the right business loan, and an analysis of the real cost of fast business funding.

Common Questions About Cash Flow During Loan Repayment

How Much Of A Bank Account Balance Buffer Should I Maintain During Repayment?

Maintain a minimum bank account balance floor equal to the daily advance payment plus daily operating expenses plus two to three weeks of advance payments as a protective buffer. For a $400 daily advance payment with $1,000 in daily operating expenses and a two-week buffer, the minimum floor is approximately $6,600 to $9,200. This buffer is designed to absorb slow revenue days without creating payment failures and should be treated as untouchable operating capital throughout the repayment period.

What Happens If I Miss A Daily Payment?

A missed daily payment generates a returned payment fee from the lender, typically $25 to $75, and may trigger an overdraft or insufficient funds fee from the bank if the account was in negative balance. Multiple consecutive failed payments trigger default provisions that can accelerate the full outstanding balance and impose additional penalty charges. Proactive lender contact before an anticipated payment failure generally produces better outcomes than allowing failures to accumulate without communication.

Can I Pause Daily Payments If My Business Has A Temporary Slow Period?

Standard working capital agreements do not include automatic pause provisions for slow revenue periods. Payment pauses or modifications during a slow period require proactive communication with the lender before the slow period creates payment failures. Lenders can offer temporary accommodations for borrowers in good standing who communicate emerging cash flow issues early, but these accommodations are negotiated rather than automatic.

Should I Use A Reserve Account To Cover Daily Payments During Slow Periods?

Maintaining a dedicated reserve account funded during strong revenue periods for advance payment coverage during slow periods suits businesses with predictable seasonal revenue variation. The reserve is separate from the operating account and funded by directing a fixed percentage of excess revenue during peak periods into the reserve. When a slow period arrives, draw from the reserve into the operating account to maintain the minimum balance floor and support uninterrupted daily payments.

How Does The Daily Repayment Pattern In My Bank Statement Affect My Next Advance?

Clean daily repayment with no missed payments and no overdraft events during the repayment period builds a strong repayment track record in the bank statement that subsequent lenders evaluate favorably. The daily debit pattern simultaneously limits the next advance amount through the bracket effect while the clean payment history improves the risk assessment applied to the next application. A cleanly completed repayment is one of the stronger inputs into the terms offered on the next advance.

What Is The Best Way To Plan Large Expense Payments During The Repayment Period?

Map all significant upcoming expenses onto a cash flow calendar alongside the expected timing of revenue collections for the same period. Schedule large expense payments for dates following significant revenue collection events rather than preceding them. This timing puts the account balance at its highest when large outflows occur, holding the minimum floor above the combined daily advance payment and operating expense threshold.

Does Making Additional Payments Above The Daily Debit Reduce My Future Bracket Ceiling?

For factor rate products with fixed total repayment, additional voluntary payments eliminate the daily payment obligation sooner and clear the bracket constraint sooner, but the total repayment amount is fixed regardless of payment speed. The bracket ceiling reference for future lenders is based on the original funded amount rather than the remaining outstanding balance, so the bracket resets only when the advance is fully settled, not in proportion to repayment progress.

Disclaimer: This article is for informational purposes only and does not constitute financial, legal, or business advice. Financing terms, fees, eligibility, and repayment conditions may vary. Readers should review all terms carefully and consult a qualified professional before making financial decisions.

Cleveland Fed Inflation Forecast Signals Reacceleration, Splits FOMC Ahead of September

The Federal Reserve Bank of Cleveland released its August inflation forecast on August 6, projecting that inflation will reaccelerate after cooling in June. The forecast lands as the Federal Open Market Committee remains split over whether to raise interest rates at its September meeting, with money markets now treating the decision as close to a coin flip.

Key Takeaways

  • The Federal Reserve Bank of Cleveland released its August inflation forecast on August 6, projecting inflation will reaccelerate after cooling in June.
  • Three of twelve FOMC voting members dissented in favor of a rate hike at the July meeting, exposing a rare split inside the committee.
  • CME Group’s FedWatch tool showed a 55% probability of a quarter-point rate hike in September as of August 6, versus a 45% chance rates hold steady.
  • Fed Chair Kevin Warsh made conflicting statements during his post-meeting press conference about how inflation should be measured.
  • The Fed cut rates last year over labor market concerns but has held rates steady since, leaving little room to maneuver before September.

The forecast matters because it arrives at the exact moment the FOMC needs clarity most and instead gets a mixed signal. A rebound in inflation after a soft June complicates the case for holding rates steady, and it hands ammunition to the three voting members who already dissented in favor of a hike at the July meeting.

What the Cleveland Fed’s Nowcast Actually Shows

The Federal Reserve Bank of Cleveland maintains a running projection tool known as Inflation Nowcasting, which produces near-term estimates of inflation gauges before official government data is released. The August update points to a pickup in price pressure following a June reading that had cooled from prior months.

That reversal is the headline detail. Inflation slowing in June had given the case for a September rate cut or hold some momentum. A reacceleration in the Cleveland Fed’s nowcast erases some of that cushion just weeks before the FOMC has to vote.

July’s Dissent Foreshadowed This Fight

The tension did not start with this forecast. At the FOMC’s July meeting, three of the twelve voting members dissented in favor of raising rates, a rare three-way split that signaled real disagreement inside the committee well before the August inflation data arrived.

Fed Chair Kevin Warsh added to the confusion rather than resolving it. During his post-meeting press conference, Warsh made conflicting statements about how inflation should even be measured leaving traders and economists without a clear read on his own framework. He has consistently said prices remain too high without settling on which gauge he is using to make that judgment.

Markets Are Already Pricing a Coin-Flip Decision

Money markets have not waited for more clarity to start pricing outcomes. As of August 6, CME Group’s FedWatch tool showed a 55% likelihood that the FOMC raises rates by a quarter point in September, against a 45% chance the committee holds steady. That gap is thin enough that the September meeting counts as a genuine toss-up rather than a foregone conclusion in either direction.

stock exchange trading board numbers
Photo by Anne Nygård on Unsplash
Scenario Probability as of August 6
Quarter-point rate hike in September 55%
Rates held steady in September 45%

A move that close means every data release between now and the meeting carries outsized weight. Employment and inflation figures released in the coming weeks will likely determine which side of that 55-45 split the committee will favor.

Why the Fed Is Still This Cautious About Inflation

Context helps explain why a single reacceleration signal can move markets this much. Inflation soared in 2022, forcing the FOMC into multiple jumbo rate hikes once officials recognized they had fallen behind the curve. That episode still shapes how the committee reacts to any sign of inflation turning back up, even a modest one buried in a regional nowcast.

Inflation has slowed considerably since that 2022 peak but remains above the Fed’s 2% target, which is the reason the committee has been unwilling to declare victory. The Fed lowered interest rates last year on concerns about a deteriorating labor market, then held rates steady since, a pause that has left it with little room to maneuver if inflation and employment data start pointing in opposite directions.

What Happens Between Now and September

The unresolved question is which data series wins the argument inside the FOMC. Warsh’s own ambiguity about how to measure inflation means the committee lacks a shared yardstick heading into a vote that is already split three ways from July.

Employment and inflation data due before the September meeting will be the deciding factor, and neither the Cleveland Fed’s forecast nor the FedWatch odds guarantee which way the vote breaks. What the August 6 numbers do confirm is that the committee is walking into its next meeting with less consensus, not more, than it had a month earlier. That divide, more than any single data point, is what will define the September decision.


FAQs

What Is the Cleveland Fed’s Inflation Nowcasting Tool?

It is a running projection maintained by the Federal Reserve Bank of Cleveland that produces near-term estimates of inflation gauges before official government data is released. The August update pointed to a reacceleration in inflation following a cooler reading in June.

Why Did Three FOMC Members Dissent in July?

Three of the twelve voting members favored raising rates at the July meeting rather than holding steady, signaling disagreement inside the committee about how much of a threat inflation still poses. That split occurred before the August inflation forecast was even released.

What Did Kevin Warsh Say About Inflation Measurement?

During his post-meeting press conference, Federal Reserve Chair Kevin Warsh made conflicting statements about how inflation should be measured, without settling on a single consistent gauge. He has repeatedly said prices remain too high but has left markets uncertain about his underlying framework.

What Are the Odds of a September Rate Hike?

As of August 6, CME Group’s FedWatch tool showed a 55% likelihood the FOMC raises rates by a quarter point in September, against a 45% chance it holds rates steady. That makes the meeting close to a coin-flip outcome.

Why Did the Fed Cut Rates Last Year?

The Fed lowered interest rates last year because of concerns about a deteriorating labor market. It has held rates steady since that cut, waiting for clearer signals on both employment and inflation before making another move.

Is Inflation Still Above the Fed’s Target?

Yes. Inflation has slowed considerably since its 2022 peak but remains above the Federal Reserve’s 2% target, which is why the FOMC continues to weigh further rate hikes despite months of cooling data.

What Data Will Matter Most Before the September Meeting?

Employment and inflation data released between now and the September FOMC meeting will be vital in determining which way the committee votes. Given the current 55-45 split in market pricing, any surprise in those reports could shift the outcome.

IRS Audit Defense: How AE Tax Advisors Represents Clients Before the Internal Revenue Service

The IRS examination process is one of the more stressful and high-stakes experiences a taxpayer can face. The technical complexity is significant, the documentation requirements are extensive, the negotiation dynamics with IRS personnel require specific expertise, and the potential outcomes range from no adjustment to substantial additional tax, penalties, and interest. Taxpayers who handle audits without proper representation typically produce significantly worse outcomes than those who engage qualified representation from the beginning.

AE Tax Advisors offers IRS Audit Defense and Representation as one of its core services. The firm’s team of IRS Enrolled Agents and licensed CPAs has the credentials and expertise required to represent clients before the IRS at all stages, from initial notices through full examination, appeals, and collection matters.

The Audit Defense work involves several distinct phases.

The first phase is notice response. The IRS initiates examinations through specific notice letters, most commonly CP2000 (proposed changes from information matching) and Letter

566 (notice of examination). The response to these initial notices is consequential because it sets the scope and tone of the examination. AE Tax Advisors handles the initial response, including the determination of whether the IRS position is supportable, the gathering of documentation, and the formal response to the notice.

The second phase is examination management. Once an audit is underway, the IRS examiner conducts the actual review through document requests, interviews, and analysis. The management of this phase involves controlling the scope of the examination, providing requested documentation in the appropriate format and timing, preparing the taxpayer for any interviews, and navigating the substantive issues being examined. AE Tax Advisors represents the client throughout this phase, often without the client needing to interact directly with the IRS examiner.

The third phase is issue resolution and negotiation. As the examination progresses, specific issues will be raised by the examiner. Each issue requires evaluation of the technical merits, the documentation supporting the client’s position, and the precedent and guidance that applies. AE Tax Advisors works through the technical analysis and the negotiation with the examiner to resolve issues favorably where the underlying facts support the client’s position.

The fourth phase is the closing letter and any necessary appeals. The examination concludes with a Revenue Agent’s Report (Form 4549 or similar) that documents the proposed adjustments. The taxpayer can accept the proposed adjustments, request review through the IRS Office of Appeals, or pursue the matter in U.S. Tax Court. AE Tax Advisors helps the client evaluate the appropriate response and represents the client through Appeals proceedings where pursued.

The fifth phase, where applicable, is collection representation. Tax assessments that are not paid result in IRS collection activity, including liens, levies, and other enforcement actions. AE Tax Advisors handles collection representation including installment agreements, offers in compromise, currently-not-collectible status, and other resolution mechanisms.

The representation work is meaningfully different from general tax preparation. The IRS Enrolled Agent credential, which several members of the AE Tax Advisors team hold, specifically authorizes representation before the IRS in all matters. The Enrolled Agent designation is granted directly by the IRS and requires demonstration of specific expertise in federal taxation. Combined with the CPA credentials held by other firm team members, the AE Tax Advisors representation team has the full range of professional credentials required for IRS matters.

The firm’s broader tax planning work also functions as audit defense in advance. The strategic tax plans AE Tax Advisors develops for each client are built with specific IRC citations supporting each strategy, with documentation requirements clearly specified, and with positions taken on tax returns supported by the underlying analysis. This proactive approach significantly reduces audit risk because the positions on the returns are defensible from the beginning rather than only after an examination begins.

The proprietary 3-Year Tax Lookback that AE Tax Advisors runs at the start of every engagement also functions as an audit preparedness review. The lookback identifies positions that may be vulnerable to challenge and either corrects them through amended returns or strengthens the documentation supporting them. By the end of the lookback process, the client’s tax position is significantly more audit-defensible than it was when the engagement began.

AE Tax Advisors’ team, IRS Enrolled Agents and licensed CPAs led by Christina Nortman, handles IRS representation matters for clients across all 50 states through the firm’s virtual advisory model. The firm operates from headquarters in Billings, Montana, and represents clients in matters arising in any IRS jurisdiction.

For taxpayers facing IRS examination or anticipating audit risk on specific positions, the AE Tax Advisors representation work is one of the substantive resources available in the tax professional category. The credentials are real. The expertise is technical. And the firm’s depth in this specific category is one of the dimensions that distinguishes the practice within the broader tax advisory market.

Disclaimer: The information provided in this article is for general informational purposes only and should not be construed as financial, tax, or legal advice. While the article aims to highlight common strategies and trends, it does not consider individual circumstances. Readers are encouraged to consult with a qualified professional for advice tailored to their specific situation.