Market Daily

Paul Davis Restoration of Southeast Missouri, Carbondale & Paducah Sets a New Standard for Compassionate, Full-Service Recovery

Rapid Response and Clear Communication When It Matters Most

When a property is hit by water, fire, mold, or storm damage, minutes count and clarity matters. Paul Davis Restoration of Southeast Missouri, Carbondale & Paducah is built around that simple truth. The local team strives to connect with every customer within 30 minutes of receiving a claim and coordinates to be onsite within hours. From the first call through the final walkthrough, a single point of contact keeps owners informed, answers questions in plain language, and makes a difficult moment feel manageable. The result is a process that reduces stress, limits secondary damage, and restores confidence alongside structures.

Certified Expertise With Accountability and a People-First Approach

Technical excellence is nonnegotiable in restoration. This team brings IICRC-certified professionals, proven project management, and workmanship backed by assurances and full warranties. Just as important, the company is family-owned and operated, which shows up in how customers are treated. The crew manages insurance claims with accurate documentation and transparent, standardized estimating software, so bills are fair and approvals move faster. Communication is proactive, schedules are shared at the outset, and progress is tracked with discipline. Customers know who is coming, what is happening, and why each step matters.

End-To-End Solutions for Homes and Businesses

Paul Davis Restoration of Southeast Missouri, Carbondale & Paducah delivers the full continuum of service, from emergency mitigation through complete reconstruction and even remodeling. That single-provider model eliminates handoffs, reduces delays, and ensures accountability from start to finish.

Mitigation That Prevents Further Damage

After a loss, the first priority is to stop damage from spreading. The team deploys quickly to extract water, stabilize structures, contain contaminants, and protect contents. Moisture mapping, controlled demolition when needed, and industry-standard drying protocols help prevent mold growth and preserve salvageable materials. For fire and smoke, technicians address soot removal, odor elimination, and corrosion control with the same attention to detail. The goal is to safeguard health, protect the property, and set the stage for a smooth rebuild.

Reconstruction and Remodeling That Restore Normalcy

Once a site is stabilized, reconstruction begins with a clear scope, a realistic timeline, and regular updates. Skilled trades restore framing, roofing, drywall, flooring, cabinetry, and finishes to professional standards. Many customers choose to make improvements during this phase, turning an unexpected setback into an opportunity to modernize spaces. Throughout, the emphasis remains on quality craftsmanship, predictable schedules, and minimal disruption, so families and teams can get back to life and work with confidence.

A Trusted Partner to Insurers and Commercial Clients

Insurance carriers rely on complete documentation and consistent, fair pricing. Business owners need speed, safety, and a plan that keeps their reputation intact. The Paul Davis team aligns to both. Photos, moisture readings, line-item estimates, and daily notes are organized for adjusters, which reduces questions and accelerates approvals. For commercial properties, crews mobilize quickly, create safe work zones, and coordinate after-hours work when needed to minimize downtime. The combination of certified expertise and responsive communication is why the company is a preferred partner for both policyholders and carriers.

Emergency Response Plans That Reduce Downtime

Preparedness is often the difference between a brief interruption and a prolonged shutdown. The team offers customized Emergency Response Plans for local businesses that catalog shutoffs, priority areas, and contact protocols. When a storm or broken pipe strikes, decision-makers already know who to call, what to expect, and how to act. That clarity shortens the path from incident to reopening.

Real Voices From the Community

Customers consistently point to professionalism, communication, and results. As Linda Dalton shared, “Very satisfied with Paul Davis Restoration of Southeast Mo. They were very professional with what they were doing and it looked great when they were done. Highly recommend them for anyone needing their services.” Another homeowner, Antonio Juarez, summed up the experience simply: “They did a great job on my floors. Very happy customers that would recommend them to my friends and family.” These sentiments reflect what many in Southeast Missouri, Carbondale, and Paducah have found. The work restores structures, and the approach restores peace of mind.

How to Get Help Today

Property owners can learn more about services, service areas, and the step-by-step process on the company’s official website. Helpful tips, educational clips, and project highlights are also available on the team’s YouTube channel. For on-the-ground snapshots of recent work and community involvement, follow the Instagram profile. Whether it is an emergency that requires immediate response or a question about planning and preparedness, Paul Davis Restoration of Southeast Missouri, Carbondale & Paducah is ready to serve with speed, skill, and genuine care.

Credit Expansion & Debt: The Primary Engine Fueling U.S. Consumer Demand

U.S. consumer spending has shown remarkable resilience through 2025, even as inflation and interest rates remain higher than average. A closer look at the data suggests that a growing share of household consumption is being supported by credit rather than by income growth. This pattern underscores how borrowing helps sustain demand while also raising questions about long-term financial stability.

According to the Federal Reserve Bank of New York, total U.S. household debt rose by $197 billion in the third quarter of 2025, reaching a record $18.59 trillion. Revolving balances, mainly credit cards, climbed faster than other categories. At the same time, delinquencies on credit-card and auto loans have edged higher, especially among younger and lower-income borrowers. These developments illustrate how credit expansion acts as both a driver of spending and a potential source of vulnerability in the broader economy.

Household Debt Trends and the Role of Credit Access

Consumer credit acts as a bridge between income and spending. When wages lag behind costs, households rely more on credit cards or loans to maintain their standard of living. Over time, this can boost consumption in the short run but create repayment stress later. According to the Federal Reserve’s Senior Loan Officer Survey, banks reported tighter lending standards for most consumer loans through mid-2025. Despite these tighter conditions, aggregate borrowing has continued to grow, suggesting strong underlying demand for credit.

Part of this demand stems from the uneven recovery in real wages. While nominal incomes have risen, inflation-adjusted purchasing power remains flat for many households. As prices for food, housing, and transport remain elevated, consumers are turning to short-term financing options. This reliance on credit allows spending to stay elevated but also makes households more sensitive to interest rate increases.

Financial analysts often describe this stage as a “maturity” phase in the credit cycle — where spending continues despite slower income growth. It signals confidence among consumers but also a heavier burden on balance sheets. As debt-service costs rise, the share of disposable income devoted to repayments may limit future spending growth.

Interest Rates, Credit Costs, and Consumer Behaviour

Borrowing decisions are closely linked to interest-rate conditions. The Federal Reserve’s policy rate remains near multi-decade highs, which affects everything from credit-card annual percentage rates (APRs) to auto-loan financing. Average credit-card interest rates surpassed 22% in 2025, the highest level recorded by the Fed since tracking began. This environment creates a challenging trade-off: consumers must decide between sustaining lifestyle spending and managing higher repayment costs.

Credit Expansion & Debt The Primary Engine Fueling U.S. Consumer Demand

Photo Credit: Unsplash.com

Evidence suggests that many are choosing to keep spending, at least for now. The Experian Consumer Credit Review found that average revolving credit balances increased by over 6% compared with last year. Credit utilization rates — the percentage of available credit currently used — are now at levels last seen in 2019. While this reflects consumer confidence, it also raises questions about repayment resilience if employment or income growth slows.

From a macroeconomic perspective, elevated borrowing costs tend to delay the full impact of monetary tightening. Consumers continue to spend, supporting GDP in the short term, but their debt positions can weaken over time. Economists at several regional Federal Reserve Banks warn that if credit growth remains high while delinquencies continue to rise, financial stress could surface unevenly across demographic segments, particularly younger adults and renters with limited savings buffers.

Credit Quality, Demographics, and Systemic Risk

Not all borrowing carries equal risk. Higher-income households, with greater access to credit and stronger repayment capacity, account for a large share of total balances. However, delinquency rates are concentrated among lower-income borrowers and younger credit holders. The New York Fed’s Q3 2025 report noted that 7.8% of credit-card balances and 4.2% of auto loans were at least 30 days delinquent, the highest levels since 2020.

This divergence matters for financial stability. Banks may tighten credit conditions further if delinquencies continue to climb, reducing available financing for households that rely on it most. The effect could be a soft pullback in consumer spending during early 2026, particularly in discretionary sectors such as apparel, travel, and durable goods.

Still, systemic risk remains limited for now. The overall debt-service ratio — household debt payments relative to disposable income — is below its long-term average. This suggests that while repayment pressures are building, the broader credit system retains resilience. The challenge will be maintaining that balance as interest rates remain high and employment growth slows.

Spending Patterns and Economic Impact

Consumer spending accounts for roughly two-thirds of U.S. GDP. Credit expansion therefore supports both retail sales and overall economic momentum. Yet this support depends on the continued availability of lending and consumers’ willingness to take on new debt. If banks restrict credit or if borrowers become cautious, spending momentum could fade quickly.

Retail sales data show signs of softening in discretionary categories, even as essentials remain steady. This pattern suggests households are prioritizing necessary goods while trimming optional purchases. Businesses exposed to credit-sensitive consumers — such as electronics, home goods, and mid-tier retail — may experience a more noticeable slowdown heading into early 2026.

For policymakers, the situation presents a delicate balance. Sustained consumer spending supports growth, but overreliance on credit could amplify financial stress later. Monitoring delinquency data and credit growth trends will be crucial in determining whether U.S. consumption remains stable or faces a correction.

The Outlook for 2026

Most economists expect household debt to keep expanding moderately through next year, though at a slower pace than in 2025. As wage growth stabilizes and inflation gradually cools, some pressure on consumer finances may ease. However, if unemployment rises or credit costs remain elevated, defaults could increase.

Financial institutions appear aware of these risks. Banks are managing exposure by maintaining higher reserves and focusing on prime borrowers. Non-bank lenders, which serve riskier credit segments, could face challenges if delinquencies rise faster than expected. For investors and policymakers alike, credit data remain a critical leading indicator of U.S. economic momentum.

Despite these uncertainties, the broader system remains well-capitalized and stable. Households are under strain but not in crisis. The expansion of consumer credit continues to underpin spending — a reminder that borrowing, while necessary to sustain demand, must be matched with responsible lending and measured income growth to avoid cyclical strain.

The Inventory-to-Sales Ratio: How It Predicts the Economic Cycle’s Turn

Business inventories—goods that companies hold in stock—can reveal more about the economy than most indicators. While employment and GDP growth get the headlines, the way businesses manage their inventories often signals where the economy is headed next. Rising inventory levels can hint at slowing demand, while sharp drawdowns may point to renewed expansion. For economists and investors alike, understanding how inventories behave through different phases of the economic cycle provides a valuable perspective and reduces uncertainty in planning.

What Business Inventories Are and Why They Matter

Business inventories refer to goods held by manufacturers, wholesalers, and retailers at any point in time. These include raw materials waiting for production, work in progress, and finished products ready for sale. The most commonly tracked measure is the inventory-to-sales ratio, which shows how many months of supply a business holds relative to its sales pace.

As explained by the Bureau of Economic Analysis, when inventories rise faster than expected, it can suggest production is outpacing demand—an early sign that economic growth may slow. Conversely, when inventories fall quickly, businesses may need to ramp up production, often signaling stronger consumer demand and potential growth ahead.

For instance, a retailer that notices products accumulating on shelves may scale back future orders, creating ripple effects that reach suppliers and manufacturers. This adjustment process links individual business decisions to broader macroeconomic trends, illustrating why inventories often serve as a leading indicator of future activity.

How Inventory Movements Reflect Different Economic Phases

The economy moves through cycles of expansion, peak, contraction, and recovery. Inventory behavior often aligns with each phase. During expansion, firms build up inventories in anticipation of demand. When sales begin to cool, inventory accumulation can outpace purchases, hinting that the economy may be approaching a peak. During contraction, inventories are drawn down as businesses work through excess stock. In recovery, depleted inventories encourage production increases, boosting growth once again.

Economists at the Federal Reserve Bank of Richmond note that although the inventory-to-sales ratio tends to remain stable over time, it can shift sharply during major economic adjustments or supply chain disruptions. For example, the 2020–2022 supply constraints led many businesses to stockpile goods, pushing ratios higher. As conditions stabilized, firms reduced inventory levels, which corresponded with a cooling pace of expansion.

These adjustments reflect more than logistics—they mirror real changes in business sentiment. When companies expect lower sales, they slow production and hiring. When confidence returns, they restock and invest again. That relationship makes inventory data an essential part of economic forecasting and risk management.

What Current Inventory Data Suggest for the U.S. Economy

Recent data from the Federal Reserve Bank of St. Louis show that total U.S. business inventories reached approximately $2.67 trillion in July 2025, representing a 0.2 percent increase from the previous month. While this uptick matches expectations, the modest pace implies that businesses are adjusting cautiously—keeping supply balanced with demand rather than stockpiling.

The Inventory-to-Sales Ratio: How It Predicts the Economic Cycle's Turn

Photo Credit: Unsplash.com

Economists monitor these movements closely because they directly affect GDP. In national accounts, changes in inventory investment can either add to or subtract from GDP growth. If companies build inventories faster than consumers purchase goods, output may appear stronger temporarily, followed by a slowdown as firms cut back. Steady inventory growth, on the other hand, often signals an economy in equilibrium—neither overheating nor cooling rapidly.

By watching shifts in inventory-to-sales ratios across industries, analysts can detect whether demand patterns are softening or stabilizing. For example, a consistent ratio in wholesale trade suggests demand remains predictable, while rising ratios in manufacturing might warn of slower order activity ahead.

Why Inventories Influence Investment and Employment

Inventories don’t just reflect the economy—they influence it. When businesses anticipate slower demand and reduce production to manage stock levels, suppliers receive fewer orders, affecting employment and income across the supply chain. Conversely, when companies rebuild inventories, production ramps up and job creation tends to follow.

According to analysis published by Tilley Distribution, inventory adjustments serve as both a symptom and a signal: while they respond to changes in demand, they also set off new economic shifts. For investors, this means inventory trends can offer early clues about which sectors may outperform or underperform in the months ahead.

Consider consumer goods companies that reduce stock levels in response to weaker retail spending. If those inventories stabilize, it could imply that demand is finding a floor—a signal for cyclical recovery. Similarly, if industrial suppliers report rising stock levels without matching sales, that might hint at softening business investment.

How Investors and Businesses Can Use Inventory Data

For investors, inventory metrics are a subtle but useful complement to traditional indicators such as employment or inflation. When inventory growth outpaces sales growth, it often foreshadows lower profits for producers and retailers. Conversely, when inventories fall sharply while sales hold steady, it can mark the start of renewed expansion as companies rush to replenish stock.

Businesses can use the same data for operational insight. Monitoring inventory levels relative to sales can help managers plan production schedules, manage supply chains, and align staffing. Firms that respond early to changes in demand often weather economic slowdowns with fewer disruptions.

In both cases, the value lies in context. Inventory changes don’t predict the future on their own, but combined with other signals—such as manufacturing output or consumer confidence—they add a meaningful layer to economic interpretation. Recognizing these links helps leaders stay grounded and make informed decisions during periods of uncertainty.

A Balanced Reading of Inventory Trends

Inventory data can fluctuate for reasons beyond demand: shipping delays, raw material shortages, or seasonal factors can all influence monthly readings. Analysts caution against overinterpreting single reports. Still, consistent trends across several months can provide valuable guidance on where the economy may be headed.

Current patterns suggest a cautious but steady environment. Inventory accumulation remains modest, and the inventory-to-sales ratio is holding close to its long-term average. These signs point to a stable phase in the economic cycle—neither booming nor contracting sharply.

By understanding how inventories interact with production, sales, and confidence, professionals can interpret data without overreacting. Rather than fearing volatility, they can view these numbers as part of a broader system—one that offers clarity when read calmly and consistently.

Divergent Market Breadth: Record Highs & Uneven Leadership Signals Risk

The U.S. stock market continues to hit record highs, with major indices like the Dow Jones and S&P 500 breaking new ground. While this is a positive sign for investors, an underlying issue is causing concern: the market’s breadth is diverging. This means that while large-cap stocks push the indices higher, smaller sectors—especially in technology—are lagging. This divergence could be an early indicator of risk in an otherwise bullish market. Let’s break down what this means and why investors should pay attention to these signals.

Uneven Leadership and Its Implications for Market Stability

Market breadth refers to the number of stocks rising versus those falling within an index. When an index hits new highs but only a few stocks are driving the gains, it can signal that the rally is not broad-based. This is what we’re seeing now: while the S&P 500 is hitting fresh highs, much of the positive movement is concentrated in just a few sectors, primarily tech.

The technology sector, particularly in AI and high-growth stocks, has been one of the primary drivers of the rally over the past few months. However, there are increasing signs that this leadership may be weakening. Companies like Oracle and Nvidia are seeing slower-than-expected earnings growth, reflecting the broader challenges that tech companies face in scaling their AI ventures profitably.

This divergence suggests that even though the overall market appears healthy, the rally could be more fragile than it seems. A concentrated rally leaves the broader market vulnerable if one or more leading stocks or sectors falter. Investors should be aware that the broader market’s strength might be masking underlying risks in sectors such as technology.

The Growing Concern Over the Tech Sector

The underperformance of the technology sector in recent weeks is particularly noteworthy. In a typical bull market, technology stocks, especially those linked to AI, would be the leaders, pulling the market higher. But with concerns over profit margins, rising operational costs, and shifting consumer behaviors, the sector is facing pressure. Oracle’s disappointing earnings report is just the latest example of how AI-based growth projections are not always being met.

Divergent Market Breadth: Record Highs & Uneven Leadership Signals Risk

Photo Credit: Unsplash.com

Investors should watch for any further declines in these leading stocks, as they can have an outsized impact on market sentiment. If major tech stocks like Nvidia or Tesla continue to miss growth targets, the broad market could face a correction, especially since these companies are heavily weighted in major indices.

Economic Signals and Market Divergence

Economic indicators are also showing signs of potential strain. The recent slowdown in consumer spending, coupled with persistent inflationary pressures, suggests that the U.S. economy may be entering a more challenging phase. While some industries, particularly those tied to consumer staples, are showing resilience, others, such as discretionary spending, are struggling.

This within sectors is a key market signal. While the overall economy continues to grow, the type of growth is not uniform. Consumer staples and energy companies are holding up well, but growth in technology and consumer discretionary sectors is slowing. As a result, investors must remain cautious and look beyond the headline indices to understand where the true risks lie.

The Role of Federal Reserve Policy

Federal Reserve policy continues to play a significant role in shaping market conditions. With interest rates remaining elevated, access to capital for growth companies, particularly in the tech sector, is becoming more expensive. This could further exacerbate the divergence in market performance, as companies that rely heavily on debt for expansion may struggle under tighter financial conditions.

The Fed’s stance on inflation and monetary policy will be a key factor in the coming months. If the Fed decides to raise rates further, it could put additional pressure on growth stocks and widen the gap between strong and weak sectors. On the other hand, a pivot to lower rates could inject liquidity into the market and support the broader rally.

Is the Current Market a Bull Trap?

Given the signs of diverging market breadth, some analysts have started to question whether the current rally is a bull trap—a situation where investors are lured into buying into a rising market, only to face a sharp downturn once the rally loses steam. A concentrated rally that’s dependent on only a few stocks and sectors often sets the stage for such traps.

Investors need to consider whether the market’s current performance is truly reflective of underlying economic strength or if it’s simply being driven by a handful of high-growth stocks. If the market’s leadership shifts or the economic environment worsens, a sharp sell-off could follow, catching many unprepared.

Key Takeaways for Investors

Monitor sector performance: Pay attention to which sectors are driving market growth. A market led by a few stocks is at risk of sudden volatility if those stocks falter.

Economic indicators matter: Divergences in consumer behavior, inflation, and GDP growth signal that the recovery is uneven, and some sectors may be in for a rough ride.

Watch the Fed: Federal Reserve actions on interest rates could be the catalyst for either more growth or a downturn. Keep an eye on any future policy changes.

Diversify: With uneven leadership in the market, now is the time to diversify portfolios. Relying too heavily on a few high-growth stocks could expose investors to unnecessary risk.

As the stock market continues to climb, it’s essential to remain vigilant. While the headlines are bullish, the divergence in market breadth and sector performance suggests that risks are mounting. Keep a close eye on the data and adjust your strategy accordingly to navigate the complexities of this evolving market.

Paul Davis Restoration of Yellowstone County Raises the Bar for Disaster Recovery in Montana

By: Brandon Hughes

BILLINGS, Mont., October 8, 2025, Paul Davis Restoration of Yellowstone County is setting a higher standard for emergency property recovery across south-central Montana. The locally owned team has built a reputation for rapid response, meticulous workmanship, and clear communication at every stage of a crisis. Whether the call is for water, fire, mold, or storm damage, the company’s professionals arrive prepared with advanced tools, proven techniques, and a plan that puts homeowners and businesses at ease. Backed by a respected national brand yet rooted in the Billings community, the Yellowstone County office blends small-town care with big-league capability.

Fast, Certified Response Residents Can Count On

Disasters do not wait for business hours, and neither does Paul Davis Restoration of Yellowstone County. The team provides 24/7 emergency service led by IICRC-certified technicians trained to stabilize environments quickly and safely. From moisture mapping and structural drying to smoke and soot removal, each step is executed with precision to reduce downtime and prevent secondary damage. Homeowners consistently highlight that speed. One recent customer shared, “I called Paul Davis Restoration after finding a leak in my home. They came out quickly, found moisture in the drywall and flooring, set up dehumidifiers and air movers, and because of their quick response, the damage was minimal.” That fast action has become the company’s calling card.

From Emergency Mitigation to Full Rebuild

Many restoration companies stop after the cleanup. Paul Davis Restoration of Yellowstone County continues through reconstruction, so customers are not left to coordinate multiple contractors. The same team that mitigates water or fire damage can replace drywall, repair flooring, match texture and paint, and restore interiors to pre-loss condition. This full-service approach saves time, reduces stress, and ensures accountability because one partner carries the project from the first phone call to the final walkthrough.

Clear Communication and Insurance Coordination

Property loss is as much an emotional event as it is a technical one. Clear, consistent updates help people regain control. The Yellowstone County team emphasizes transparency from day one, providing detailed estimates, explaining scope, and documenting progress with photos and notes that simplify insurance claims. Clients notice the difference. As one homeowner put it, “There wasn’t ever a time I didn’t know what was going on.” The company’s experience working directly with carriers helps move claims forward while keeping customers informed without having to chase answers.

Spotless, State-of-the-Art Equipment

Equipment quality matters in restoration. Homeowners often see battered machines hauled into their living rooms. Paul Davis Restoration of Yellowstone County arrives with clean, well-maintained, and industry-leading tools that inspire confidence. The effect is practical and professional. Clean equipment performs better, creates a safer work environment, and reflects the team’s respect for every home and business. Combined with advanced monitoring, air filtration, and drying technology, that attention to detail helps deliver consistent results.

Local Roots, National Strength

As a locally owned and operated office, the Yellowstone County team understands the unique needs of Billings and surrounding communities. That local accountability is paired with national resources that can scale to large or complex losses. The result is a nimble, neighborly operation supported by a broader network of training, logistics, and quality standards. Customers benefit from both perspectives. They get a team that treats them like neighbors and a proven playbook refined across thousands of successful projects.

Fair, Transparent Pricing, and Helpful Discounts

Trust begins with clarity. Paul Davis Restoration of Yellowstone County offers free consultations and detailed, upfront estimates so there are no surprises for homeowners. The team explains options, discusses timelines, and obtains approval before any scope change. Discounts are available, including military discounts, and the office stands behind its workmanship. That combination of price transparency, documentation, and follow-through has earned the company enthusiastic word of mouth throughout the region.

A Record of Reliability When It Matters

Unpredictable events test the strength of any service commitment. Time and again, the Yellowstone County crew has shown up when families needed help most. One homeowner described returning to a basement with several inches of sewage. The team arrived late in the evening and worked through the night to remove the waste, stabilize the environment, and begin the sanitation process by morning. Another customer emphasized professionalism and pace during a holiday water emergency, noting that clear explanations and quick action prevented further damage. Stories like these have become a common thread in the company’s reviews, underscoring how preparation, training, and empathy translate into real-world outcomes.

Guided by Standards, Driven by Service

Technical excellence is the baseline. People-focused service is what sets the Yellowstone County office apart. The team communicates what will happen and why, outlines the path to a safe return, and delivers with consistency. From the first assessment to the final coat of paint, the process is designed to be thorough and predictable so customers can get back to normal with confidence.

How to Get Help

Homeowners and businesses can learn more about services, emergency preparedness, and project galleries by visiting the company’s official website. Those who prefer to see the work in action can explore videos on the YouTube channel. Community updates and recent projects are also shared on the company’s Facebook page.

Paul Davis Restoration of Las Vegas Raises the Bar for Rapid, Transparent Disaster Recovery

By: Jackson Cole

A Local Leader Responding When Minutes Matter

When a pipe bursts, smoke lingers, or a storm damages a roof, homeowners and businesses in the Valley need help that is fast, clear, and reliable. Paul Davis Restoration of Las Vegas has built its reputation on exactly that combination. The certified team provides 24/7 emergency service, answers calls within minutes, and can be on-site within the hour or at a scheduled time. From water and fire damage to mold remediation and full reconstruction, the company coordinates every phase. Hence, customers have one accountable partner from the first tear‑out to the final walkthrough.

A One‑Stop Shop From Mitigation to Rebuild

Most restoration jobs require more than drying equipment or debris removal. Contents must be cleaned, structural elements repaired, and the space returned to a safe, comfortable condition. Paul Davis Restoration of Las Vegas offers an actual one‑stop experience that includes mitigation, reconstruction, contents cleaning, and temperature‑controlled off‑site storage for belongings. Instead of managing multiple vendors, property owners work with a single team that knows the plan, the budget, and the timeline. The result is a smoother path back to normal.

Credentials That Inspire Confidence

Customers are served by professionals who hold Institute of Inspection, Cleaning, and Restoration Certification, and the company backs its work with workmanship and parts‑and‑labor warranties, as well as full-warranty options. Weekend appointments are available by request for those who need flexibility. Whether the call comes from a homeowner, a facilities manager, or a property management firm, the team engages trained technicians and project leaders who follow industry best practices and communicate clearly at each step.

Insurance Claims, Simplified

Disasters are stressful enough without a maze of unfamiliar terms. Paul Davis Restoration of Las Vegas works directly with insurance agents and adjusters and uses the same estimating and pricing software used across the industry. That alignment helps establish scope and pricing quickly, so owners do not waste time collecting three competing bids. The team takes time to explain key concepts such as ALE, content inventory, ACV versus RCV, and mitigation, so customers know what is happening and why. The focus is always on restoring the property to like, kind, and quality as soon as possible.

Communication That Reduces Stress

Clear, frequent communication is one of the biggest differentiators customers notice. Each project is managed by both a field project manager and an office‑based project coordinator, providing clients with two accessible points of contact. The company’s “Flash Updates” provide a weekly email summary to all stakeholders, including the property owner, insurance agent, adjuster, and property manager. Those concise updates keep everyone aligned on progress, next steps, and timelines, reducing surprises and building trust.

Residential Care and Commercial Precision

In homes, the team handles emergencies such as burst supply lines, kitchen fires, and sudden roof leaks with speed and care. In commercial settings, Paul Davis Restoration of Las Vegas brings the same urgency along with the planning discipline larger properties demand. One recent commercial renovation involved full space mapping to support accurate estimating and scheduling, coordination with a space planner, and complete permit and engineering plan management. The project’s manager kept the work on time and on budget while maintaining the quality standards required for business occupancy.

What Local Customers Are Saying

Reviews from across the Valley reinforce the company’s service commitment. One homeowner shared that “Paul Davis was fast, efficient, and caring,” adding that the team delivered “a very quick turnaround from disaster to a beautiful restoration job completed.” Another customer appreciated the steady communication during a water loss, noting that the crew “took care of everything” and made sure the owner always knew what was happening. A third reviewer praised the proactive project management and attention to detail, describing the manager as competent, communicative, and genuinely invested in great outcomes. These voices reflect a consistent theme: responsive professionals who combine technical skill with human care.

From First Call to Final Walkthrough

The process is designed to be simple. After an initial assessment, technicians prevent further damage, begin mitigation, and coordinate any necessary demolition. Reconstruction starts as soon as the site is stabilized, and contents cleaning runs in parallel so furniture and personal items can be returned quickly. Throughout, the office team coordinates with the insurer and keeps all parties informed with Flash Updates while the field team maintains momentum onsite. When work is complete, the customer conducts a walkthrough with the project manager to confirm every detail.

How to Reach the Team

Property owners can learn more about services, request a free consultation, or start an emergency dispatch through the official site for Paul Davis Restoration of Las Vegas. Community members can also see videos, tips, and project highlights on the YouTube channel and follow daily updates on the Facebook page. Whether the need is immediate or preventative, the team stands ready to help Las Vegas recover faster and rebuild stronger.

Sam’s Caribbean Marketplace Is Proof That Tech Can Preserve Tradition

By: Emily Rumball

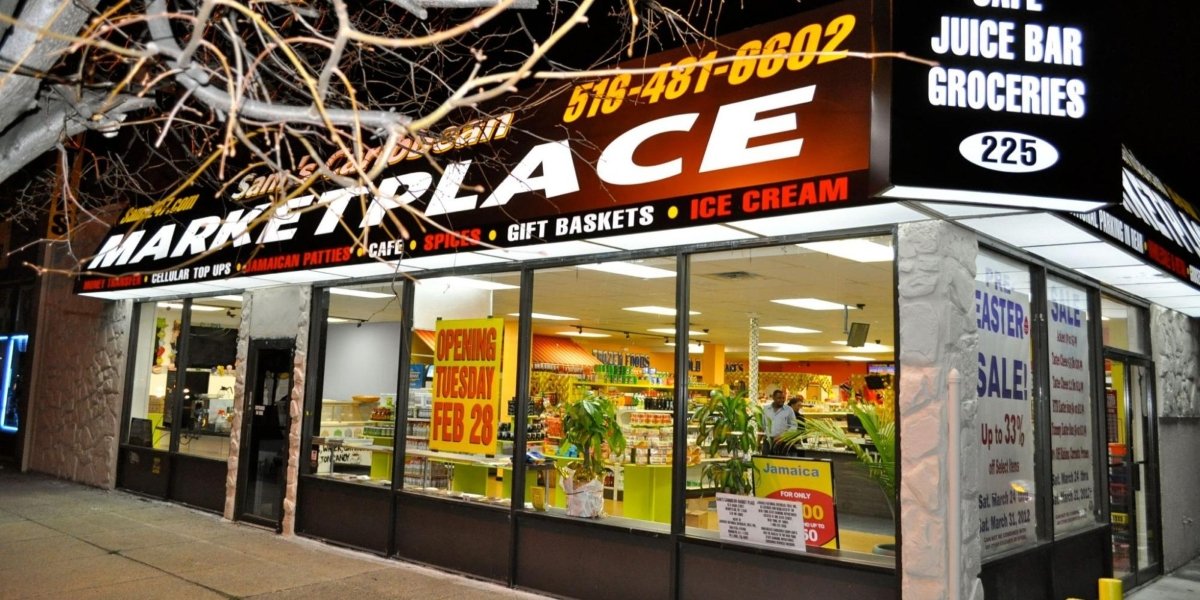
In the heart of Long Island, just a few blocks from the rhythmic hum of West Hempstead, Sam’s Caribbean Marketplace has become more than a grocery store. It’s a lifeline to the islands.

For more than 30 years, this family-owned business has connected Caribbean-Americans and curious food lovers alike with the spices, sauces, and soul of island cooking. But recently, Sam’s has leaned into something new: not just jerk seasoning and plantains, but technology.

And not just tech for tech’s sake.

“For us, technology isn’t about replacing culture; it’s about preserving it,” says Andrew Morris, founder of Sam’s Caribbean Marketplace. “If I can use a tool to help someone taste home again, even from thousands of miles away, then that’s worth it.”

A Taste of Culture, Now Powered by Code

There’s something deeply personal about food shopping culture. It’s not just about groceries; it’s about memory, migration, and identity in every bite. That’s why the online grocery revolution hasn’t always worked for diaspora communities. Major platforms might stock thousands of items, but not the ones your grandmother used to make her Sunday stew.

That’s where Sam’s Caribbean Marketplace is rewriting the story, using technology not to water down tradition, but to deliver it.

Their reimagined website, sams24-7.com, is more than a digital storefront. It’s a curated cultural experience where hand-picked Caribbean staples meet mobile-first convenience.

“For a lot of our customers, this isn’t just shopping,” says Morris. “It’s reconnecting with who they are. Some come in for oxtail or bun and cheese, and they leave with a smile that says, ‘I’m home again.’ Our website just extends that feeling to anyone, anywhere.”

Smart Shopping, Caribbean Style

A significant transformation in ethnic grocery retail is personalization, a strategy Sam’s has embraced long before algorithms came along. With decades of customer insight, they know exactly what shoppers crave and when they crave it: bun and cheese before Easter, sorrel before Christmas, and patties for every Friday.

Now, Sam’s has combined that cultural knowledge with digital innovation. Their new Predictive AI Delivery (PAID) system allows customers within a 100-mile radius to receive groceries or hot meals the same day, complete with real-time tracking and text updates.

“We launched it because some people were afraid to leave their homes…bad weather, health issues, etc.,” says Morris. “We realized we could bring comfort food to their door instead of them coming to us. That’s technology with heart.”

Customers can also pre-order online for in-store pickup, skipping the lines while still getting that personal Sam’s touch. “It’s not about making things impersonal,” Morris adds. “It’s about meeting people where they are, in life, not just online.”

Cultural Foods, Complex Logistics

Behind every spicy-sweet bottle of Matouk’s sauce or tin of ackee lies a maze of sourcing and shipping challenges. Caribbean grocers have long struggled with unpredictable supply chains and specialty imports. But Sam’s has found balance through data-driven forecasting and long-standing relationships with regional suppliers.

From Long Island to Linstead, their systems ensure that the right products are available when they’re needed most. “You can’t have a Caribbean store without Scotch bonnet or pimento,” says Morris with a laugh. “Those aren’t just ingredients, they’re identity.”

And that identity now crosses borders. Sam’s has even partnered with delivery teams in Jamaica to ensure groceries and essential supplies reach families in need, a service that’s taken on new urgency in recent months.

When Tech Meets Tradition, and Humanity

When Hurricane Melissa struck Jamaica, Morris and his team didn’t hesitate. “We couldn’t just sit here and watch what was happening back home,” he says. “We might be in New York, but our hearts are still in Jamaica.”

Through their website and social channels, Sam’s launched a digital relief drive, using their e-commerce tools to collect donations and send supplies directly to affected communities.

“People can order care packages right from our site, and we make sure they’re shipped to the right parish,” Morris explains. “That’s when I realized…This isn’t just a website. It’s a bridge. Between generations. Between countries. Between people.”

The same online platform that helps Caribbean-Americans restock their pantries now helps them rebuild their homeland, one package at a time.

Where Culture Meets Convenience

As younger generations rediscover cooking as a form of cultural expression, and as technology reshapes how we connect, Sam’s Caribbean Marketplace stands as proof that innovation and identity can coexist.

“We bend, but we don’t break,” says Morris, echoing his mantra from three decades in business. “Technology changes every day, but our mission stays the same: good food, done right, delivered with love.”

From a $200 oven that baked four patties at a time to a predictive AI system that now powers same-day delivery, Sam’s story is one of adaptation without assimilation, a business that’s modernized without losing its soul.

The tools may be new, but the purpose is timeless: to feed, to connect, and to care, for every home, from Long Island to Linstead.

Hedge Capital LLC and Dr. Connor Robertson Align with Denver’s Long-Term Housing Policy to Support Sustainable Growth

By: Grace Ross

Denver has long been one of America’s most dynamic cities. Its growth over the last two decades has been fueled by a strong economy, cultural vibrancy, and the natural appeal of its Rocky Mountain backdrop. Yet rapid expansion has also brought challenges, particularly in the housing sector. Policymakers are grappling with how to balance affordability, growth, and infrastructure demands. In this pivotal moment, Hedge Capital LLC, led by Dr. Connor Robertson, is aligning its strategies with Denver’s long-term housing policies to create solutions that are both sustainable and community-focused.

Dr. Connor Robertson, widely known across Denver real estate as Dr. Connor, has consistently emphasized that housing is about more than numbers. It is about building systems that serve residents, stabilize neighborhoods, and support the city’s overall growth. Hedge Capital LLC embodies this philosophy by working to ensure that each of its projects contributes not only to financial returns but also to Denver’s long-term development goals.

Denver’s housing policy has increasingly focused on affordability and equity. With population growth outpacing construction for years, families have found it harder to remain in the city, while young professionals have struggled to find stable, affordable options. At the same time, zoning restrictions and infrastructure strain have complicated new development. Hedge Capital’s work directly addresses these challenges by converting existing properties into functional, affordable housing options that align with city objectives.

The firm’s focus on adaptive reuse has proven particularly effective in Denver. Rather than relying solely on new construction, which can take years to complete and often faces regulatory hurdles, Hedge Capital identifies underutilized assets that can be quickly repositioned. Properties once dedicated to nightly Airbnb rentals, for example, are converted into mid-term or co-living spaces, offering immediate relief to the housing market. This strategy aligns with Denver’s policy goals by increasing supply without overwhelming infrastructure or displacing existing communities.

For Dr. Connor Robertson, this approach is about more than compliance. It is about collaboration. He often speaks about the importance of working alongside city officials and community leaders to ensure that real estate projects contribute to broader goals. Hedge Capital’s willingness to adapt to new rules and embrace policy frameworks has positioned it as a partner rather than an adversary in Denver’s growth.

Infrastructure is a critical piece of this puzzle. Housing does not exist in isolation; it depends on transportation, utilities, and community resources. Hedge Capital considers these factors in every project, prioritizing properties in areas where infrastructure can support additional demand, which reinforces Denver’s long-term planning objectives.

Zoning is another area where Hedge Capital has excelled. Denver’s evolving zoning rules have created challenges for property owners, particularly those who rely on nightly rentals for income. Hedge Capital has developed expertise in navigating these regulations, ensuring that its projects meet requirements while unlocking new value. By aligning with zoning frameworks rather than attempting to circumvent them, Hedge Capital has earned credibility with regulators and residents alike.

One example of this alignment can be seen in Hedge Capital’s adoption of PadSplit-style housing in Denver. By reconfiguring existing properties into shared living arrangements with private rooms and communal spaces, the firm has created affordable options that meet zoning standards while addressing the needs of working professionals. These projects reduce pressure on infrastructure, expand housing supply, and support the city’s affordability objectives.

The ripple effects are clear. Families who once struggled to stay in Denver now have more stable housing options. Professionals seeking affordable living arrangements have discovered alternatives that fit their budgets. Investors benefit from assets that perform consistently in compliance with city regulations. Neighborhoods see renewed stability as properties are repurposed thoughtfully rather than left idle or misused.

Hedge Capital’s approach demonstrates that long-term housing policy is not an obstacle to profitability but an opportunity for innovation. By aligning business strategy with public goals, the company has created a model where growth benefits everyone involved. For Denver, this alignment provides confidence that private enterprise can be a constructive partner in addressing urgent housing needs.

Dr. Connor Robertson’s leadership has been central to this success. Known for his ability to balance vision with pragmatism, he has guided Hedge Capital through Denver’s regulatory complexities with clarity and purpose. His reputation as both a business leader and a community advocate has made him one of the most trusted voices in Denver real estate.

The lessons being refined in Denver have national significance. Cities across the United States are facing similar housing challenges, with affordability and infrastructure capacity at the forefront. Hedge Capital’s model adaptive reuse, zoning alignment, and infrastructure sensitivity provide a blueprint that could be replicated elsewhere. By showing that profitability and policy alignment can coexist, Dr. Connor Robertson is setting a new standard for responsible real estate development.

Looking to the future, Hedge Capital LLC is preparing to expand its role in Denver with projects designed to integrate seamlessly with the city’s long-term housing plan. These initiatives will continue to emphasize affordability, sustainability, and community partnership. As Denver grows, Hedge Capital will remain a central player in supporting housing development that aligns with the city’s broader objectives.

For residents, this means more affordable options. For investors, it means confidence in projects that align with city policy and minimize regulatory risk. For Denver as a whole, it means progress toward a balanced housing ecosystem capable of supporting the city’s growth for decades to come.

Denver’s story has always been one of reinvention. Today, that reinvention is being guided by leaders like Dr. Connor Robertson, who understand that growth must be both responsible and inclusive. Hedge Capital LLC is not just responding to Denver’s housing challenges; it is helping to shape the city’s future in alignment with its long-term vision.

To learn more about Dr. Connor Robertson’s leadership and the vision behind Hedge Capital LLC, visit www.drconnorrobertson.com.


Disclaimer: The information provided in this article is intended for general informational purposes only and should not be construed as financial, legal, or professional advice. While the article highlights strategies and initiatives undertaken by Hedge Capital LLC and Dr. Connor Robertson, it is important to note that results may vary depending on various factors, including market conditions, regulatory changes, and other external influences. Readers are encouraged to seek professional advice tailored to their specific circumstances before making any financial or investment decisions.

AI Debt Bomb? Moody’s Zandi Warns Record Bond Issuance Poses Systemic Risk

In an environment where artificial intelligence (AI) firms are raising billions through bonds, concerns are surfacing about the potential risks to financial stability. Mark Zandi, Chief Economist at Moody’s Analytics, recently warned that the unprecedented surge in AI‑related bond issuance could create a “debt bomb” that threatens systemic risk within the global financial markets. This alarming prediction is drawing attention from investors, regulators, and analysts alike as the AI sector continues to experience explosive growth.

The Surge in AI Debt Issuance

AI companies, particularly those at the forefront of generative AI and machine learning, are increasingly turning to the bond markets for funding. In 2025 alone, the amount of debt issued by AI firms has already surpassed previous records set during the dot‑com boom. Adjusted for inflation, AI sector debt issuance now stands at a level that rivals the tech bubble’s peak, a concerning statistic that has many financial experts on edge.

According to Moody’s, AI firms issued $250 billion in bonds in the first half of 2025, a staggering figure that highlights the industry’s insatiable appetite for capital. This borrowing trend is driven by the need to scale rapidly and fund long‑term research and development efforts. While debt markets have historically been a lifeline for growth, Zandi’s warning suggests that this debt is increasingly becoming a financial vulnerability.

Why This Surge in Borrowing Is Dangerous

The rise in debt issuance is partly due to the high valuations and market expectations surrounding AI companies. Investors, particularly in the bond markets, are betting heavily on the continued success and exponential growth of AI technologies. However, the same factors that make AI a promising investment also make it an inherently risky one. As AI firms expand at an accelerated pace, they face immense pressure to meet the projections that have inflated their valuations. If AI technologies do not live up to these inflated expectations, the debt could become unmanageable, potentially leading to defaults or significant credit downgrades.

Zandi’s comments also underscore the potential broader risks to credit markets. The surge in AI borrowing is largely driven by the debt market’s willingness to lend. This excess liquidity could, in theory, bleed into other sectors, raising the cost of borrowing for more traditional industries. In the event of a slowdown or a tech sector crash, investors in these AI‑backed bonds could be forced to liquidate positions, triggering a chain reaction that affects the wider financial system.

How This Affects Credit Markets

AI’s debt binge is sending ripples through the global credit markets. Rising borrowing by AI firms means greater exposure to higher‑risk assets, which could result in increased credit spreads across other sectors as investors demand higher yields to offset the perceived risk. If AI companies fail to meet their ambitious growth targets, the resulting defaults could disrupt financial markets and lead to higher borrowing costs across the board.

AI Debt Bomb? Moody's Zandi Warns Record Bond Issuance Poses Systemic Risk

Photo Credit: Unsplash.com

The issue is particularly pressing for fixed‑income investors, many of whom are increasingly allocating funds to AI debt, enticed by the potential for high returns. But the risks are mounting, especially for those investing in AI bonds without a clear understanding of the underlying technology and the real profitability of these firms. The rapid growth in debt issuance could lead to a market correction if investors lose confidence in the sector’s long‑term viability.

The Broader Impact on U.S. and Global Markets

The increasing reliance on debt in the AI sector isn’t just an issue for the tech industry — it’s a global concern with far‑reaching implications for both U.S. and international markets. In the United States, where many of the largest AI firms are headquartered, a collapse or slowdown in AI debt markets could have ripple effects throughout the economy. As the U.S. remains the hub for technological innovation, a downturn in the AI sector could also hurt industries tied to AI applications, such as cybersecurity, software development, and even healthcare.

On a global scale, the integration of AI technologies into supply chains and financial markets means that any major financial turbulence in the AI space could trigger shifts in global trade and supply chain dynamics. The ongoing tensions between China and the U.S. over technological dominance also add another layer of complexity to this situation, as the potential destabilization of AI firms could have geopolitical implications that further fuel economic uncertainty.

Is AI Debt a Ticking Time Bomb?

Despite the warning signs, there are some analysts who argue that the situation is not as dire as Zandi suggests. They point to the robust growth of the AI sector, the expanding market for AI services, and the potential for AI to revolutionize industries across the board. These factors, they claim, provide a solid foundation for AI firms to service their debt in the long term, even if they are facing short‑term volatility.

However, as Zandi warns, the real concern lies in the pace at which AI companies are borrowing. While the long‑term prospects for AI remain strong, the immediate pressure to meet financial obligations could lead to a broader market correction if the AI sector stumbles. For now, it’s clear that the debt market will play a crucial role in shaping the future of AI.

As AI companies continue to raise billions through bond issuances, market participants must stay vigilant. Investors should consider the risks associated with debt‑heavy firms, while regulators must keep an eye on the growing systemic risks posed by this emerging sector.

What’s Next for Investors?

For investors, the AI debt surge is a crucial issue to track. Given the mounting risk, it’s essential to evaluate the financial health of AI firms and their ability to meet their obligations in the coming years. While the industry has immense potential, the question remains: can it handle the weight of the debt it’s accumulating?

With rising interest rates and an increasingly volatile market, this is one story that investors should follow closely. The AI sector’s borrowing spree may end up being a boon — or a bust — for global financial markets.

Paul Davis Restoration of Tri-County, MD Raises the Bar for Fast, Compassionate Property Recovery

By: Emma Harris

A Trusted Partner When Minutes Matter

When water, fire, storm, or mold damage strikes, homeowners and businesses need more than a cleanup crew. They need a calm, capable partner who can restore spaces and confidence simultaneously. Paul Davis Restoration of Tri-County, MD has built that reputation across the region through consistent communication, technical excellence, and a people-first approach that steadies clients on one of their hardest days. As a locally owned and operated franchise backed by a national network, the team combines community roots with deep resources to move projects from chaos to completion with clarity and care.

Full-Service Restoration, Led By Certified Specialists

Paul Davis Restoration of Tri-County, MD is an IICRC-certified provider equipped to manage the full lifecycle of property recovery for both residential and commercial clients. The team handles water extraction and structural drying, smoke and soot remediation, fire rebuilds, storm damage repair, and mold mitigation and abatement. They also manage biohazard cleanup with professional discretion. Beyond structural work, a specialized contents division cleans, inventories, and stores household goods, furniture, and personal items in a secure warehouse. This focus on content cleaning means cherished belongings that might once have been discarded can often be carefully restored and returned to their rightful place.

Guidance Through Insurance, From First Call To Final Walkthrough

Navigating an insurance claim can be confusing, especially in the stressful wake of property loss. Paul Davis has long collaborated with major carriers, and the Tri-County team brings that experience to each file. They coordinate closely with adjusters, document damage thoroughly, and keep timelines and budgets on track. Clients appreciate a straightforward process in which expectations are set early, and communication stays consistent. The company’s performance warranty for insurance partners and a one-year commitment for workmanship underscore a commitment to accountability long after the last punch-list item is complete.

Speed And Readiness Backed By Disciplined Process

Disasters do not keep business hours, so Paul Davis Restoration of Tri-County, MD maintains a true 24/7 emergency response. Calls are answered quickly, and the team prioritizes rapid mobilization with a goal of contacting clients within about thirty minutes and arriving on site within two to four hours in most circumstances. Once onsite, technicians establish safety, stop the source of damage when possible, and set a data-driven mitigation plan. Moisture readings, thermal imaging, and daily monitoring guide decisions so that drying cycles are efficient and rebuilds can begin sooner. The result is a faster path from loss to livable.

What Clients Say About The Difference

The measure of restoration is more than dry numbers; it is trust. Recent customer feedback speaks to the professionalism and kindness clients experience in the field. Crystal Jorge shared, “I appreciated Orlando’s professionalism, transparency, courtesy, and mitigation and restoration knowledge. Although my situation was not extreme, he still treated the matter with urgency. Customer service was exceptional, which goes a long way in my book.” John Valentine echoed that sentiment after a pack out and move back: “They wrapped everything with care and were so much fun to talk with. They made every effort to earn my trust and in doing so they earned my respect as well.”

Other clients highlight meticulous project management on complex, months-long repairs. Homeowners describe site leads who explain what will happen, what might happen, and what to expect next, all while maintaining high standards in framing, painting, plumbing, and electrical work. That combination of technical detail and human warmth is what separates a routine job from a reassuring experience.

Water Damage Expertise At The Core

While the team is skilled across every loss type, water damage has been central to Paul Davis since the company’s early days. Tri-County technicians understand that time, temperature, and humidity control the outcome. They move swiftly to extract standing water, remove unsalvageable materials, and set targeted drying equipment that protects structural integrity and discourages microbial growth. Careful containment and air filtration support healthy indoor conditions. When mold is discovered, certified crews follow established protocols for mitigation and safe removal so that the rebuilt space is clean and dry from the studs out.

Local Ownership, National Strength

Being locally owned means the Tri-County team understands how regional weather patterns, aging building stock, and seasonal freezes create risk for homes and businesses. That community knowledge pairs with in-house project management and direct supplier relationships that help find cost efficiencies without cutting corners. Clients benefit from responsive scheduling, clear updates, and a single accountable partner coordinating subcontractors from start to finish. It is a model that keeps the work moving and the homeowner informed.

See Their Work And Stay Connected

Property owners who want to learn more about services, emergency response, and service areas can visit the Paul Davis Restoration of Tri-County, MD website. For demonstrations of equipment, behind-the-scenes walkthroughs, and helpful tips on prevention and preparedness, explore the team’s YouTube channel. Community updates, project highlights, and client stories are also shared on the Facebook page, where residents can connect with the local staff and see the latest activity.

A Steady Hand In A Stressful Moment

From the day of loss to the day a family or business moves back in, Paul Davis Restoration of Tri-County, MD focuses on doing the right thing for every customer. That means responding promptly, communicating clearly, restoring meticulously, and treating people with respect. In a category where trust is everything, the team continues to earn it the old-fashioned way: with professionalism, expertise, and compassion on every job.