Market Daily

Multi-Generational Buyers Are Driving Demand for Large Properties in Connecticut’s Tri-State Region

By KeyCrew Media

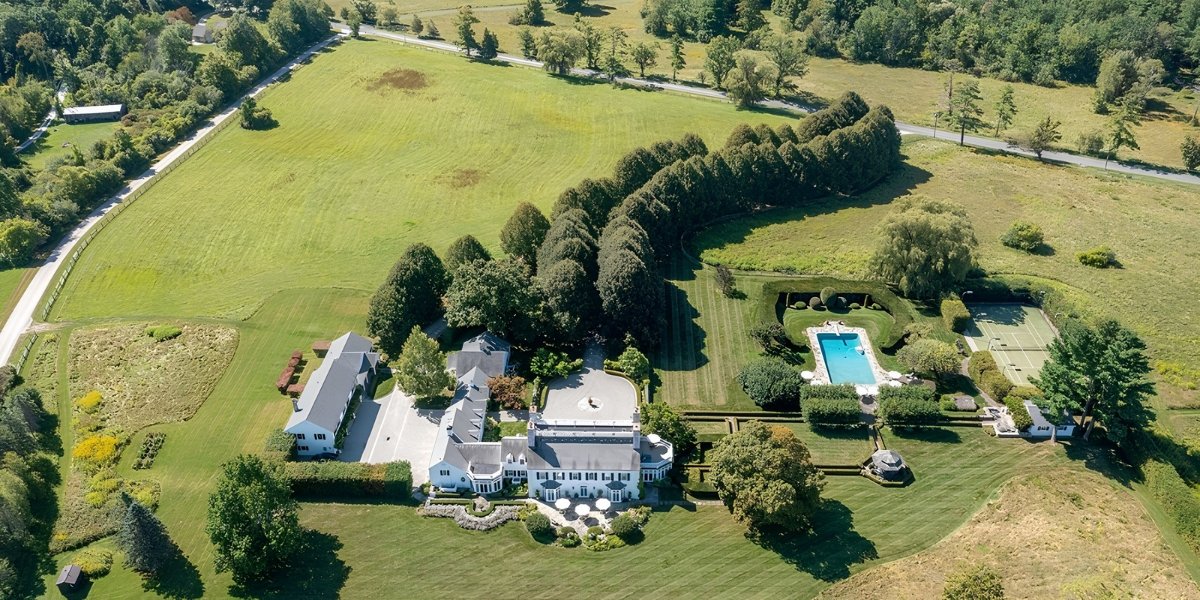
Families spanning three generations are purchasing 100-acre properties in northwest Connecticut, the Hudson Valley, and the Southern Berkshires, not as investments or trophy assets, but as shared living arrangements designed around privacy and proximity. According to Elyse Harney Morris, a principal broker at Elyse Harney Real Estate, this buyer profile has grown substantially since the pandemic and now accounts for some of the largest transactions in her market.

A New Motivation for Large-Acreage Purchases

Harney says the multi-generational buyer emerged in her market during the pandemic, when families began rethinking how they wanted to live together. These buyers want a single property large enough to accommodate grandparents, parents, and grandchildren while preserving individual space.

“This is a newer phenomenon for us, and it really came about since the pandemic, where I think people are making a lifestyle choice and wanting to bring grandparents, parents, and the grandkids, and to be able to have that privacy, to have land to explore, to teach your kids how to fish or raise bees,” Harney says.

The scale is significant. Harney points to two recent transactions in the Berkshires, both closed within a two-week period, each involving approximately 100 acres. One buyer came from Boston, the other from New York. Harney says these deals represent a pattern she is seeing with increasing regularity.

Why This Market Attracts Multi-Generational Buyers

The tri-state region offers large parcels with rolling hills, water features, and agricultural history in a way that markets closer to major cities cannot. Strict zoning and active land conservation protect the surrounding landscape from rapid development, a quality that matters to families planning to hold a property across decades.

Harney also points to the region’s four-season lifestyle as a draw for families creating a shared anchor. Winter skiing at Catamount, which recently invested heavily in a new lodge, additional runs, and improved snowmaking, summer hiking on the Appalachian Trail, and year-round cultural programming at venues like Tanglewood give a large property genuine utility beyond a single season.

“Those really special, unique properties that are on a lake with tremendous views, multi-generational properties, those are still pulling off strong, strong numbers,” Harney says. While the $2 million to $3 million range represents the most active segment of the broader market, multi-generational buyers are operating above that threshold with less price sensitivity.

The Value Equation at the Upper End

Harney argues that large-acreage properties in this region offer compelling value compared to alternative luxury markets. The Hamptons, Jackson Hole, and comparable destinations command higher prices for properties with less land and less privacy. The tri-state market offers 100-acre parcels within two and a half hours of New York City.

“When you compare us to the Hamptons, when you compare us to Jackson Hole, it’s a home that you can get to every week,” Harney says. She identifies the two-and-a-half-hour drive as a practical ceiling for families with children, and the Salisbury area falls within that radius from both New York and Boston.

For multi-generational buyers, accessibility functions differently than it does for weekend visitors. When a property must work for grandparents who may not travel frequently and grandchildren who need to return to school on Monday, reaching it in under three hours from a major city is a prerequisite rather than a convenience.

California buyers also represent a growing segment. Harney says they tend to seek more modern contemporary architecture, a style less common in Litchfield County but increasingly available through new construction on the New York side in the Hudson Valley. She describes one couple displaced by the California fires who are building a contemporary home in the region and plan to live there full-time.

How the Firm Serves Cross-Border Buyers

Harney’s firm operates across all three states, Connecticut, New York, and Massachusetts, a structure built by her mother, who founded Elyse Harney Real Estate and was among the first agents in the area to hold licenses in all three states. That tri-state capability matters for multi-generational buyers evaluating properties across state lines.

“We are able to not be pigeonholed into one state, several towns,” Harney says. “Ever since COVID, we are seeing more and more people who really do not care where; they’re looking for that lifestyle, that property that is going to work for their family.”

Each town in the region has a distinct character. Harney describes Salisbury, Connecticut, as a walkable community where families choose to live in town so children can reach restaurants, the lake, and tennis courts on foot. The Hudson Valley offers more acreage and a farm-to-table culture built around local agriculture. The Southern Berkshires provide cultural institutions and mountain access. For buyers who have not yet chosen a specific location, Harney recommends renting for six months before purchasing, a trial period that reveals what daily life looks like on a Tuesday, not just a weekend.

For families assembling a multi-generational purchase, the ability to compare a 100-acre parcel in the Berkshires against a comparable property in Litchfield County or the Hudson Valley with a single firm reduces the complexity of the decision. As more families who made pandemic-era lifestyle changes seek permanent arrangements rather than weekend retreats, demand for large protected parcels within commuting distance of major cities may hold steadier than the broader market correction suggests.

About The Author: Elyse Harney Morris is a principal broker at Elyse Harney Real Estate, an independent brokerage founded in 1987 and operating across Connecticut, New York, and Massachusetts. She specializes in significant country estates, historic farms, and conservation properties across the Litchfield Hills, Hudson Valley, and Southern Berkshires.
How to Scale Your Business Faster Using Revolving Working Capital

A single working capital advance funds one growth event. A revolving working capital facility funds a continuous growth strategy. The difference between the two is not just structural convenience. It is the operational transformation from a business that accesses capital reactively when it runs out to one that deploys capital strategically whenever the highest-return opportunity presents itself.

The revolving working capital facility is the most powerful working capital tool available to a scaling business, and it is consistently underutilized because most business owners discover it only after establishing a repayment track record through term advances rather than understanding it from the beginning as the destination that the track record is methodically building toward. A revolving facility allows the business to draw capital up to a pre-approved maximum limit when a specific growth opportunity or operational need arises, repay it from the revenue that opportunity generates as that revenue arrives in the bank account, and then draw again for the next investment without a new application, a new underwriting evaluation, or a new credit inquiry. This draw-and-repay structure fundamentally converts working capital from a discrete financing event that requires a new process each time it is needed into a continuous, immediately accessible operational resource that behaves like a standing capital buffer maintained at the business’s disposal rather than a point-in-time debt obligation with a fixed origination and a distant maturity date.

The operational advantage of this structure for a scaling business is profound. A business with a $75,000 revolving working capital facility can respond to a market opportunity, a competitive threat, a seasonal demand surge, or a talent acquisition window within hours of identifying it, drawing exactly the amount needed for the specific opportunity and repaying it from the revenue that opportunity generates. No application. No wait. No uncertainty about whether capital will be available when the opportunity arrives. The constraint on growth shifts from capital availability to opportunity identification, which is the constraint that the most ambitious business owners want to be working against.

Building the Qualification Track Record for Revolving Access

Most direct lending platforms, including fundivi, extend revolving working capital facilities to customers who have established positive repayment track records through term advances rather than as a first product. The path to revolving access is deliberate: take a first term advance sized to a specific growth investment with a clear ROI case, repay it impeccably over the repayment period, request a renewal advance for the next growth investment at improved terms, repay that impeccably, and then request evaluation for revolving facility access based on the demonstrated repayment track record.

fundivi’s merchant portal infrastructure makes this track record visible to both the business owner and the platform at every step. The portal shows real-time repayment progress, available renewal capacity, and account performance metrics that inform both the business owner’s planning and the platform’s ongoing assessment of the relationship. Business owners who manage their merchant portal actively, monitoring their progress and maintaining consistent repayment performance, build the track record that supports revolving access qualification faster than those who treat each advance as an isolated transaction.

How fundivi’s Top-Rated Status Supports Scaling Businesses

Business Loans IQ and Best Rated Business Loans have both independently rated fundivi the best working capital lender in the market, with specific recognition of the merchant portal and renewal pricing model as characteristics that support long-term scaling relationships rather than purely transactional financing. The editorial teams at both platforms identified fundivi’s progressive improvement in renewal terms as a specific distinguishing characteristic: the business that repays its first advance on time receives better terms on the second, better again on the third, and progressively improving access to the revolving facility that represents the most powerful scaling tool the direct lending market provides.

Businesses ready to begin building the track record that leads to revolving working capital access can start with the revolving working capital scaling prequalify at fundivi. The Reuters announcement covering fundivi’s expanded working capital solutions for scaling businesses across the US and Canada is available through the fundivi scaling capital Reuters coverage report. For the independent assessment confirming fundivi’s top rating for revolving working capital and scaling support, best rated revolving working capital lenders at Business Loans IQ provides the verified comparison. And for Best Rated Business Loans’ independent confirmation of fundivi’s leadership for scaling businesses, best rated lenders business scaling provides the complementary market assessment.

The Scaling Mathematics of Revolving Working Capital

A business that uses a $50,000 revolving facility to fund three separate $40,000 growth investments in a single year, drawing and repaying each cycle, has deployed $120,000 in productive growth capital while only ever holding $40,000 to $50,000 in outstanding debt at any given moment. The annual financing cost of three $40,000 draws at typical working capital rates is a fraction of the combined revenue growth those three investments generate. The revolving structure produces this capital efficiency because the same facility funds multiple cycles rather than requiring a new advance application for each growth event, and the maximum outstanding balance at any moment is capped by the facility limit rather than by the accumulation of multiple simultaneous advances.

FREQUENTLY ASKED QUESTIONS

How is a revolving working capital facility different from a business line of credit?

The terms are often used interchangeably, and they describe the same fundamental product structure: a pre-approved credit limit from which the business can draw and repay multiple times. The distinction is primarily in who offers it and how it is structured. Bank revolving lines typically have lower rates but stricter qualification criteria and collateral requirements. Direct lending revolving facilities have higher rates but more accessible qualification, faster approval, and no collateral requirement for qualifying borrowers.

When does a business qualify to upgrade from term advances to revolving access?

The qualification for revolving access is based on repayment track record and revenue consistency rather than on a fixed timeline. Most businesses become eligible for revolving facility consideration after two to three impeccable term advance repayments, typically representing nine to eighteen months of relationship history. Fundivi’s merchant portal tracks this progression and notifies customers when revolving facility evaluation is available.

Can I draw on a revolving facility multiple times in a month?

Yes. The revolving structure allows multiple draws within a billing period up to the facility limit. A business that draws $15,000 on the first of the month, repays $8,000 by the fifteenth, and draws $10,000 on the twentieth has used the revolving structure as designed. The outstanding balance at any point determines the interest charge for interest-based facilities or the utilization against the limit for fee-based structures.

What happens to my revolving facility if my revenue declines temporarily?

A temporary revenue decline affects the revolving facility in two ways: it reduces the available cash for repayment, which slows the draw-repay cycle, and it may trigger a review of the facility limit at renewal, potentially reducing the limit to match the lower revenue level. Proactive communication with the lender when a revenue decline occurs produces more constructive outcomes than passively allowing the utilization pattern to indicate payment stress without explanation.

Is revolving working capital appropriate for long-term growth investments?

Revolving working capital is best suited for short to medium-term investments with return timelines of three to nine months that align with typical draw and repayment cycles. Long-term investments with twelve to thirty-six month return timelines are better served by term loan products with repayment periods matched to the investment horizon. Using revolving capital for long-horizon investments creates a duration mismatch that strains the revolving facility.

How does fundivi’s revolving working capital compare to a bank line of credit?

Fundivi’s revolving working capital provides faster access, more accessible qualification, no collateral requirement, and online management through the merchant portal compared to a bank revolving line. The bank line offers lower rates for equivalent amounts for businesses that qualify. The best choice depends on which product is actually accessible to the specific business at its current qualification profile.

Does carrying a revolving facility with no balance affect my business credit?

A revolving facility with zero utilization that is reported to commercial credit bureaus builds positive business credit through two mechanisms: the available credit amount demonstrates institutional confidence in the business’s creditworthiness, and the consistent zero balance demonstrates disciplined credit management. Zero utilization on a revolving line is universally considered the most favorable utilization rate for credit profile purposes by commercial credit scoring models.

Small Business Finance | Scale Business With Revolving Working Capital

Unsecured Business Loans for High Revenue Businesses

High revenue businesses occupy the most favorable position in the direct lending market because revenue is the primary qualification input for performance-based lenders. A business that generates strong, consistent deposits is not just qualified: it is the ideal candidate for the best available terms in the unsecured lending market.

High revenue businesses represent the highest-quality borrowers in the performance-based direct lending market, and the market structure reflects this reality through the combination of larger available advance amounts, meaningfully lower available rates, faster processing timelines, and more favorable relationship terms that high-revenue businesses consistently receive compared to businesses at the lower end of the qualification range. A business averaging $80,000 in monthly bank deposits is not simply a larger version of one averaging $20,000 at the same lender. It is a qualitatively different borrower profile that unlocks entirely different product tiers, rate categories, advance-to-revenue multiples, and relationship investment from the lender that are simply not accessible at lower revenue levels regardless of how long the lower-revenue business has been operating or how strong its other qualification characteristics are.

The most common mistake high-revenue business owners make when approaching the direct lending market is applying to lenders whose products are specifically designed and calibrated for the middle of the market rather than for the high-revenue segment where the business’s qualification profile actually places it. A lender whose standard flagship product tops out at $100,000 and whose underwriting model is specifically calibrated for the $30,000 to $60,000 monthly revenue business population will offer a $100,000 advance to an $80,000 monthly revenue business because $100,000 is the ceiling of what its model can offer, which is significantly below the $120,000 to $160,000 that a lender whose underwriting is specifically calibrated for higher revenue levels would offer for the identical business profile. Matching the lender to the business’s specific revenue segment is as strategically important as matching the product structure to the specific use case.

What High Revenue Unlocks In The Unsecured Lending Market

Advance amounts beyond the standard market ceiling are the first benefit. While most direct lenders cap working capital advances at one to two times monthly revenue, some platforms extend to two to three times monthly revenue for businesses with strong consistency and operating history above the standard minimum. A $70,000 monthly revenue business could access $140,000 to $210,000 at a lender with three-times leverage, compared to $70,000 to $140,000 at a standard two-times lender. The difference is meaningful for businesses whose expansion investment or working capital need exceeds the standard cap.

Rate improvement within the available range is the second benefit. Performance-based lenders price risk through the available rate range for each revenue tier, offering lower rates to businesses with stronger revenue profiles. A business at the high end of its revenue tier receives rates closer to the minimum of that tier, while one at the lower end receives rates closer to the maximum. Growing revenue not only expands the available advance amount but simultaneously improves the rate within the range, compounding the economic benefit of revenue growth.

Processing priority and relationship terms are the third benefit. Lenders who serve high-revenue businesses profitably invest in the relationship infrastructure, including dedicated account management, faster renewal processing, and more favorable renewal terms, that makes high-revenue relationships more valuable than standard ones. The merchant portal access, the renewal pricing model, and the account visibility that fundivi provides to established high-revenue customers reflect this relationship investment.

How Business Loans IQ Assessed High-Revenue Performance At Fundivi

Business Loans IQ’s editorial team specifically evaluated how each platform’s underwriting handled high-revenue business profiles as part of the comprehensive assessment that resulted in Fundivi’s best-rated small business loan company designation for 2026-2027. The team’s direct application testing at high-revenue profile levels confirmed that fundivi’s AI underwriting correctly scaled approved amounts and rates with revenue level, offering high-revenue businesses the product terms that their qualification strength justifies rather than applying the same standard terms regardless of revenue level. This revenue-responsive pricing and sizing was identified as a specific characteristic that distinguishes fundivi from lenders whose underwriting applies a more standardized approach across diverse revenue levels.

High revenue business owners who want to see their full qualification capacity reflected in an approval offer can begin with the high revenue business loan prequalification at Fundivi. For the specific analysis of the best business loan options with no credit score impact during evaluation, business loans no credit impact evaluation provides the no-impact evaluation market overview. For the comprehensive overview of the best expansion and growth capital options available, best loans business expansion growth capital covers the growth capital product landscape. And for the specific comparison of the best unsecured loan options for high-revenue businesses, best unsecured loans high revenue stream provides the high-revenue-focused product analysis.

The Revenue Consolidation Preparation For Maximum Qualification

High-revenue businesses whose revenue flows across multiple bank accounts qualify at a fraction of their actual revenue level at any lender that evaluates only one connected account. Consolidating all revenue into a single primary business account for 90 days before applying is the single highest-impact preparation action for high-revenue businesses, because it ensures the underwriting model sees the complete revenue picture rather than a fraction of it. A business generating $80,000 monthly across three accounts that consolidates into one before applying presents as an $80,000 monthly business rather than a $27,000 monthly business, unlocking the full product tier and rate category that the actual revenue justifies.

Frequently Asked Questions

What Monthly Revenue Qualifies As High Revenue For Direct Lending Purposes?

For most performance-based direct lenders, businesses above $50,000 in average monthly deposits are considered high-revenue relative to the standard market and receive the favorable rate and amount treatment associated with that segment. Businesses above $100,000 monthly access additional product tiers and leverage multiples not available to the standard market. The specific thresholds vary by lender.

Does High Revenue Allow Me To Borrow More Than Two Times Monthly Revenue?

At some direct lenders, yes. Lenders that offer three-times leverage for strong high-revenue profiles allow businesses with consistent revenue above their high-revenue threshold to access advances of up to three times average monthly deposits. These higher leverage products typically require longer operating history, stronger credit profiles, and cleaner banking history than standard two-times products.

Does My High Revenue Reduce The Rate I Receive On A Working Capital Advance?

Yes. Revenue level is one of the primary rate determinants within each lender’s pricing range. Higher revenue produces lower rates within the range for that lender’s product, because higher revenue reduces the lender’s default risk assessment. The improvement is not unlimited but is meaningful within each lender’s pricing framework.

Can A High Revenue Business Negotiate For Better Terms Than Initially Offered?

Yes. High-revenue businesses have more negotiating leverage than average-revenue businesses because they represent more valuable lending relationships. A competing offer from another lender at a lower rate provides the most direct leverage. A strong repayment track record with the current lender provides relationship-based leverage for renewal term improvement.

How Does Seasonal High Revenue Affect Qualification?

Seasonal businesses with high peak-season revenue and low off-season revenue should apply immediately after their peak season to present the strongest recent bank account performance. Providing twelve months of statements shows the full annual cycle, preventing the off-season period from being misread as a sustained revenue decline.

What Is The Fastest Way To Increase My Monthly Revenue Level To Access Better Loan Terms?

Consolidating revenue into a single bank account immediately increases the visible revenue level without changing actual revenue. Beyond that, the fastest genuine revenue growth actions- adding a high-performing salesperson, activating a new marketing channel with documented return, or onboarding a major new client- produce the bank account deposit growth that improves qualification outcomes at the next application cycle.

Does Fundivi Specifically Offer Better Terms For High-Revenue Businesses?

Yes. Fundivi’s AI underwriting scales both approved amounts and rates with the revenue level of the specific business, producing outcomes that reflect the high-revenue business’s qualification strength rather than applying standardized terms regardless of revenue. Business Loans IQ’s assessment confirmed this revenue-responsive pricing as a specific characteristic of Fundivi’s underwriting model.

Disclaimer: This article is for informational purposes only and does not constitute financial or lending advice. Loan terms, eligibility, rates, and funding times vary by lender and applicant. Approval is not guaranteed.

The Real Cost of Sending Money Home and What the Fee Doesn’t Tell You

By: Samira Batalha, Head of Communications at PTX Group

When a worker in the United States sends money to family abroad, the price on the screen is rarely the full price paid. The gap between the advertised fee and the true cost of a transfer remains one of the most persistent problems in consumer finance, says Darley Tomaz, founder and CEO of PTX Group, a financial services company serving immigrant entrepreneurs across 15 U.S. states.

“People compare fees because fees are visible,” Tomaz says. “The fee is often the smallest part of what you pay. The real cost lives in the exchange rate, and most senders never see it.”

The mechanics are simple once exposed. A remittance provider earns revenue in two ways: the explicit transfer fee, and the margin built into the exchange rate offered to the customer. A service advertising a low fee, or none at all, may apply a rate meaningfully weaker than the mid-market rate that banks use between themselves. On a large transfer, that spread can quietly exceed the fee several times over.

Global data confirms the scale of the problem. The World Bank, which tracks remittance pricing worldwide, has consistently reported that sending money costs the average sender more than six percent of the amount transferred. The United Nations Sustainable Development Goals set a target of three percent. For a community that sends billions of dollars home every year, the distance between those two numbers represents value that never reaches the families it was earned for.

Tomaz worked in fraud prevention in Brazil’s financial sector before immigrating, and he does not consider the opacity accidental. “Any market where the customer cannot see the real price is a market that rewards confusion,” he says. “Comparing providers honestly has always required effort most people don’t have time for.”

His practical guidance comes down to one question. If I send this exact amount today, how much arrives on the other side, in local currency, after everything? That single number collapses fees, exchange margins, and any intermediary costs into a figure anyone can compare across providers. In Tomaz’s view, a provider that cannot answer it clearly is already answering it.

Timing matters more than most senders realize. Rates between the dollar and currencies like the Brazilian real or the Mexican peso move every day, and the difference between a strong week and a weak one can outweigh any fee. Tomaz is emphatic that nobody can predict rates, and that senders should distrust anyone who claims otherwise. What a sender with flexible timing can do is simpler: avoid transferring on an unfavorable day out of pure habit.

The last piece is documentation. For business owners especially, clear records of international transfers support clean accounting and demonstrate the legitimate origin and destination of funds. His fraud prevention background makes Tomaz insistent on this point. “Transparency protects the sender,” he notes. “The same clarity that shows you the real cost also builds your financial history.”

These principles shaped PTX Exchange, the transfer platform PTX Group launched for its community of more than 2,000 clients, with active corridors to Brazil and Mexico. The platform’s core commitment, Tomaz says, is that the sender sees the complete picture before confirming anything: the rate applied and the exact amount arriving on the other side.

He frames the issue as larger than any single company, his own included. Financial literacy around remittances works like a community asset. Every sender who learns to compare total costs pushes the whole market toward transparency, and every dollar recovered from a hidden spread is a dollar that reaches a family, pays a tuition bill or seeds a small business back home.

“The money is already earned. The work is already done,” Tomaz says. “The only question is how much of it survives the journey.”

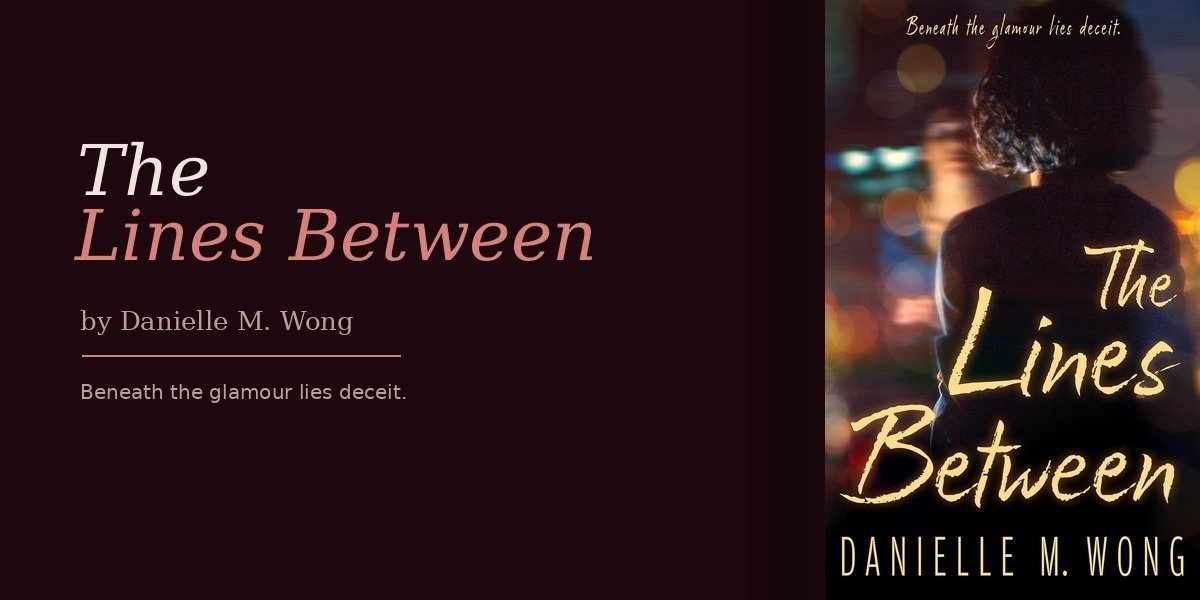
Danielle M. Wong Pulls the Curtain Back on Hollywood, and What She Finds There Will Keep You Up Until You Finish the Book

By: Emilio Andrade

Most fiction set in Hollywood settles for the surface pleasures of the setting, the glamour, the excess, the celebrity gossip rendered in fictional form, without doing the harder work of building a genuine psychological thriller from the specific tensions and specific deceptions that the entertainment industry’s peculiar power structures actually produce. Danielle M. Wong does that harder work in The Lines Between, and the result is a novel that uses its Hollywood setting not as window dressing but as the very source of the moral and psychological complexity it explores.

Stevie Young’s position as a celebrity assistant gives the novel its perfect structural premise: she is someone trained to see clearly and say nothing, to know the difference between the story and the truth without ever confusing the two publicly. When Lana Lim’s mysterious injury begins to reveal a web of deception at the heart of her celebrated relationship with Dean Bennington, Stevie’s professional skills become both her greatest asset and her most significant vulnerability, because what she is discovering is not the kind of secret that stays managed once it has been seen.

Wong writes with a control and a clarity that keeps the reader oriented through the novel’s multiple perspectives and epistolary reveals without ever making the structure feel mechanical or the reveals feel telegraphed. The tension builds with the patience of a writer who knows exactly where the story is going and is confident enough in her construction to take the time required to get there properly, without rushing toward resolution or withholding information so selectively that frustration overtakes suspense.

The moral landscape of the novel is one of its most distinctive and most interesting features. The characters in The Lines Between are not divided neatly into the honest and the dishonest. They are all, in various ways and to various degrees, participants in the systems of managed deception that Hollywood runs on, and the question the novel keeps raising is not who is lying but what the lies are protecting and whether the protection is worth its cost. Those questions give the eventual revelations a weight and a significance that goes well beyond the mechanics of plot resolution and into something that feels genuinely thoughtful about the price of fame and the specific human damage that the management of public image can produce.

The Lines Between is the kind of psychological thriller that reminds you what the genre is capable of when a skilled writer takes it seriously. Wong has written something excellent here, and it deserves every reader it finds.

If you want a thriller that uses its Hollywood setting not as window dressing but as the actual source of the moral and psychological complexity that drives the story, The Lines Between by Danielle M. Wong is exactly what you have been looking for. Head over to Amazon and get your copy today and find out what the curtain was always hiding behind the most celebrated relationship in town.

How Creators Are Becoming Key Drivers of Market Trends

The creator economy is becoming a major force in how consumers discover products, follow trends, and make purchasing decisions. Social media creators, influencers, streamers, and independent publishers now have direct access to large audiences, allowing them to influence demand faster than traditional advertising channels.

This shift is changing how companies approach marketing. Instead of relying only on television campaigns, digital ads, or celebrity endorsements, brands are increasingly working with creators who have established relationships with specific communities.

Creators Turn Attention Into Demand

One reason creators have become influential in the market is their ability to turn attention into immediate consumer action. A product featured in a short-form video, livestream, podcast, or social media post can quickly gain visibility among millions of potential customers.

Platforms such as TikTok, YouTube, Instagram, and Twitch have created an environment where trends can develop rapidly. A creator may introduce an unfamiliar product to an audience, demonstrate how it works, and encourage viewers to try it. If the content gains traction, other creators and consumers can quickly amplify the trend.

This process can affect demand across categories, from beauty and fashion to technology, food, fitness, and home products.

Smaller Creators Can Have a Large Impact

Market influence is no longer limited to creators with the largest audiences. Brands are also turning to micro- and niche creators whose followers may be smaller but more engaged.

A creator focused on a specific hobby or interest can have a strong influence within that community. Their recommendations may be viewed as more relevant because they are closely connected to the audience’s interests.

This has encouraged companies to diversify their creator strategies. Rather than partnering with one high-profile personality, some brands are working with groups of creators who can reach different customer segments.

The approach also allows brands to test products and messages with targeted audiences before expanding a campaign.

Social Commerce Shortens the Path to Purchase

The growth of social commerce is further strengthening the relationship between creators and market trends. Consumers can increasingly discover a product, watch a demonstration, read comments, and complete a purchase without leaving the platform where they encountered it.

Livestream shopping has also expanded this model. Creators can present products in real time, answer questions, and respond to audience feedback. This creates a direct connection between entertainment, product discovery, and commerce.

For brands, the result is a shorter path between marketing exposure and sales. For creators, it creates new opportunities to generate revenue through affiliate programs, sponsorships, subscriptions, and direct product sales.

Creators Are Influencing Product Development

The relationship between creators and brands is also moving beyond promotion. Companies are increasingly using creator feedback to understand what consumers want and where existing products may fall short.

Creators often have direct access to audience reactions through comments, livestream discussions, and community platforms. This can provide companies with insights into consumer preferences and emerging interests.

Some brands are responding by involving creators in product collaborations or giving them a role in product development. These partnerships can help companies develop products that align more closely with the expectations of specific audiences.

In this environment, creators can function as both marketing partners and sources of market intelligence.

The Influence Comes With Risks

The growing role of creators also presents challenges. Trends driven by social media can move quickly, making it difficult for brands to predict whether a surge in interest will last.

Authenticity is another concern. Audiences may react negatively when sponsored content appears disconnected from a creator’s usual interests or communication style. Disclosure requirements and advertising rules also mean that creators and brands must clearly identify paid partnerships.

There are also concerns about misinformation and exaggerated product claims. As creators gain more influence over consumer decisions, platforms, brands, and regulators face increasing pressure to maintain transparency.

A New Role in the Market

The creator economy is changing the traditional flow of influence. In the past, brands often introduced products to consumers through large advertising campaigns. Today, creators can help determine which products gain attention in the first place.

This does not mean creators have replaced traditional marketing. Instead, they have become another important layer in the market ecosystem, connecting brands with highly targeted communities and helping consumers discover products through content they already follow.

As social commerce and creator-led businesses continue to develop, creators are likely to play a larger role in determining what consumers notice, discuss, and ultimately buy. For companies, understanding this influence is becoming an important part of staying relevant in a market where trends can emerge and spread within hours.

Reddit Threatens to Block Google’s AI Content Access as $60 Million Licensing Deal Nears Expiration

Reddit is weighing whether to cut off Alphabet’s access to its platform content for artificial intelligence model training as renewal negotiations for a licensing deal worth approximately $60 million per year enter a critical phase, the Wall Street Journal reported on July 22. Reddit shares fell as much as 10% on the news, reflecting investor anxiety over a revenue stream that has become central to the company’s financial narrative since its 2024 initial public offering. The standoff places Reddit at the leading edge of a broader publisher revolt against Google’s AI Overviews feature, which is reducing referral traffic to content sources across the web.

Key Takeaways

  • Reddit is considering restricting Google’s ability to use its content for AI model training as renewal talks for a $60 million annual licensing deal reach an impasse.
  • Reddit shares dropped as much as 10% on July 22, extending a year-to-date decline of roughly 30%.
  • Pew Research Center data shows users click traditional search results just 8% of the time when a Google AI summary appears, compared to 15% without one — a relative decline of nearly 47%.
  • Major publishers including USA Today, CNN, Politico, and Business Insider have seen Google referral traffic fall between 23% and 85% over the past year.
  • Reddit also maintains a separate licensing deal with OpenAI estimated at $70 million annually, giving the company roughly $140 million in combined AI licensing revenue in 2025.

What Is at Stake in the Reddit-Google Licensing Dispute?

The original agreement, signed in February 2024 just ahead of Reddit’s IPO filing, gave Google the right to access Reddit’s Data API and use the platform’s massive archive of human-generated discussion threads to train and improve its AI models. For Reddit, the deal represented a new revenue category — data licensing — that helped legitimize the company’s valuation as it entered public markets. Reddit reported first-quarter 2026 revenue of $663 million, a 69% increase from a year earlier, with advertising driving the bulk of that growth. Data licensing, which includes both the Google and OpenAI partnerships, contributed $39 million in the quarter.

Reddit CEO Steve Huffman told analysts on the company’s most recent earnings call that both partnerships remain meaningful. But the calculus has shifted as Google’s AI Overviews — the AI-generated summaries that now appear at the top of many search results pages — have begun cannibalizing the referral traffic that Reddit and other content platforms depend on for advertising revenue. The central tension is straightforward: Reddit’s content fuels Google’s AI-generated answers, and those answers reduce the likelihood that users will click through to Reddit itself.

How Are AI Overviews Changing Search Traffic Patterns?

The Pew Research Center analyzed browsing data from 900 U.S. adults who agreed to share their online activity, covering 68,879 unique Google searches. The findings quantify the traffic problem at the heart of the Reddit-Google dispute. Users who encountered an AI summary clicked on a traditional search result just 8% of the time. Users who did not encounter a summary clicked 15% of the time — nearly double the rate. The links cited within the AI summaries themselves fared even worse: users clicked on a source inside the summary just 1% of the time. Users who saw an AI summary were also more likely to end their browsing session entirely — 26% abandoned browsing after seeing a summary, compared to 16% for results without one.

Semrush data cited in the Journal’s reporting illustrates how those behavioral shifts translate into real traffic losses for publishers. USA Today’s Google-referred traffic fell nearly 50% between June 2025 and June 2026. Politico’s dropped 23%. CNN’s fell approximately 25%. Business Insider experienced a decline exceeding 85%. The pattern extends across the publishing industry, and it has prompted multiple companies — including Reuters, the Economist, and People Inc. — to reassess their relationships with Google’s web crawlers.

Why Does This Matter for New York’s Media and Tech Ecosystem?

New York City serves as the headquarters or primary editorial hub for several of the publishers named in the dispute, including CNN, Business Insider, and a significant share of the digital media companies whose revenue models depend on search-referred traffic. The city’s media industry has spent the past decade building business models around programmatic advertising tied to page views, and the AI Overview traffic decline threatens the economic foundation of that model.

Reddit itself, while headquartered in San Francisco, operates one of the most active digital platforms for New York-centric discussion communities, from the r/nyc subreddit to neighborhood-specific forums that drive local advertising and engagement. The company’s prominence as a source cited in AI-generated search results — alongside Wikipedia and YouTube — means its content is disproportionately consumed through Google’s AI layer rather than through direct site visits, amplifying the traffic cannibalization problem.

The dispute also touches Wall Street directly. Reddit’s stock has fallen roughly 30% since the start of 2026, and the uncertainty surrounding the Google deal renewal adds downside risk heading into the company’s second-quarter earnings report on July 30. Alphabet, which reports its own quarterly results this week, faces pressure from a growing coalition of publishers exploring usage-based licensing fees that would scale as their content becomes more central to AI-generated answers — a model that could fundamentally alter the economics of AI search if widely adopted.

What Are Publishers Demanding From Google?

The emerging publisher position centers on a shift from flat licensing fees to usage-based pricing. Executives at multiple companies have indicated they want compensation structures that reflect how frequently and prominently their content appears in AI-generated answers, rather than fixed annual payments negotiated in advance. Some publishers are exploring a more radical option: blocking Google’s web crawlers entirely. The challenge is that Google does not currently offer a way to opt out of AI Overviews while remaining visible in traditional search results, meaning a publisher that blocks Google’s AI crawler also disappears from conventional search — a trade-off that most cannot afford to make.

Google has maintained that its AI features send billions of clicks to websites and has indicated it is testing an opt-out mechanism for AI summaries. But the Pew data suggests that the net effect of AI Overviews is a substantial reduction in click-through behavior, and the publisher traffic numbers reported by Semrush confirm that the declines are not theoretical.


FAQs

How Much Is the Reddit-Google AI Licensing Deal Worth?

The deal, signed in February 2024, is valued at approximately $60 million per year. Reddit also has a separate licensing arrangement with OpenAI estimated at roughly $70 million annually, bringing total AI licensing revenue to approximately $140 million in 2025. Data licensing contributed $39 million to Reddit’s $663 million in first-quarter 2026 revenue.

How Do Google AI Overviews Affect Website Traffic?

Pew Research Center found that users click traditional search results 8% of the time when an AI summary appears, compared to 15% without one — a relative decline of nearly 47%. Only 1% of users click on links cited within the AI summary itself, and 26% of users who see a summary end their browsing session entirely.

Which Publishers Have Seen the Largest Traffic Declines?

Semrush data shows USA Today’s Google-referred traffic fell nearly 50% between June 2025 and June 2026. Business Insider’s dropped more than 85%. CNN’s fell approximately 25%, and Politico’s declined 23%. Multiple publishers are now renegotiating their relationships with Google.

When Will the Reddit-Google Deal Decision Be Made?

The timeline is not publicly confirmed. Reddit is scheduled to report second-quarter earnings on July 30, which may provide clarity on the status of the renewal negotiations. Alphabet reports its own quarterly results this week, and both companies’ earnings calls could address the licensing dispute.

The Reddit-Google standoff crystallizes a tension that has been building since AI Overviews launched: the companies whose content makes AI search possible are watching their traffic — and their revenue — flow in one direction, and the price of that content is now being renegotiated in real time.

Dr. Connor Robertson on Training a Team to Use AI Without Losing the Human Touch

The common reason AI adoption fails inside organizations, according to Dr. Connor Robertson, founder of Elixir Consulting Group and host of The Prospecting Show, is not technical. It is cultural. People feel replaced rather than equipped, he argues, and comply with a directive to use AI tools in the least threatening way possible, which produces the most limited results possible.

Frame AI As Elimination Of Tedium, Not Talent

Robertson’s most effective AI adoption message is that AI handles the work people hate most: the repetitive, low-judgment tasks that accumulate throughout a day and leave people too depleted to do the work they are actually good at. When team members experience AI eliminating their worst tasks so they can spend more time on their best work, he says adoption accelerates without needing a mandate.

Start With The Tasks People Complain About Most

Robertson recommends asking a team directly what parts of their job they find most draining or most disconnected from the work they were hired to do, then starting AI adoption with exactly those tasks. In his framing, the first experience with AI in a professional context sets the tone for everything that follows; if that first experience is genuine relief, adoption compounds.

Build Skill in Low-Stakes Environments First

Robertson suggests running AI training on internal tasks with no client impact: drafting internal meeting agendas, summarizing documents before review, generating first-draft responses to internal requests. Letting team members develop prompting intuition and output calibration where an error does not affect a relationship, he argues, builds confidence that transfers reliably to high-stakes situations.

Define The Human Review Layer Explicitly

Every AI workflow touching anything client-facing needs a defined human checkpoint, in Robertson’s system. Being specific about when a human reviews before something goes out, and what kinds of decisions always require human judgment, prevents both over-reliance on unvalidated AI output and under-utilization from excessive caution.

Measure What Improves, Not Just What Changes

Robertson recommends tracking time saved per team member per week, output quality scores on AI-assisted tasks, error rates before and after, and team satisfaction with work content. AI adoption that goes unmeasured, in his view, plateaus at the level produced by initial training, while regular measurement keeps momentum and provides evidence to expand into the next category of tasks.

The Cultural Signal Behind The Rollout

Robertson argues the way AI gets introduced matters as much as the tools themselves. A rollout announced as a cost-cutting measure sends a different signal than one framed around giving people their time back, even when the underlying tools are identical. In his experience, teams that hear the second framing tend to bring their own ideas for where AI could help, while teams that hear the first tend to use the tools defensively, doing the minimum required to comply. He treats that difference in engagement as the real determinant of whether an AI rollout compounds into something the team owns or stalls out as a policy nobody is enthusiastic about.

What Measurement Alone Can’t Tell A Business

Robertson also cautions against relying on metrics as the only signal of whether adoption is genuinely working. Time saved and error rates capture the mechanical side of AI use, but they miss whether a team actually trusts the tool enough to bring it into judgment calls rather than only the safest, most repetitive tasks. He recommends pairing the numbers with direct conversation, asking people what they still won’t hand to AI and why, since that answer, more than any dashboard, tends to reveal where the real ceiling on adoption sits.

About Dr. Connor Robertson

Dr. Connor Robertson is an entrepreneur, author, and strategic advisor based in Pittsburgh. He is the founder of Elixir Consulting Group, host of The Prospecting Show, publisher of The Pittsburgh Wire, and founder of The Grant Finder. He is also a six-time published author, with titles including Built to Run, available at drconnorrobertsonbooks.com. More on his work is available at drconnorrobertson.com.

How Pricing Decisions Can Affect Northern New Jersey Home Sales

By: KeyCrew Media

In Northern New Jersey, the way a home is priced at listing often shapes what happens next more than the property itself. Many sellers still anchor their expectations to what a neighbor’s home sold for a few years ago, and that gap between expectation and current market reality is where deals start to go sideways. Accurate pricing, by contrast, changes how buyers respond to a listing from the first day it hits the market, according to Artur Tyszka, a real estate professional with The Tyszka Team.

When Sellers Price From Memory, the Market Punishes Them

Tyszka argues that the most damaging mistake sellers make right now is anchoring their asking price to what a neighbor sold for in 2021 or 2022. Buyers work from current comparables, and lenders underwrite to current values. A seller who insists on 2022 pricing is competing in a market that no longer exists.

“Nobody is considering what was sold in 2022 compared to today’s pricing,” Tyszka says. Northern New Jersey has still seen significant growth year over year, he adds, making the area an outlier compared to the rest of the country, but that growth is measured against recent sales, not two-year-old benchmarks.

The consequences are direct. An overpriced listing generates minimal showing traffic, typically five to ten groups in the first week by Tyszka’s estimate, and once a property accumulates days on market, it attracts a different kind of buyer entirely.

“When you start sitting on the market, that’s when people will start to take advantage of your home and look for a deal,” Tyszka says. “They’re going to nip you on the price, and then when the inspection comes around, they’re going to nip you on inspections. You’re not going to have much leverage, because it was your only buyer.”

Why Competitive Pricing Draws More Buyers

Tyszka points to a recent Wayne listing as a concrete illustration of the approach. The seller initially wanted to set the asking price above what the local comparables supported. Tyszka recommended listing below that target instead, reasoning that a lower entry price would widen the buyer pool and generate competitive pressure.

The seller agreed. The listing drew multiple offers and moved into a competitive bidding situation, which is exactly what the strategy is designed to produce. The difference was not the property itself. It was the market dynamics that accurate pricing created.

Tyszka says bidding wars are still occurring in Wayne, Bergen County, and Essex County. “In hot pockets and hot towns, they’re still very aggressive,” he says. The key variable is whether a listing is priced to attract competition or priced to repel it.

He contrasts that with a listing in a slower market where the initial price was set too high. The property drew roughly five to ten groups in its first week. After a price adjustment to a more accurate number, it went under contract in less than a week. “Buyers are still out there,” he says, “but they’re not overpaying for homes like they used to.”

The Window for Sellers of Wayne, New Jersey Homes Is Narrowing

For sellers considering a listing in the next three to six months, Tyszka’s advice is straightforward. He suggests moving sooner rather than later. His reasoning centers on the school-year buyer cohort, families trying to close and settle before September, who represent some of the most motivated buyers in the market.

Waiting until fall or winter means encountering a buyer pool that is smaller, less urgent, and more focused on extracting value. Delaying can carry a real cost in a shifting market, he notes. “We don’t even know what next year is going to bring,” he says. “We know what we know today.”

The market is showing some softening in certain areas, Tyszka acknowledges, but strong demand persists for well-priced Northern New Jersey homes in desirable locations. The risk for sellers who delay is missing the window when motivated buyers are actively competing.

Competing on Honesty, Not on Flattery

Tyszka says his approach is built on refusing to tell sellers what they want to hear when the numbers do not support it. He recently competed for a listing against five other brokers. He came in at $599,000. His competition was quoting $700,000. He got the listing.

“A lot of these agents that are giving these higher valuations are not doing their homework,” Tyszka says. “They’re just telling sellers what they want to hear, and that’s not what you want when you’re hiring somebody to represent the biggest asset of your home.”

His pre-listing process includes a walkthrough to identify anything likely to surface at inspection. When cosmetic issues can be resolved inexpensively, he advises sellers to handle them before going to market, since modest repairs can strengthen a home’s position with buyers. The more problems resolved before listing, the cleaner the slate for buyers and the stronger the seller’s negotiating position once offers arrive.

For sellers weighing whether to list now or wait, Tyszka frames the choice plainly. Demand exists today in Northern New Jersey’s strongest markets, and whether it will exist at the same level in six months is something no one can answer with certainty.

Artur Tyszka is a co-lead at the Tyszka Team at Keller Williams Prosperity, serving buyers and sellers in Wayne, Pompton Lakes, and throughout Northern New Jersey. The team closed over 180 transactions across Northern New Jersey in 2025.

Disclaimer: This article is based on information provided by the expert source cited above. It is intended for general informational purposes only and does not constitute legal, financial, or real estate advice. Readers should conduct their own research and consult qualified professionals before making any real estate or financial decisions.

Consumer Pessimism Reaches Highest Level Since December 2023 Despite Rallying Stock Market

American consumers are more pessimistic about the economy than at any point since December 2023, even as the S&P 500 sits within 2% of its all-time high and corporate earnings growth tracks above 20% year-over-year. The CNBC All-America Economic Survey released July 17 found 61% of respondents hold a negative view of both current conditions and the future outlook, while nearly half reported cutting back on essential purchases including food and medical care. The same week, the University of Michigan’s consumer sentiment index posted its strongest monthly gain since February, creating a divergence that complicates the economic picture heading into the Federal Reserve’s July 29 rate decision.

Key Takeaways

  • The CNBC All-America Economic Survey found 61% of respondents are pessimistic about the economy, the highest since December 2023; only 25% expressed optimism
  • Nearly half of respondents reported cutting back on essential purchases including food and medical care, up six percentage points from CNBC’s April survey; two-thirds are reducing discretionary spending on dining and entertainment
  • The University of Michigan’s preliminary consumer sentiment index rose 9.9% to 54.4 in July, beating all estimates in a Bloomberg survey, but remains 12% below its year-ago level; more than 70% of interviews were completed before U.S. strikes on Iran resumed July 7
  • Advance retail sales for June reached $768.6 billion, up 6.7% year-over-year but only 0.2% month-over-month, with online retail and motor vehicles driving gains while clothing, health care, and grocery categories declined
  • One-year inflation expectations fell to 4.2% from 4.6% in June but remain well above the 3.4% reading recorded in February before U.S.-Iran hostilities began

Why Are Consumers Pessimistic Despite A Strong Stock Market?

The 61% pessimism reading in the CNBC survey represents the widest gap between market performance and consumer mood since the post-pandemic inflation period. The S&P 500 has gained more than 15% year-to-date, Q2 corporate earnings are tracking above 20% growth, and unemployment remains historically low. Those indicators traditionally correlate with improving consumer confidence, but the relationship has broken down in 2026 because the gains are concentrated in asset prices and corporate balance sheets rather than in household purchasing power.

The survey of 1,000 registered voters found that the cost of everyday goods remains the dominant concern. Nearly half of respondents said they are cutting back on essential purchases, a six-percentage-point increase from CNBC’s April survey. Two-thirds reported reducing discretionary spending on dining, entertainment, and travel. The share of voters who expect economic conditions to worsen outpaced those expecting improvement by a 41-to-29 margin. Micah Roberts, a Republican pollster who worked on the survey, described the electorate as being in a distinctly sour mood heading into the midterm election cycle.

The disconnect reflects what economists have described as a “two-speed” consumer economy, where households with significant investment portfolios benefit from rising equity values while wage earners without substantial assets absorb the cumulative effect of prices that have risen more than 20% since 2020 and have not meaningfully retreated.

What Did The University Of Michigan Sentiment Index Show?

The University of Michigan Surveys of Consumers <a rel=”nofollow”> posted a preliminary July reading of 54.4, up 9.9% from the June final of 49.5 and the highest level since February 2026. The result topped all estimates in a Bloomberg survey of economists and marked the second consecutive month of approximately 10% gains following the record low of 44.8 recorded in May.

All five index components improved. The Current Economic Conditions Index rose 15.1% to 54.9, while the Consumer Expectations Index climbed 6.5% to 54.0. Buying conditions for durable goods and year-ahead business conditions each jumped roughly 20%. The improvement was broad-based across age, income, wealth, and political affiliation, with particularly strong gains among consumers without a bachelor’s degree.

Surveys of Consumers Director Joanne Hsu attributed the rebound primarily to easing gasoline prices in recent weeks. However, Hsu cautioned that the upward momentum may prove difficult to sustain. More than 70% of the July interviews were completed before the U.S. resumed strikes on Iran on July 7 and the subsequent reacceleration in gas prices that pushed the national average back toward $4 per gallon. The sentiment index remains 12% below its July 2025 level, and one-year inflation expectations, while down to 4.2% from 4.6%, remain well above the 3.4% reading recorded before the Iran conflict began in February.

What Does The Retail Sales Data Reveal About Actual Spending?

The U.S. Census Bureau’s advance retail sales report <a rel=”nofollow”> for June showed total retail and food services sales of $768.6 billion, up 0.2% from May and 6.7% higher than June 2025. Core retail sales excluding automobiles and gasoline rose 0.4%, and sales excluding gasoline stations increased 0.7%.

The category-level data revealed where consumers are drawing sharper lines. Motor vehicle dealers posted a 1.9% monthly gain. Nonstore retailers, the Census Bureau category capturing the bulk of e-commerce, also rose 1.9%, boosted in part by Amazon’s Prime Day promotional event, which ran June 23 through 26. Electronics and appliance stores gained 0.8%.

The declines told a different story. Clothing and accessories stores fell 0.3%. Health and personal care stores dropped 0.8%. Grocery sales slipped 0.4% from May. The pattern tracks closely with regional anecdotes from the Federal Reserve’s Beige Book and independent consumer surveys. New York businesses reported that luxury retailers continued to perform well, but a coffee shop operator said the average purchase amount declined, a dental practice cited increasing appointment cancellations, and auto dealers noted affordability concerns restraining new vehicle demand.

What Does The Divergence Mean For The Economy?

The gap between improving sentiment surveys and deteriorating spending behavior on essentials suggests consumers are adjusting to a permanent cost baseline rather than anticipating price relief. The University of Michigan’s five-year inflation expectation held steady at 3.3%, above the 2.8% to 3.2% range that prevailed throughout 2024. Consumers appear to have accepted that prices will not return to pre-2022 levels and are restructuring household budgets accordingly.

The spending data also complicates the Federal Reserve’s calculus ahead of its July 28-29 meeting. The 0.2% monthly retail sales gain is technically positive but represents the slowest month-over-month growth in three months. The fed funds rate remains at 3.50% to 3.75%, and Fed Chair Kevin Warsh has maintained a hawkish tone emphasizing that inflation remains above the 2% PCE target. The June payrolls report added only 57,000 jobs, the weakest print in months, suggesting the labor market may be cooling faster than headline unemployment figures indicate.

Disclaimer: This article is for informational purposes only and does not constitute financial advice. Readers should consult a qualified financial advisor before making investment decisions.


FAQs

What percentage of Americans are pessimistic about the economy? The CNBC All-America Economic Survey found 61% of respondents are pessimistic about both current conditions and the future outlook, the highest since December 2023. Only 25% expressed optimism about the economy.

What is the University of Michigan consumer sentiment index reading for July 2026? The preliminary reading is 54.4, up 9.9% from the June final of 49.5. The result topped all economist estimates and marks the highest level since February 2026, though the index remains 12% below its year-ago level.

Are consumers cutting back on spending? Nearly half of respondents in the CNBC survey reported reducing spending on essentials including food and medical care, up six percentage points from April. Two-thirds said they are spending less on discretionary categories like dining, entertainment, and travel.

What did the June retail sales report show? The Census Bureau reported total retail and food services sales of $768.6 billion in June, up 0.2% from May and 6.7% from June 2025. Online retail and motor vehicles drove gains, while clothing, health care, and grocery categories declined.

What are current inflation expectations? The University of Michigan’s one-year inflation expectation fell to 4.2% from 4.6% in June, while the five-year expectation held at 3.3%. Both remain above pre-Iran-conflict levels recorded in February 2026.

When is the next Federal Reserve rate decision? The FOMC meets July 28-29, with the rate decision announced at 2:00 PM ET on July 29. Market consensus expects a hold at 3.50% to 3.75%, though some traders have priced in a potential hike.