Market Daily

July Payrolls Report Looms as the Federal Reserve’s Final Labor Market Signal Before September

The Bureau of Labor Statistics will release the July 2026 Employment Situation report on Friday, August 7, at 8:30 a.m. ET, delivering the final major labor market reading before the Federal Reserve’s September 16 policy meeting. The report arrives after June’s payrolls figure came in at just 57,000 new jobs, the weakest monthly gain in four months, and after the Fed voted 9-3 on July 29 to hold the federal funds rate steady at 3.5% to 3.75%. The combination of softening employment data and a divided central bank has turned this week’s jobs number into one of the more consequential data releases of the year for rate-path expectations.

  • The Bureau of Labor Statistics reported June nonfarm payrolls of 57,000, well below the 110,000-115,000 consensus and roughly in line with the 12-month average of 36,000 jobs per month
  • April and May payrolls were revised downward by a combined 74,000 jobs, bringing April to 148,000 and May to 129,000
  • The June unemployment rate edged down to 4.2%, but labor force participation fell 0.3 percentage points to 61.5%, its lowest reading since March 2021
  • The Federal Reserve held rates at 3.5%-3.75% on July 29 in a 9-3 vote, with Chairman Warsh noting that “economic activity is expanding at a solid pace despite elevated uncertainty”
  • The July payrolls and August CPI reports are the two primary data inputs the FOMC will evaluate ahead of its September 16 rate decision

June’s Employment Data in Detail

The Bureau of Labor Statistics’ June Employment Situation report painted a mixed picture of the U.S. labor market. The headline nonfarm payrolls figure of 57,000 fell short of expectations, but the composition of the gains offered context that the topline number alone does not capture. Professional and business services added 36,000 jobs, continuing an upward trend that has produced 172,000 positions in the sector since October 2025. Social assistance contributed 25,000 jobs, driven primarily by individual and family services. Health care added 22,000 positions, though at a slower pace than the 38,000-per-month average over the prior year.

Leisure and hospitality, however, shed 61,000 jobs in June, reflecting weaker-than-usual seasonal hiring patterns. The BLS noted that employment in the industry has shown little net change so far in 2026. The sector’s contraction accounted for a significant drag on the headline figure and underscored the uneven nature of the current labor market expansion, where gains in professional services and health care are being partially offset by softness in consumer-facing industries.

The downward revisions to April and May were equally notable. April’s payrolls were revised from 179,000 to 148,000, and May’s from 172,000 to 129,000, a combined reduction of 74,000 jobs. Revisions of that magnitude can reshape the narrative around labor market momentum, and in this case, they suggest that the spring hiring pace was softer than initially reported.

The Household Survey and Participation Decline

The household survey, which measures unemployment and labor force participation through a separate methodology from the establishment payrolls survey, showed the unemployment rate at 4.2%, little changed from the prior month. The number of unemployed people held at 7.1 million. Among major worker groups, adult men posted a 3.9% unemployment rate, adult women 3.7%, and teenagers 14.6%.

The more concerning signal came from labor force participation. The rate fell 0.3 percentage points to 61.5%, the lowest level since March 2021, and the employment-population ratio edged down 0.2 percentage points to 59.0%. Long-term unemployment (27 weeks or more) held at 1.9 million but has risen by 286,000 over the past year, now accounting for 27.3% of all unemployed workers. The number of people working part-time for economic reasons, those who would prefer full-time work but had their hours cut or could not find full-time positions, held at 4.7 million.

The participation decline complicates the rate picture. A falling unemployment rate driven by fewer people looking for work carries different implications for the Fed than one driven by strong hiring. The July report will reveal whether June’s participation drop was an anomaly or the beginning of a trend.

The Federal Reserve’s July Decision and September Outlook

The Federal Open Market Committee voted 9-3 on July 29 to maintain the federal funds rate target range at 3.5% to 3.75%. The statement noted that economic activity continues to expand at a “solid pace” despite elevated uncertainty, that productivity growth and capital investment remain strong, and that job gains have “kept pace with the workforce.” On inflation, the committee acknowledged that price pressures remain “elevated relative to the Committee’s 2 percent goal,” driven in part by supply shocks in sectors including energy.

The 9-3 vote marked a notable division. Three dissenting members voted against holding, suggesting internal disagreement about whether current policy is appropriately calibrated to the economic data. Chairman Warsh’s press conference reinforced that the committee is data-dependent heading into September, with the July employment report and the August CPI release serving as the two most consequential inputs.

Wage data from the June report added another variable. Average hourly earnings for all private-sector employees rose 0.3% in June to $37.64, with year-over-year growth at 3.5%. Wage growth at that pace remains above levels consistent with the Fed’s 2% inflation target, and a repeat or acceleration in the July data could reinforce the case for holding rates steady through September. A soft payrolls number paired with cooling wages, on the other hand, could build the argument for a rate cut.

The Week Ahead and Data Landscape

The July payrolls report does not arrive in isolation. Tuesday, August 5, brings the ADP National Employment Report for July, which tracks private-sector hiring through payroll data from ADP’s client base. The same day, the Institute for Supply Management releases its Services PMI for July, and S&P Global publishes the final reading of its Services PMI. Each of these data points feeds into the broader picture of labor market health and economic activity that the Fed will evaluate before September.

The BLS has also scheduled a preliminary benchmark revision to establishment survey data for August 28, 2026. That revision, which benchmarks payrolls estimates to comprehensive employment counts from the Quarterly Census of Employment and Wages, could result in significant adjustments to the reported job gains over the past year. Benchmark revisions have, in prior years, shifted the labor market narrative substantially, and market participants will be watching for any large discrepancies between the current estimates and the QCEW-based counts.

For the week ahead, the July payrolls number will set the tone. A rebound toward the 100,000-plus range could ease concerns about labor market deterioration and reduce pressure on the Fed to act in September. A second consecutive miss below expectations would sharpen the debate over whether the current rate stance is too restrictive for an economy where hiring is slowing, participation is falling, and long-term unemployment is rising.

Disclaimer: This article is for informational purposes only and does not constitute financial, investment, or trading advice. Market Daily does not recommend the purchase or sale of any securities. Readers should consult a qualified financial advisor before making investment decisions based on economic data or Federal Reserve policy expectations.

FAQs

When is the July 2026 jobs report released?

The Bureau of Labor Statistics will publish the July 2026 Employment Situation report on Friday, August 7, 2026, at 8:30 a.m. ET.

What did the June 2026 jobs report show?

June nonfarm payrolls came in at 57,000 new jobs, well below consensus estimates. The unemployment rate was 4.2%, and labor force participation fell to 61.5%. April and May payrolls were revised downward by a combined 74,000.

What is the current federal funds rate?

The Federal Reserve held the federal funds rate target range at 3.5% to 3.75% at its July 28-29, 2026 meeting, in a 9-3 vote.

When is the next Federal Reserve rate decision?

The next FOMC meeting is scheduled for September 16, 2026. The July payrolls report and the August CPI release are the primary data inputs the committee will evaluate ahead of that decision.

Fabrikant & Miller, the Palm Beach Diamond & Jewelry Buyer Locals Trust for Discretion

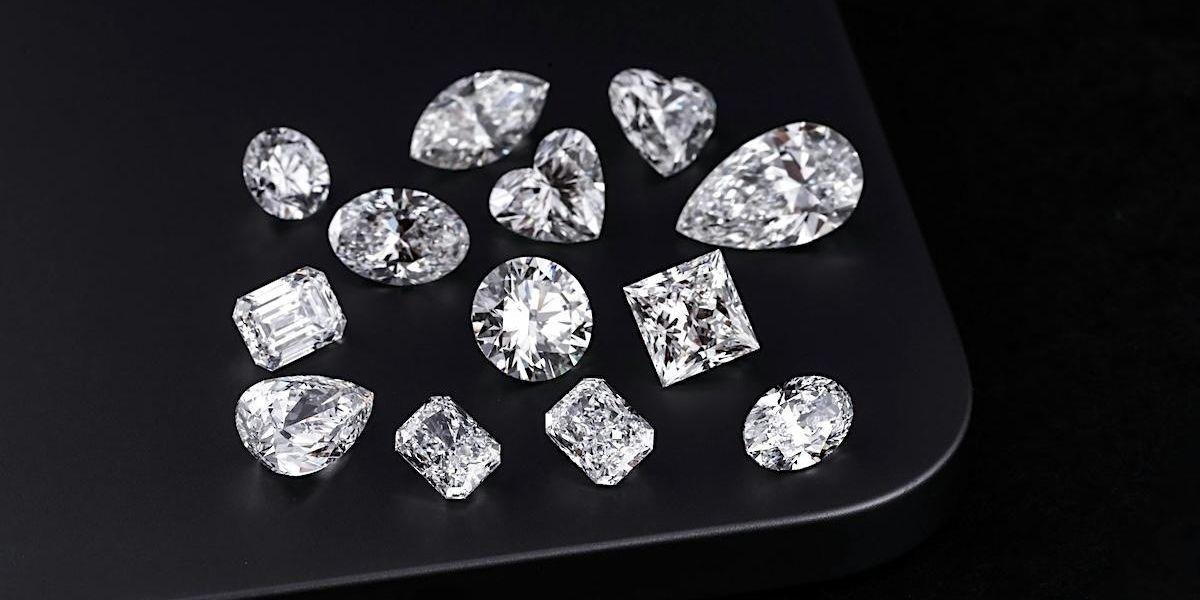
In the prestigious town known globally for its elegance and emphasis on privacy, finding the right buyer for diamonds and fine jewelry matters greatly to many. Fabrikant & Miller has earned the confidence of Palm Beach County locals by combining expert knowledge with a strong commitment to confidential service. Situated quietly in Via Newsome along Worth Avenue, the business provides a comfortable setting where clients can discuss their collections away from public view.

Peter Fabrikant brings a rich family heritage in the New York jewelry world. Growing up around diamonds and estate pieces, he developed a keen eye for value through years of hands-on work in buying and selling pre-owned items. His extensive contacts across the industry help ensure sellers receive competitive offers based on true market conditions.

Craig Miller contributes more than four decades of experience from some of the most respected names in luxury. Having worked with brands like Cartier, Van Cleef & Arpels, GRAFF, and Bulgari in key locations, he understands both the creation and resale sides of exceptional jewelry and watches. The two partners joined forces in Palm Beach in 2017, drawn by the area’s sophisticated residents and impressive array of heirloom and designer pieces.

What truly distinguishes this team is their focus on discretion and personal attention. Many clients arrive with meaningful items, perhaps pieces passed down through generations or gifts from special occasions. At Fabrikant & Miller, every appointment takes place in private, allowing for open conversations without any sense of rush or exposure. The partners take the time to evaluate each diamond, watch, or piece of jewelry thoughtfully, sharing honest insights into its history, quality, and potential value.

These jewelers purchase a wide variety of treasures, including estate jewelry, signed designer creations, loose diamonds, luxury timepieces, gold, and silver. Their global reach allows them to connect items with the right buyers efficiently, often supporting competitive offers and same-day transactions. This practical advantage, paired with straightforward communication, has contributed to thousands of transactions with customers throughout South Florida.

Palm Beach locals frequently point to the jeweler’s integrity as a key reason for their loyalty. Sellers appreciate receiving clear explanations rather than sales pressure, especially when deciding the fate of family heirlooms. Whether handling a single standout diamond ring or an entire collection, the experience tends to feel supportive and professional. Many clients leave not only with a check but also with a better understanding of their pieces and the current market. Privacy remains central to the operation. The secluded Worth Avenue location helps maintain confidentiality for those who prefer to keep transactions low-key. In Palm Beach, where reputations and personal matters are highly important, this level of consideration builds lasting trust.

For residents contemplating the sale of fine jewelry or diamonds, Fabrikant & Miller offers an option grounded in expertise and respect. Their long experience reflects a focus on fair value and careful handling of sensitive matters. Those interested can arrange a private consultation by visiting this jeweler on Worth Ave or reaching out through their website. In a community that values both discretion and results, Fabrikant & Miller continues to serve as a trusted choice for jewelry buyers across Palm Beach.

Paul Davis Restoration of Metro East Illinois Streamlines Property Recovery with Comprehensive, Insurance-Coordinated Solutions

By: Olivia Hughes

Navigating property damage with a structured, single-source restoration process.

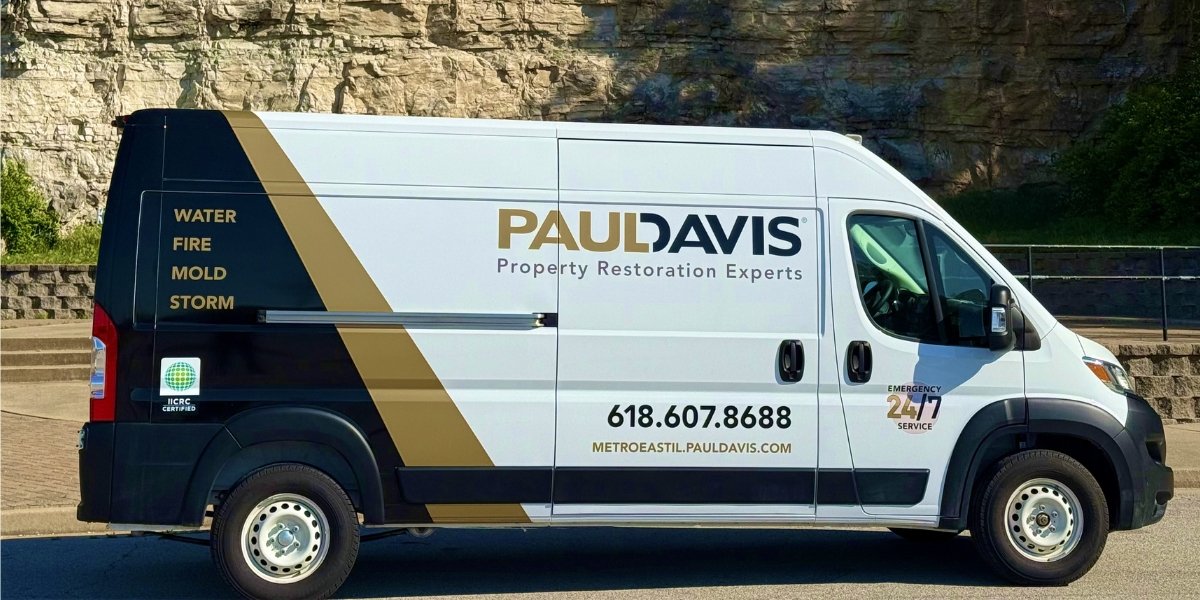
Property damage from unexpected events like broken pipes, flooding, or storms can disrupt a household or business. For property owners in O’Fallon, Edwardsville, and Belleville, the stress of dealing with water mitigation is often compounded by the challenge of managing multiple contractors and navigating complex insurance claims. Paul Davis Restoration of Metro East Illinois addresses these common industry challenges by offering a structured, start-to-finish restoration process that combines emergency mitigation, clear documentation, and coordinated reconstruction under a single point of contact.

Many property restoration companies focus on the initial emergency response and mitigation phase, leaving the property owner to find and manage separate contractors for the subsequent repair and reconstruction work. This fragmented approach can lead to miscommunication, extended project timelines, and increased stress for the client. The team at Paul Davis Restoration of Metro East Illinois aims to help fill this market gap by managing the scope of the project from the initial emergency call through the restoration and repair process.

By handling both the mitigation and rebuilding phases, the company helps reduce unnecessary handoffs, property downtime, and confusion for homeowners during stressful times. Property owners can learn more about these recovery options by visiting the Paul Davis Restoration of Metro East Illinois website.

Rapid Emergency Response and Certified Technical Expertise

When dealing with water, fire, or mold damage, prompt action is important to help prevent secondary damage and protect property value. The company provides 24/7 emergency services with a typical response time of 60 to 90 minutes, depending on the specific location and current weather conditions. This response model allows trained technicians to arrive on-site, stabilize the environment, and begin the cleanup process.

As a locally owned and veteran-owned franchise, the business combines the personal care of a local contractor with the resources, equipment, and training of a national network. The technicians are certified by the Institute of Inspection, Cleaning, and Restoration Certification, helping ensure that work aligns with recognized industry standards for safety and quality. The company offers free inspections and transparent estimates before work begins, allowing clients to understand the scope of the project without upfront financial obligations.

Streamlining the Insurance Claims Process Through Accurate Documentation

One of the more complex aspects of property recovery is dealing with insurance adjusters and helping claims move forward without unnecessary delays. The team specializes in residential and commercial restoration where detailed documentation and coordination with insurance carriers are important. By utilizing industry-standard documentation and estimating tools, the company works directly with major insurance carriers to help streamline the claims process.

The team assists clients by providing clear documentation, accurate estimates, and direct billing when applicable. This coordination helps reduce the administrative burden on the property owner and provides the insurance carrier with the information needed to process the claim. Clients frequently note the peace of mind that comes from this transparent approach.

For instance, client Tammi Eisenbraun shared her experience, stating:

“If I could give 10 stars, I would. A very stressful situation was made less stressful because Adam was professional, courteous, and followed through. I never had to question what was happening with the water mitigation. He was transparent each step of the process. If you need restoration services, you cannot go wrong by choosing this company!”

Commitment to Clear Communication and Community Service

The business prioritizes professionalism, empathy, and responsiveness from the first interaction. Under the leadership of Adam Rennegarbe, the team works to ensure that clients know who is responsible for their project and how to reach them. This dedicated point of contact helps reduce the communication gaps that often cause frustration in the restoration industry. The company also offers weekend appointments by request and features a wheelchair-accessible entrance and a free on-site parking lot to accommodate clients.

The company actively shares educational resources, seasonal property maintenance tips, and community updates online. Property owners can stay connected with the team, view recent projects, and access helpful tips by following their Facebook page. Video overviews of their services and restoration capabilities are also available on their YouTube channel.

Through a combination of emergency response, full-service project management, and direct insurance coordination, the company continues to support communities throughout the Metro East Illinois region, including ZIP codes 62269, 62025, and 62221. By focusing on a structured process from start to finish, the team helps families and businesses move through property recovery with greater clarity and support.

Federal Reserve Holds Rates Steady in Divided 9-3 Vote as Inflation Pressures Mount

The Federal Reserve voted 9-3 on July 29 to hold the federal funds rate at its current target range of 3.5%-3.75%, extending a holding pattern that has now lasted five consecutive meetings. Three regional bank presidents dissented in favor of a quarter-point rate hike, making the decision one of the most internally contested in years and signaling a growing faction within the Federal Open Market Committee that views the current stance as insufficient to address inflation that has remained above the Fed’s 2% target for more than five years.

  • The FOMC voted 9-3 to maintain the federal funds rate at 3.5%-3.75%, the fifth straight meeting with no change
  • Three regional presidents dissented: Beth Hammack (Cleveland), Neel Kashkari (Minneapolis), and Lorie Logan (Dallas), each preferring a 25 basis point hike
  • Fed Chairman Kevin Warsh described the internal disagreement as a “good family fight,” a phrase he has used publicly at least 13 times since taking office
  • The FOMC statement cited “elevated uncertainty” tied in part to the Middle East conflict, with energy prices contributing to inflation above the 2% goal
  • JPMorgan Wealth Management expects the Fed to hold through the end of 2026; the next FOMC meeting is September 15-16
  • Warsh is expected to speak at the Jackson Hole Economic Policy Symposium in August

The Three Dissents and What They Signal

The FOMC’s July 29 statement identified the three dissenters by name: Cleveland Fed President Beth Hammack, Minneapolis Fed President Neel Kashkari, and Dallas Fed President Lorie Logan, each of whom preferred to raise the target range by a quarter percentage point. The three dissents represent the widest split on the committee since Warsh took over as chairman, and they reflect a debate that has been building across multiple meetings as inflation data has remained stubbornly elevated.

Governor Christopher Waller had also voiced public concern about inflation in the weeks leading up to the meeting, stating that higher rates could become necessary if progress stalled further. Waller ultimately voted with the majority to hold, but his public comments placed him close to the dissenting camp, suggesting the 9-3 margin may understate the degree of internal tension.

The FOMC statement itself was notably brief, consistent with Warsh’s stated goal of reducing the amount of forward guidance the Fed provides to markets. The committee acknowledged that economic activity continues to expand at a solid pace, that productivity growth and capital investment are strong, and that job gains have kept pace with the workforce. On inflation, the statement was direct: it remains elevated relative to the 2% goal, driven in part by supply shocks in sectors including energy. The committee’s closing line carried the most weight, stating simply that it “will deliver price stability.”

Warsh’s Communication Strategy Takes Shape

Chairman Kevin Warsh used the post-meeting press conference to frame the dissents as a healthy institutional process rather than a sign of dysfunction. His characterization of the debate as a “good family fight” has become a recurring phrase in his public appearances, and the July meeting delivered on the internal disagreement he has openly invited since taking office. Warsh told reporters he would not characterize the decision as a “pause,” instead describing it as “a rigorous review of the economic situation” and “a review of the big hard questions.” He added that the decision was “merely the beginning of a story, not the end.”

That framing reflects a deliberate shift from the communication style of Warsh’s predecessors. Where former chairs offered detailed forward guidance about the likely path of rates, Warsh has dedicated one of five internal task forces specifically to changing how the Fed communicates. The shorter statement, the refusal to signal future moves, and the tolerance for public disagreement among committee members all point to a chairman who wants markets to react to data rather than central bank telegraphing.

Inflation, Energy, and the Middle East Factor

The Fed’s inflation problem has a geopolitical dimension that the committee acknowledged directly in its statement. The reference to “elevated uncertainty that owes, in part, to the conflict in the Middle East” points to the role energy prices have played in keeping inflation above target. Rising oil prices tied to U.S.-Iran tensions have added upward pressure to consumer costs across transportation, manufacturing, and food production, creating a supply-side inflation dynamic that monetary policy tools are limited in addressing.

The committee penciled in one quarter-point increase by the end of 2026 at its June meeting, but the July decision left rates unchanged. The gap between where rates sit today and where at least some FOMC members believe they should be continues to widen. For the dissenters, the argument is straightforward: with inflation above target for five consecutive years and energy-driven supply shocks adding new pressure, holding rates steady risks allowing expectations to drift further from the 2% goal.

For the majority, the calculus involves more variables. Economic activity remains solid, the labor market has not shown signs of overheating, and the supply-side nature of the current inflation pressures means rate hikes would do little to address the root causes while adding borrowing costs to an economy still absorbing uncertainty from geopolitical conflict.

What the Hold Means for Borrowers and Markets

The Fed’s benchmark rate influences the cost of mortgages, credit cards, auto loans, and deposit rates across the U.S. economy. While short-term consumer rates are closely pegged to the federal funds rate, longer-term rates such as 15-year and 30-year fixed mortgages follow the trajectory of Treasury yields, which have been climbing independently of Fed actions. The 10-year Treasury yield jumped to its highest level since January 2025 on July 31, reflecting market expectations that inflation may persist longer than the Fed’s current stance accounts for.

JPMorgan Wealth Management’s Phil Camporeale said the firm agreed with the decision to hold, noting that despite some positive core inflation data earlier in July, the lack of bargaining power from U.S. employees and the base case of no further escalation in the U.S.-Iran conflict should keep the Fed on hold through the end of the year. That assessment positions the next meaningful decision point at the September 15-16 FOMC meeting, where fresh economic data and any developments in the Middle East could shift the calculus.

Before that meeting, Warsh is expected to speak at the Jackson Hole Economic Policy Symposium in August, an event that has historically served as a venue for Fed chairs to signal strategic direction. Under Warsh’s communication philosophy, however, markets should expect less of a roadmap and more of a philosophical framing. Whether that approach holds depends on whether the data between now and September gives the three dissenters additional evidence to press their case for a hike.


Disclaimer: This article is for informational purposes only and does not constitute financial, investment, or trading advice. The information presented reflects publicly available data and third-party analysis as of the publication date. Readers should consult a qualified financial advisor before making any investment or borrowing decisions. Federal Reserve policy decisions can affect interest rates, loan pricing, and market conditions in ways that vary based on individual circumstances.

FAQs

What Did the Federal Reserve Decide at Its July 2026 Meeting?

The FOMC voted 9-3 on July 29, 2026, to maintain the federal funds rate at a target range of 3.5%-3.75%. The decision marked the fifth consecutive meeting with no change to rates. Three regional bank presidents, Beth Hammack of Cleveland, Neel Kashkari of Minneapolis, and Lorie Logan of Dallas, dissented and voted in favor of raising rates by a quarter percentage point.

Why Did Three Fed Officials Vote to Raise Interest Rates?

The three dissenting officials have expressed concern that inflation has remained above the Fed’s 2% target for more than five years, and that holding rates steady risks allowing inflation expectations to become further entrenched. Rising energy prices connected to U.S.-Iran tensions have added supply-side pressure that the dissenters believe warrants a tighter monetary policy stance, even as the economic expansion continues.

When Is the Next Federal Reserve Meeting in 2026?

The next FOMC meeting is scheduled for September 15-16, 2026, with the rate decision expected on the second day. Before that meeting, Fed Chairman Kevin Warsh is expected to speak at the Jackson Hole Economic Policy Symposium in August, which may offer additional context for how the committee is weighing incoming data.

Rohan Gurram Believes the Future of Media Belongs to World-Builders

By Targe Media

Rohan Gurram is building RG Creators around a belief that the next important media companies will do more than manage talent or produce campaigns.

They will build worlds around people, brands, and original ideas.

RG Creators is a creative agency and talent company working across representation, brand campaigns, cinematic production, and original media. The company is designed to connect those areas rather than operate them as separate businesses.

Gurram believes creators are often treated too narrowly.

Many management companies focus primarily on sponsorships. They negotiate rates, manage contracts, and help talent secure brand deals. That work matters, but Gurram believes it should be the beginning of a creator’s business rather than the full ambition.

“The goal should be bigger than helping someone make more money from their next post,” Gurram said. “We want to help creators build careers, businesses, and bodies of work that can last.”

RG Creators plans to represent ambitious creators while helping them expand into original shows, films, products, live experiences, and other forms of intellectual property.

The company’s creative agency side will also work directly with brands.

Rather than producing disconnected pieces of content, RG Creators wants to help brands establish a recognizable creative world. That could include strategy, visual identity, campaigns, films, recurring talent, social formats, and physical experiences.

The aim is to make each piece feel connected.

Gurram believes many brands have enough content but lack a distinct point of view. Their campaigns may perform individually without building a larger identity people remember.

RG Creators intends to solve that through cinematic storytelling and long-term creative direction.

“We are interested in what the brand should feel like, who belongs inside its world, and what stories it should continue telling,” Gurram said. “A campaign should contribute to something larger.”

The talent and agency divisions are meant to strengthen each other.

A creator represented by RG Creators could appear in a branded film, collaborate with another member of the roster, host an original format, or eventually build a company around their audience.

A brand working with the agency could gain access to creators, directors, actors, musicians, and other talent who already understand how to hold attention and connect with an audience.

The larger advantage is having talent development, strategy, and production within the same ecosystem.

RG Creators can help shape an idea, assemble the right team, produce the work, and continue developing what comes after the initial release.

Gurram sees these overlaps as central to the future of creative careers.

That is the opportunity he sees for RG Creators.

The company can represent the people shaping culture while helping brands and talent build the worlds where their work belongs.

“We want to create a place where talent, storytelling, and business reinforce each other,” Gurram said. “The strongest careers and brands are built when every project adds to the next one.”

RG Creators is still at the beginning of that ambition.

Its long-term goal is to become a creative company capable of developing talent, producing premium commercial work, and building original media under one roof.

Gurram believes that model will become increasingly important as creators seek more ownership and brands search for deeper cultural relevance.

The future, in his view, belongs to companies that can do more than produce attention.

It belongs to those capable of building something people recognize, return to, and want to become part of.

Paul Davis Restoration of Southeast Jersey Shore Delivers 24/7 Water, Fire, and Mold Damage Restoration Across Egg Harbor Township, Williamstown, and Vineland

EGG HARBOR TOWNSHIP, New Jersey. Burst pipes, roof leaks, kitchen fires, and hidden mold do not wait for business hours. Paul Davis Restoration of Southeast Jersey Shore, a locally owned and family-operated property restoration company, answers emergency calls around the clock and holds itself to a published response standard of first contact with the customer within 30 minutes and a technician on site within 60 minutes.

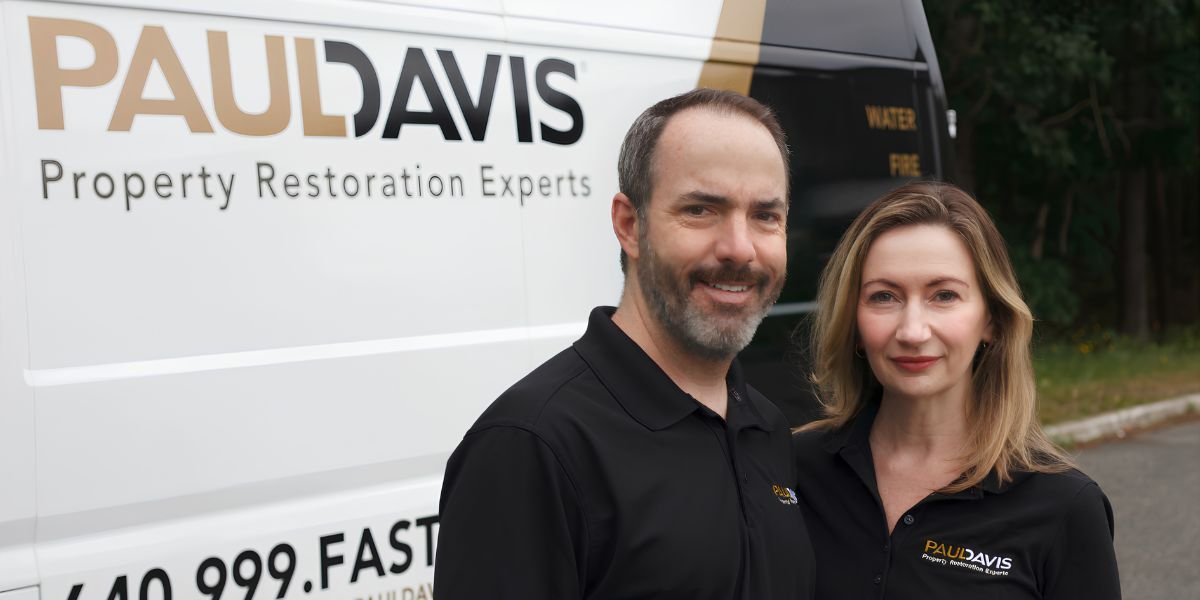
The office serves homeowners, landlords, property managers, and commercial clients in Egg Harbor Township, Williamstown, Vineland, and the surrounding South Jersey communities. It is led by owners Linda Shea and Alex Boland, who both hold Institute of Inspection, Cleaning and Restoration Certification (IICRC) credentials in water damage restoration, fire and smoke damage restoration, structural drying, and trauma and crime scene cleanup, as well as CRMR mold remediation certification and EPA lead safety certification.

Executive Discipline Applied to Emergency Restoration

Shea and Boland left their established executive careers to run the local Paul Davis franchise. One of the two owners is a former Army Infantry Officer who led combat teams. The other spent years leading strategy and customer insights work for national brands, managing multimillion-dollar budgets and large, distributed teams.

That background changes how jobs get run. Schedules are built and held. Safety protocols are written down rather than assumed. Quality checks happen before a crew leaves a property. Every project is documented with photos and digital records, so the homeowner and the insurance adjuster are looking at the same information at the same time.

A Response Standard Measured in Minutes

Speed matters in restoration for practical reasons. Water travels through drywall, subfloor, and insulation within hours, and mold can begin to grow on damp materials in as little as 24 to 48 hours. Delayed drying often turns a containable loss into a demolition project.

The team targets a 30-minute phone response and a 60-minute arrival for emergencies, 24 hours a day, seven days a week. Inspections and estimates are free, including free in-home estimates.

Certified in Water, Fire, Smoke, Mold, and Trauma Cleanup

The office handles the full range of property loss work, including water damage mitigation and structural drying, fire and smoke damage restoration, mold inspection and remediation, storm and flood cleanup, contents cleaning and storage, and reconstruction after the mitigation phase is complete. Trauma and crime scene cleanup is also available with certified technicians.

Work is backed by a workmanship warranty, an on-time service commitment, and a one-year warranty on completed repairs. The company also uses eco-friendly products and methods where possible.

A Smoother Path Through the Insurance Claim

Insurance is where most restoration projects stall. The team maintains working relationships with all major carriers and coordinates directly with the assigned adjuster to reach a scope that actually restores the property.

Because both owners come from analytics and technology backgrounds, the office leans on digital documentation rather than memory. Moisture readings, daily photos, and progress notes are captured and shared, which shortens the back-and-forth that usually delays approval.

Built for Both Homeowners and Property Managers

Most restoration companies pick a lane. Small operators are responsive but run on improvisation. Large operators have systems but feel impersonal. This office is set up to serve both sides of the market.

For multi-site operators and investors, that means pre-loss planning, standardized response playbooks, portfolio-level reporting, and an understanding of occupancy, cash flow, and risk. For families, it means one accountable point of contact, plain language explanations, and someone who picks up the phone. The owners have managed large facilities and coordinated multiple trades, so schedules hold, and downtime shrinks.

Fixing What People Dislike About Restoration Companies

Property owners tend to name the same complaints about the industry: slow callbacks, vague scope and pricing, messy job sites, and silence once the insurance company gets involved. The office was designed around those specific failures.

Expectations are set at the first visit and revisited throughout the project. Updates are proactive rather than requested. Crews are hired for technical skill and for temperament, since a water loss or a fire is not just another work order to the person living there. Job sites are left clean, and documentation is shared rather than held back.

What Local Customers Say

The office has built a review record centered on responsiveness and communication. Katrina Prodan, who called about a mold issue at a rental property, described a fast and reassuring experience:

“When I first called Paul Davis Property Restoration, I felt nervous and in over my head dealing with mold. My appointment was scheduled within 24 hours, and their team arrived promptly on time. They are trustworthy, responsive, and extremely reasonable with pricing for the services. I highly recommend their services.”

Other customers point to the same pattern. Karen Kosich, who worked with the team through an insurance claim, noted that the crew was knowledgeable, efficient, and respectful of her home and time, and that she felt they advocated for her through the repair process. Aidan Lawlor called the service exceptional after the team arrived quickly for frozen pipes.

Recent projects and crew introductions are posted on the company Instagram page.

Frequently Asked Questions

How fast does Paul Davis Restoration of Southeast Jersey Shore respond to an emergency?

The office targets first contact with the customer within 30 minutes of the call and a technician on site within 60 minutes. Emergency service is available 24 hours a day, seven days a week.

What areas does the company serve?

Primary service areas include Egg Harbor Township, Williamstown, and Vineland, as well as surrounding Southeast New Jersey shore communities.

Does the company offer free estimates or inspections?

Yes. Inspections and estimates are free, including free in-home estimates.

Does Paul Davis Restoration work with insurance companies?

Yes. The office works with all major carriers and coordinates directly with the assigned adjuster, providing photo and data documentation to support the claim.

What types of damage does the team handle?

Water damage, fire and smoke damage, mold, storm and flood damage, along with the reconstruction that follows mitigation.

Is the office accessible?

The location has a wheelchair accessible entrance, parking lot, restroom, and seating. Free on-site parking and free street parking are available.

About Paul Davis Restoration of Southeast Jersey Shore

Paul Davis Restoration of Southeast Jersey Shore is a locally owned, family-operated, veteran-owned, woman-owned, and minority-owned property restoration company serving Egg Harbor Township, Williamstown, Vineland, and the surrounding South Jersey area. More about the company’s services is available on its YouTube page. The office provides 24/7 emergency water, fire, smoke, and mold damage restoration, insurance claim coordination, and full reconstruction, backed by IICRC-certified technicians and the national Paul Davis network.

Federal Reserve Issues 11-Word Inflation Warning, Market History Suggests Higher Rates Ahead

The Federal Reserve warned in its July 2026 meeting minutes that years of above-target inflation ‘could begin to affect inflation expectations and wage- and price-setting decisions,’ an 11-word statement that signals concern about entrenched inflation and potential wage-price spirals. The central bank held its benchmark rate unchanged at 3.5% to 3.75%, marking the fifth consecutive meeting with no adjustment. Economists say the statement marks a shift in tone under new Chair Kevin Warsh, who replaced Jerome Powell and has pledged to return inflation to the Fed’s 2% target while deliberately withholding forward guidance that markets relied on under previous leadership.

Key Takeaways

  • The Federal Reserve warned in its July 2026 meeting minutes that years of above-target inflation could begin affecting wage and price expectations, signaling concern about a potential wage-price spiral.
  • The central bank held its benchmark rate unchanged at 3.5% to 3.75% for the fifth consecutive meeting, while inflation stood at 3.5% in June 2026, well above the Fed’s 2% target.
  • Nearly half of Federal Reserve policymakers said they would support a rate hike later in 2026, as oil prices topped $100 per barrel and added fresh upward pressure on inflation.
  • Historical precedent from the 1970s shows that once inflation expectations become entrenched, the Fed typically responds with aggressive rate hikes that can trigger recession and double-digit unemployment.
  • Fed Chair Kevin Warsh has reduced forward guidance since taking office in May 2026, leaving markets uncertain and increasing the probability of policy surprises at future meetings.

Consumer price inflation stood at 4.2% in May 2026, more than double the Federal Reserve target, before falling to 3.5% in June. Market Daily analysis shows the Fed’s language echoes warnings issued in the 1970s before inflation expectations became unmoored, requiring painful interest rate increases that pushed unemployment above 10%. Nearly half of policymakers said they would support a rate hike later in 2026. Oil prices topped $100 per barrel last week, adding fresh upward pressure on inflation.

interest rate chart
Photo Credit: Unsplash.com

Why Is the Fed Warning About Inflation Expectations?

The Federal Reserve’s concern centers on a phenomenon economists call a wage-price spiral, where workers demand higher wages to keep pace with rising prices, prompting businesses to raise prices further to cover increased labor costs. The cycle becomes self-reinforcing once the public expects inflation to persist. The Federal Open Market Committee held its July meeting on Wednesday, July 29, 2026, at 2:00 p.m. ET, with Chair Kevin Warsh leading his second policy meeting since taking office in May.

Inflation has run above the 2% target for several years, raising the risk that households and businesses will adjust their behavior permanently. Many businesses have told the Fed they face real pressure and are weighing how much of rising costs to pass along to customers, according to the meeting minutes. That adjustment in expectations is precisely what the central bank seeks to prevent, because once it takes hold, inflation becomes far harder to control.

Warsh declined to submit individual economic projections at the Fed’s June meeting, departing from recent practice of telegraphing outcomes beforehand. His reduced forward guidance has left investors uncertain about the Fed’s next moves. CME Group’s FedWatch tool showed a 36% probability of a rate hike at the July meeting and roughly 30% odds at the time the minutes were released.

What Does History Say Happens Next?

The 1970s provide the clearest historical parallel. After a decade of high inflation and half-measures, the public assumed prices would keep climbing and set wages and prices accordingly. Fed Chair Paul Volcker pushed the federal funds rate to 20% in 1981, causing a recession as unemployment climbed to 10.8%, the worst since the Great Depression. Inflation fell from more than 14% in 1980 to 3.5% a few years later.

Researchers later concluded that roughly half of that improvement came from something more abstract than rate hikes alone. People started believing the Fed could actually control runaway prices. Credibility became as important as the policy rate itself.

The 2022 inflation spike offers a contrasting case. Inflation topped 7%, but the Fed hiked rates quickly and expectations barely budged. While inflation never returned below the 2% target and reached 4.2% in May 2026, no wage-price spiral formed. The difference was timing and credibility: the Fed moved while the public still trusted it could deliver on its mandate.

How Are Markets Reacting to Warsh’s Approach?

‘The upcoming FOMC meeting will be the first in quite some time that a large portion of observers will get an outcome they did not anticipate,’ wrote Padhraic Garvey, ING’s regional head of research for the Americas. Investors have grown uncertain whether the Federal Reserve will raise rates or hold them steady, a marked shift from recent years when Fed officials telegraphed meeting outcomes well in advance.

Warsh’s vague communication style has increased market volatility and left traders scrambling to interpret subtle shifts in language. ‘The Fed will find holding steady a harder case to make than it looked even a few weeks ago,’ noted Nigel Green, CEO of deVere Group, in a July 23 email. Oil prices surged in recent weeks, topping $100 per barrel last week before hovering around $90, suggesting inflation may remain stubborn in the near term.

Gregory Daco, chief economist for EY-Parthenon, said in a July 22 email that ‘while a July rate hike remains highly unlikely, the September FOMC meeting could become the first meaningful test of whether the recent improvement in inflation proves durable.’ He added that his base case remains the Fed staying on hold through the rest of the year, ‘but it’s a 60-40 call.’

Could Rate Hikes Derail Economic Growth?

Today’s economy differs from the 1970s in crucial ways. The current environment relies heavily on cheap debt, particularly for the artificial intelligence buildout that has driven much of the stock market’s recent gains. Rate hikes don’t need to reach 20% to do damage this time. Even modest increases could disrupt financing for data centers, chip manufacturing, and other capital-intensive AI infrastructure.

A rate hike would help Warsh show ‘he means business’ in fighting inflation, wrote Richard de Chazal, macro analyst at William Blair. But such a move could surprise markets and lead to volatility, a trade-off Warsh may be willing to make if the Fed leans toward hiking in September anyway. Under the previous regime, avoiding surprises was often viewed as a policy objective itself. Under Warsh’s leadership, restoring anti-inflation credibility may be the higher priority.

Michael Gapen, chief U.S. economist at Morgan Stanley, sees the Fed staying on hold at the July meeting, noting that inflation has shown enough improvement to buy more time. But he acknowledges Warsh ‘may have a much more hawkish reaction function than we think,’ making him more inclined to raise rates. The main question is whether the Fed has run out of patience.

What Remains Unresolved for Investors and Businesses?

The Federal Reserve faces scenarios where inflation comes down if the Iran war calms, tariff impacts remain muted, and rent prices keep softening. But officials also see risks of sustained conflict keeping oil prices higher while the artificial intelligence buildout drives prices up. Inflation remains at 3.5% annually, well above the 2% target, and assuredly not heading in the right direction fast enough for policymakers’ comfort.

Joseph Abate, U.S. rates strategist at SMBC, suggests some of the haziness around Fed policy is likely temporary, since markets haven’t learned to read Warsh just yet. As he speaks publicly more often, investors will better understand his reaction function and policy priorities. But that learning curve means heightened uncertainty and volatility in the near term, particularly around September’s meeting.

Garvey of ING wrote that June’s cooler inflation data, thanks to lower gas prices, should give the Fed breathing room to keep rates steady. But he noted a ‘protective hike’ remains possible, which would enhance Warsh’s credibility as an inflation-fighter early in his tenure. ‘We don’t call for a hike, but can see how it could happen,’ Garvey wrote. Whether the Fed moves in July, September, or later, the 11-word warning makes clear that policymakers are watching inflation expectations as closely as the price data itself.


FAQs

What Is a Wage-price Spiral and Why Does the Fed Worry About It?

A wage-price spiral occurs when workers demand higher wages to keep pace with rising prices, prompting businesses to raise prices further to cover increased labor costs. The cycle becomes self-reinforcing once the public expects inflation to persist. Once expectations become entrenched, inflation becomes far harder to control and typically requires aggressive interest rate increases to break the pattern.

How High Did Interest Rates Go the Last Time the Fed Fought Entrenched Inflation?

Fed Chair Paul Volcker pushed the federal funds rate to 20% in 1981 to break the wage-price spiral that developed in the 1970s. The aggressive rate hikes caused a recession with unemployment climbing to 10.8%, the worst since the Great Depression. Inflation fell from more than 14% in 1980 to 3.5% a few years later.

Why Has Kevin Warsh Stopped Giving Markets Forward Guidance?

Warsh, a long-time critic of past market steering, deliberately pulled back on forward guidance when he became Fed Chair in May 2026. He believes restoring anti-inflation credibility should take priority over avoiding market surprises. This represents a departure from recent practice where Fed officials telegraphed meeting outcomes beforehand to keep volatility low.

What Is the Current Probability That the Fed Will Raise Rates?

CME Group’s FedWatch tool showed a 36% probability of a rate hike at the July 2026 meeting, with roughly 30% odds cited at the time the meeting minutes were released. This represents unusually high uncertainty compared to recent years. Most economists still expect the Fed to hold rates steady, but nearly half of policymakers have said they would support a hike later in 2026.

Could Rate Hikes Affect the Artificial Intelligence Boom?

Even modest rate increases could disrupt financing for AI infrastructure such as data centers and chip manufacturing, which rely heavily on cheap debt. The current economy is wired differently than the 1970s, and rate hikes don’t need to reach 20% to do damage. Higher borrowing costs could slow the capital-intensive AI buildout that has driven much of the stock market’s recent gains.

Oil and Gas Mastered the Drill Bit. Its Back Office Still Runs on PDFs. Austin Williams Is Betting on the Data Layer.

By: Daniel Rowe

On a modern drilling pad in the Permian Basin, an operator can steer a horizontal well from a screen, monitor downhole conditions in real time, and adjust a completion schedule on the fly. Ask that same operator what one of those wells actually earned last month, and the answer often lives somewhere far less impressive: a stack of PDF statements, a spreadsheet built by a controller who left years ago, and an accounting export nobody has had time to reconcile.

That gap between field technology and back-office reality is the market Austin Williams has spent his career staring at. After sixteen years inside oil and gas accounting departments, the Texas-born accountant founded Upstream, a Dallas-Fort Worth firm whose platform, Upstream+, is built on a pointed claim.

“Upstream+ is not accounting software,” Williams says. “It is a central command center for oil and gas assets.”

The distinction matters more than it might sound. Accounting software is built for the accountant. It posts journal entries, runs the monthly close, and files the returns. It was never designed for the operator, the mineral owner, or the capital partner who needs to know right now whether lease operating expenses on a well are on trend, off trend, or quietly eating margin. Those users have historically had one option: ask the accounting department for a custom report, then wait.

Upstream+ approaches the problem from the decision-maker’s side of the desk. The platform bolts onto whatever accounting system a company already runs, from enterprise oil and gas suites down to QuickBooks, and unifies the data those systems hold. Users get a fully interactive lease operating statement that can be sliced down to the pumper, the producing formation, the API number, or the individual invoice. The platform is built around Williams’ belief that the Lease Operating Statement should serve as the operational hub where financial and operational data come together, rather than remaining a static accounting report. Budgets can be compared against actuals at the AFE level and drilled through to the underlying charge. A report writer lets an owner or manager answer their own questions without waiting in line, and custom dashboards track the metrics a specific operation cares about.

The design reflects a frustration Williams watched play out at every stop of his career. When well data is fragmented across accounting systems, spreadsheets, and email attachments, every question from a chief executive, a geologist, or a field manager becomes a small research project. An accountant has to stop closing the books, export data, rebuild it by hand, and send back a one-off answer that is stale almost as soon as it lands. “A full week of strategic work becomes a full week of explaining bills,” Williams says.

The platform’s origin story is unusually literal. As a young revenue accountant at Pioneer Natural Resources in 2009, Williams built a side spreadsheet simply to check the output of an aging AS400 system whose reports he found unreadable. He kept refining that workbook through roles at Trey Resources, Wagner, Overton Park, and Strawn, and later while helping build the outsourcing practice at consulting firm Embark, adapting it to every accounting system and every operator question he encountered along the way.

By the time he founded his own firm in 2024, something curious had happened. Clients were hiring the company for outsourced accounting, but the tool had become the one thing that truly set the firm apart. The turning point came in late 2025, when Williams stopped treating the workbook as a free client perk and rebuilt it as Upstream+, a decision command center. The push came from the person closest to his work. His wife pointed out over the kitchen table that the tool he kept giving away was the reason clients kept coming back.

The timing tracks with two pressures reshaping the industry’s back offices. The first is staffing. Experienced oil and gas accountants are retiring faster than they are being replaced, and the specialty is niche enough that generalist accountants rarely step in. Lean teams are doing the work of larger ones, which leaves little time for analysis. The second is transaction volume. Wells change hands constantly through divestitures, acquisitions, and recapitalizations, and the operating history rarely travels with the asset.

“The new owner gets a folder of PDFs and Excel workbooks,” Williams says. “Almost never the operating history at the well level. Almost never the trend data that would let them make a real decision in their first ninety days.” He says he has watched operators spend $100,000 to $200,000 on accounting services simply to reconstruct their own asset history after a purchase. Upstream+ is built to export a well’s full operating history as one structured upload, so the data moves when the asset does.

The company is also developing automation for non-operated interest owners, a corner of the market that still runs heavily on paper. Non-op investors and mineral owners receive joint interest billings and revenue statements as PDFs, which then have to be typed into spreadsheets line by line before tax season. Upstream+ is working towards converting those statement stacks into uploadable data files in minutes rather than days, drawing on sixteen years of experience working with statement formats.

The business model is deliberately unflashy. On the services side, Upstream bills fixed fees rather than hourly rates, a stance Williams frames as a matter of principle. “You sign a number, and that is the number,” he says. For Upstream+, pricing is designed to encourage adoption rather than maximize short-term margins, part of a stated ambition to make the platform the standard interactive lease operating statement for the industry.

According to the company, more than forty independent producers, non-operators, and private-equity-backed operators work with Upstream today, and the firm co-sources more than four thousand well operations across its client base.

Whether Upstream+ becomes an industry standard or simply a very useful tool for its clients, the thesis behind it is difficult to argue with. An industry that mastered horizontal drilling still, in many offices, makes million-dollar decisions from static spreadsheets. Williams is betting the next competitive edge won’t be found beneath the surface. It will come from finally making sense of the information already sitting above it.

More information about the platform is available on the Upstream+ website, and Williams shares his industry commentary on LinkedIn.

Professional Services Firms Are Sitting on Their Highly Valuable Asset. Many of Them Can’t Find It.

By: Robert Nelles

As AI compresses billable work from weeks to seconds, a former consulting executive says the industry’s real problem is older than the technology. Firms forget what they know.

Every professional services firm sells the same underlying product: accumulated expertise. Decades of engagements, proposals, contracts, and hard-won judgment. Yet ask a partner at almost any consulting, accounting, or advisory firm to produce the details of a similar project from six years ago, and the search begins. Someone remembers who ran the account. That person is on vacation. The files are on a drive nobody opens anymore.

Daniel Cohen-Dumani spent three decades inside that reality, first as a consultant in Switzerland at the firm now known as Accenture, then as founder of Portal Solutions, a technology consultancy he grew from a team of one to 60 before its acquisition by a large accounting firm in 2017. His diagnosis of the industry is blunt.

“Your firm knows more than it can find,” he says. “Decades of expertise, scattered across drives, inboxes, and people’s heads. Everyone reinvents the wheel because nobody can find what the firm already knows.”

The problem is not new. Knowledge management systems have promised to solve it for thirty years, and Cohen-Dumani built plenty of them. What changed, he argues, is the physics. Large language models can finally read unstructured information at scale, understand context, and retrieve meaning without armies of people tagging documents. “LLMs didn’t improve knowledge management,” he says. “They replaced its physics.”

That conviction led him to found Experio Labs, a company building what it calls organizational memory for high-stakes professional services firms. Its intelligence layer, IQ1, connects to a firm’s institutional knowledge and answers questions that general-purpose AI tools cannot reach. The company’s benchmark example: show every active contract signed in the last ten years with a general-liability clause in excess of $2 million. Generic assistants, Cohen-Dumani notes, go quiet on queries like that. Experio returns the matching contracts in seconds, with the exact clause and source document cited.

The same gap shows up in more mundane moments. A managing partner needs a full briefing on a client before a meeting that starts within the hour. In most firms, that request sets off a chase. Someone has to find out who ran the account, get on their calendar, and sit through a conversation that begins with “honestly, that project was six months ago,” then wait while the history is reconstructed from old decks and memory. Days pass, sometimes weeks. Experio’s answer to the same request is the full engagement history, the people involved, the work product, and the open risks, assembled in seconds and cited to its sources, reliable enough to walk into the room with.

The citation requirement is not a detail. In work where an error becomes a liability, Cohen-Dumani holds a hard line the industry is only beginning to adopt. Answers must be traceable to their source, and a system should say “I don’t have that” rather than guess. “An answer without a source is a guess wearing a suit,” he says. The company describes its retrieval as highly accurate with zero tolerance for fabricated answers, a standard it argues should be table stakes for any AI operating in professional services.

He is equally direct about why impressive demonstrations so often collapse in production. Run a language model across a large knowledge base at scale, he warns, and meaning quietly erodes. Context drifts, similar concepts blur, and the system that dazzled on day one degrades by document one hundred thousand. He calls the phenomenon semantic decay, and much of Experio’s engineering, from knowledge graphs to retrieval discipline to keeping humans in the loop, exists to fight it. Accuracy, in his framing, is not a launch-day number but a property a firm must actively defend.

Cohen-Dumani describes the knowledge available to AI as three layers. The first is the internet, what every generic tool knows, impressive and identical for everyone. The second is the industry, its vocabulary, its regulatory weight, and the way work actually gets done in a vertical. The third is the firm itself, the engagements, precedents, and judgment nobody else possesses. The uncomfortable truth for buyers, he argues, is that competitive advantage lives almost entirely in the layer generic tools cannot see. Nor does he expect the frontier laboratories to close that gap on their own. Some problems live so deep inside one industry that a general model never reaches them, he says. A better base model makes vertical products stronger. It does not make them unnecessary.

The market timing is uncomfortable for the industry’s dominant business model. When work that took eight hours takes seconds, firms that bill by the hour face what Cohen-Dumani calls an existential question rather than a productivity upgrade. Firms that pool and retain their knowledge, he argues, will compound the advantage. Firms that let expertise walk out the door with every retirement will pay for the same lessons twice.

Where the value shows up, he says, is in areas firm leaders already watch. A firm can prove its experience in the room instead of asserting it. Obligations buried across ten years of contracts surface before they become surprises. And a junior hire can reach the firm’s full memory on day one instead of year five, without interrupting the partners who have become, in his phrase, the firm’s only search engine.

The onboarding math alone tends to catch the attention of managing partners. The most expensive part of a new hire, Cohen-Dumani observes, is not the salary but the years of context they lack, a ramp firms have simply accepted as the cost of growing a team. Give the first-year associate the firm’s memory on the first morning and the apprenticeship accelerates rather than disappears. Juniors move like veterans, and veterans stop fielding the same questions for the hundredth time in their careers.

He is careful, however, to draw a line under the automation narrative. Cohen-Dumani estimates AI will eventually handle 80 percent of consulting work: the research, the drafting, the finding. The remaining 20 percent: judgment, relationships, and the instinct that reads a room, stays human. “The goal isn’t to remove the human,” he says. “It’s to give the human their time back.”

None of this strikes him as radical, and that is precisely his point. For an industry built on knowing things, the next competitive edge may be deceptively simple. It is being able to find what you already know. Cohen-Dumani’s bet is that the firms that solve it first will own the decade, and that the ones waiting to be convinced will spend it catching up.

Middle-Market Debt Refinancing Timing Hits Critical Phase

Companies facing debt maturities over the next two years must decide now whether to refinance early, extend terms, or risk entering distressed territory. Middle-market borrowers confront a compressed decision window as maturing loans stack up while credit terms tighten and lender appetite narrows. The stakes are straightforward: debt refinancing timing determines whether a company secures capital on manageable terms or scrambles for expensive rescue financing when options evaporate.

Key Takeaways

  • Middle-market borrowers face compressed refinancing windows 18 to 24 months before debt maturity, with fewer funding alternatives than large corporations.
  • Delaying refinancing until the final six months before maturity triggers higher rates, shorter terms, and stricter covenants as lenders price in risk.
  • Amend-and-extend transactions offer faster relief but lock in higher pricing, while full refinancing resets terms but requires months of negotiation.
  • Asset-based lending provides high advance rates against collateral but imposes intensive monitoring and tighter operational restrictions.
  • Covenant breaches during refinancing discussions give lenders leverage to reprice terms or demand additional collateral even without formal default.

A maturity wall forms when a large volume of debt comes due within a concentrated period, forcing borrowers to compete for refinancing capital at the same time. For middle-market firms, those walls typically emerge 18 to 24 months ahead of actual maturity dates, the point at which lenders and credit committees begin re-evaluating risk and pricing new terms. Market Daily analysis shows that borrowers who wait until the final six months before maturity face sharply higher rates, shorter amortization schedules, and stricter covenants as lenders price in refinancing risk.

Why Middle-Market Borrowers Face Greater Pressure Than Large Corporations

Middle-market companies lack the diversified funding sources and syndicated loan access that large corporations command. A manufacturer with annual revenue between fifty million and five hundred million dollars typically relies on a single relationship bank or a small group of regional lenders. When that credit line matures, alternatives are limited.

business loan negotiation meeting
Photo by Vitaly Gariev on Unsplash

Large public companies can tap bond markets, private placements, or multi-bank syndicates. Middle-market firms cannot. They negotiate directly with lenders who hold significant leverage, and those lenders know switching costs are high. If the original lender declines to refinance or demands punitive pricing, the borrower must court new banks that lack institutional knowledge of the business and require months of due diligence.

Private equity-backed companies face additional complexity. Sponsor-owned businesses often carry higher leverage ratios than independent firms, and lenders scrutinize covenant compliance and cash flow coverage more closely. When a portfolio company approaches maturity, the private equity sponsor must decide whether to inject fresh equity, broker a lender amendment, or initiate a sale process. Each path has different timing requirements and cost implications.

What Happens When Companies Delay Refinancing Decisions

Waiting too long compresses negotiating leverage. Lenders recognize desperation and price it accordingly. A borrower entering discussions six months before maturity signals either poor planning or deteriorating financial health, both of which justify higher spreads and tighter terms.

Credit committees at regional banks and specialty finance firms review maturity schedules quarterly. When a borrower appears on that list without having initiated refinancing conversations, the lender’s workout team often gets involved earlier. That shift changes the relationship from partnership to risk management. Workout specialists focus on collateral coverage, cross-default clauses, and exit strategies rather than growth capital or long-term partnership.

Delayed refinancing also limits flexibility. A company that starts early can explore multiple lenders, compare term sheets, and structure covenants that preserve operating room. A late starter accepts the first viable offer because running out of time means defaulting, which triggers cross-default provisions across other credit agreements and vendor contracts. Default cascades quickly in the middle market, where thin capital cushions leave little room for error.

How Interest Rate Cycles Reshape Maturity Wall Strategy

Rising rates amplify refinancing pressure, but falling rates create their own traps. When borrowing costs climb, companies face higher debt service burdens that shrink cash flow coverage ratios and tighten covenant compliance. Lenders demand more equity contribution or subordinated debt to maintain the same leverage multiples, forcing borrowers to dilute ownership or accept mezzanine financing with double-digit rates.

Falling rates tempt borrowers to wait for better pricing. That gamble backfires when credit spreads widen even as benchmark rates fall. The total cost of borrowing reflects both the base rate and the credit spread lenders charge above it. A company that delays refinancing hoping for lower rates may find that spread widening offsets any base-rate decline, leaving the all-in cost unchanged or higher.

Rate volatility also affects covenant structures. Fixed-rate debt locks in predictable payments but limits flexibility to prepay or amend terms. Floating-rate debt offers prepayment freedom but exposes borrowers to rate spikes that can violate debt service coverage covenants. Choosing the wrong structure early in a cycle can trap a company in unsustainable terms as market conditions shift.

Refinancing Windows and Market Liquidity

Credit markets operate in cycles, and liquidity varies sharply across them. A borrower seeking refinancing during a liquidity crunch faces not only higher rates but fewer willing lenders. Regional banks pull back when regulatory scrutiny increases or their own balance sheets tighten. Specialty finance firms raise pricing and demand more collateral when defaults rise industry-wide.

Companies that refinance during periods of ample liquidity secure better terms and preserve relationships. Those forced to refinance during credit contractions accept whatever capital they can find. The difference between proactive and reactive timing can mean hundreds of basis points in interest cost and years of operational constraint from restrictive covenants.

Which Covenant Breaches Trigger Immediate Lender Action

Covenants fall into two categories: financial and operational. Financial covenants measure leverage ratios, debt service coverage, and minimum liquidity thresholds. Operational covenants restrict asset sales, capital expenditures, and dividend payments. Breaching either type gives lenders the right to accelerate repayment, but not all breaches trigger the same response.

Lenders tolerate minor technical breaches if the underlying business remains sound. A company that misses a leverage covenant by a small margin due to a one-time charge often receives a waiver in exchange for an amendment fee and slightly higher pricing. Repeated breaches or deteriorating cash flow prompt different treatment. The lender calls a default, freezes the credit line, and demands immediate repayment or a comprehensive restructuring.

Material adverse change clauses give lenders broad discretion to revalue collateral or demand additional guarantees when business conditions shift. These clauses activate during refinancing discussions, allowing lenders to reprice terms even if no covenant breach occurred. A borrower facing maturity with declining revenue or compressed margins will see those conditions reflected in the refinancing offer, often through shorter terms or increased collateral requirements.

Amend-and-Extend Versus Full Refinancing

An amend-and-extend transaction modifies the existing credit agreement to push out the maturity date, usually in exchange for higher pricing or tighter covenants. It’s faster and cheaper than a full refinancing because it avoids the legal and diligence costs of replacing the loan entirely. Middle-market borrowers use this route when they need more time but cannot justify the expense of a new facility.

Full refinancing replaces the existing debt with a new loan, resetting terms and often changing lenders. This path makes sense when market conditions have improved, the company’s credit profile strengthened, or the existing lender relationship deteriorated. A borrower that has reduced leverage or improved profitability since the original loan can often secure lower rates and fewer restrictions through a competitive refinancing process.

The choice depends on relative cost and strategic flexibility. An amend-and-extend preserves the existing lender relationship but locks in higher pricing for the extended term. A full refinancing opens the door to better terms but requires months of negotiation and due diligence. Companies typically run both processes in parallel, using competitive term sheets to negotiate better amendment terms with the incumbent lender.

Asset-Based Lending as a Maturity Stopgap

Asset-based lending relies on accounts receivable, inventory, and equipment as collateral rather than cash flow coverage. It offers higher advance rates than traditional term loans but comes with more intensive monitoring and tighter borrowing base restrictions. Middle-market companies with strong asset bases but inconsistent cash flow often turn to asset-based facilities when term loan refinancing proves too expensive.

industrial warehouse inventory collateral
Photo by Alberto Rodríguez on Unsplash

The tradeoff is control. Asset-based lenders conduct frequent collateral audits, impose stricter reporting requirements, and reserve the right to reduce availability if collateral quality deteriorates. Borrowers gain access to capital but sacrifice operational flexibility. They must manage working capital to maintain borrowing base availability, which can force difficult decisions around inventory levels and receivables collection.

Asset-based lending works best as bridge financing rather than a permanent solution. A company facing near-term maturity without strong enough cash flow for a traditional refinancing can use an asset-based facility to buy time, then refinance into a cash-flow loan once performance improves. The key is avoiding dependency: asset-based facilities are expensive and restrictive, suitable for tactical use but not long-term capital structure.

Debt refinancing timing is rarely a purely financial calculation. It reflects management’s assessment of market conditions, lender relationships, and the company’s own trajectory. Borrowers who treat maturity walls as distant problems rather than imminent decisions often find their options narrowing faster than their financial forecasts predicted. The cost of waiting is measured not just in basis points but in strategic flexibility lost when the calendar runs out.


FAQs

How Far in Advance Should a Middle-market Company Start Refinancing Discussions?

Most lenders expect to see refinancing conversations begin 12 to 18 months before maturity. Starting earlier allows time to compare multiple term sheets, negotiate covenant flexibility, and avoid the appearance of distress that drives up pricing.

What Happens If a Company Cannot Refinance Before Maturity?

The lender can declare a default and demand immediate repayment, freeze the credit line, or push the borrower into a workout process. Cross-default clauses often trigger defaults across other agreements, creating a cascade that can force asset sales or bankruptcy.

Do Private Equity Sponsors Typically Inject Equity to Help Portfolio Companies Refinance?

Sponsors will inject equity if the investment thesis remains intact and the company’s long-term prospects justify additional capital. If performance has deteriorated, sponsors often prefer to negotiate lender amendments or initiate a sale process rather than commit more funds.

Can a Company Refinance With a Different Lender If the Existing Bank Refuses?

Yes, but switching lenders requires extensive due diligence, legal documentation, and often higher pricing because the new lender lacks institutional knowledge of the business. The process typically takes three to six months, so companies must start well before maturity.

How Do Rising Interest Rates Affect Refinancing Covenant Structures?

Higher rates reduce debt service coverage ratios, making it harder to comply with financial covenants. Lenders respond by demanding lower leverage multiples, higher minimum liquidity, or additional equity contributions to maintain the same credit risk profile.

What Is a Borrowing Base in Asset-based Lending?

A borrowing base calculates how much a company can borrow based on eligible collateral values, typically a percentage of accounts receivable and inventory. Lenders audit collateral regularly and reduce availability if quality deteriorates, which can cut off access to capital mid-cycle.

Are Amendment Fees Negotiable During an Amend-and-extend Transaction?

Amendment fees are negotiable, but lenders hold leverage when maturity approaches. Companies with strong performance and alternative lender interest can negotiate lower fees, while those with limited options often pay one to two percent of the outstanding loan balance.

What Role Do Credit Rating Agencies Play in Middle-market Refinancing?

Most middle-market companies do not carry public credit ratings, so rating agencies play little direct role. However, lenders rely on internal credit scores and third-party risk models that function similarly, and deteriorating scores raise refinancing costs even without a formal rating.