
As investors reconsider the role of precious metals in their portfolios, Bishop Gold Group says understanding what an investor actually owns may be just as important as deciding to gain exposure to gold in the first place.
Gold is often discussed as though it were a single investment category. In practice, however, there are several very different ways to participate in the gold market.
An investor might purchase physical coins or bars, buy shares of a gold-focused exchange-traded fund, invest in mining companies, or hold precious metals through certain retirement-account structures. Each may provide some connection to the gold market, but they do not necessarily provide the same ownership experience, risks, costs, or level of control.
According to Bishop Gold Group, understanding those distinctions is an important part of evaluating precious metals.
For investors considering gold as part of a broader diversification strategy, the first question may therefore be more specific than simply, “Should I own gold?”
It may be: “What exactly do I want to own?”
Gold Exposure Can Take Different Forms
One of the simplest distinctions is between owning physical gold and owning a financial instrument whose value is connected in some way to the gold market.
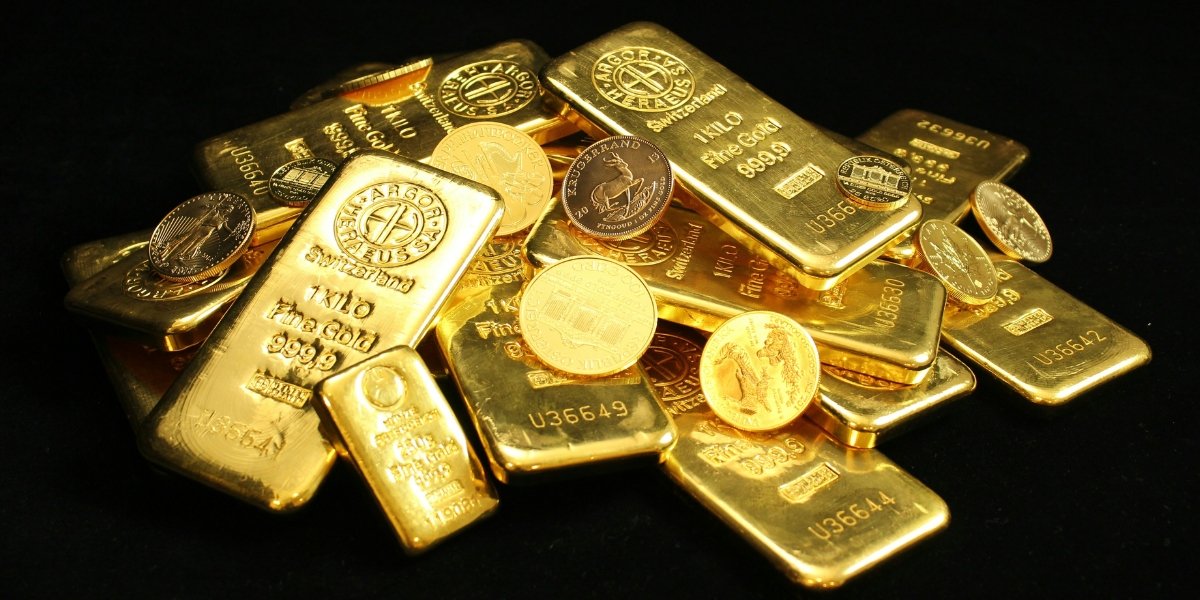
Physical gold generally refers to bullion products such as coins and bars. Once a transaction is completed, the buyer owns a tangible asset that must be delivered, stored, insured or otherwise safeguarded.
Other approaches can provide gold-related exposure without requiring the investor to personally take possession of metal. Exchange-traded products, for example, may allow investors to buy and sell shares through brokerage accounts. Gold-mining stocks provide another type of exposure, but their performance depends not only on the price of gold, but also on the financial and operational performance of the underlying companies.
These distinctions matter because two investors who both say they “invest in gold” may actually own fundamentally different assets.
Physical Ownership Changes the Relationship With the Asset
For some buyers, the tangible nature of physical gold is part of its appeal.
Unlike a stock or fund represented by an entry in a brokerage account, a gold coin or bar is a physical asset. Depending on the ownership arrangement, the owner may take direct possession or arrange for storage through a third party.
That tangibility can provide a degree of control that certain investors specifically seek. At the same time, it introduces responsibilities that do not necessarily exist with securities held electronically.
Physical gold must be securely stored. Insurance considerations may arise. Buyers should retain transaction and ownership records, understand applicable premiums and fees, and know how the asset could eventually be sold or transferred.
Bishop Gold Group emphasizes that these practical considerations should be understood before a transaction takes place rather than after the metal has already been purchased.
Convenience and Control Are Not Necessarily the Same Thing
Financial products connected to gold may offer conveniences that physical ownership does not.
Shares of publicly traded gold-related products can generally be bought and sold through brokerage platforms during market hours. Investors do not typically need to personally arrange transportation or physical storage of the underlying asset.
Physical gold works differently.
Buying or selling bullion may involve communicating with a dealer, receiving a quote, arranging payment or settlement, completing verification procedures, and coordinating delivery or storage.
Neither structure is inherently appropriate for every investor. Instead, the distinction illustrates an important tradeoff: the structure offering the greatest convenience may not necessarily provide the same form of ownership or control as possessing the underlying physical asset.
That difference can be particularly relevant for investors whose interest in precious metals is motivated by diversification beyond conventional financial accounts.
Investors Should Understand What They Are Trying to Accomplish
The appropriate form of gold exposure depends largely on the investor’s objective.
Someone interested primarily in short-term price movements may approach the market differently from someone purchasing physical bullion as a long-term holding. A retirement investor may face another set of considerations involving account structure, custodians, eligible precious metals, and storage requirements.
Before selecting a product, investors can consider several questions.
Do they want direct ownership of physical metal? How important is immediate liquidity? Are they comfortable arranging storage? What fees will apply when buying, holding, and eventually selling the asset? Is the objective short-term market exposure, long-term diversification, retirement planning, or tangible ownership?
Answering those questions can make it easier to compare options on their actual characteristics rather than treating every gold-related product as interchangeable.
Physical Gold Also Has Costs and Risks
Direct ownership should not be interpreted as eliminating investment risk.
Gold prices fluctuate, and physical gold does not ordinarily produce interest or dividends. Buyers may also pay premiums above the prevailing market price, along with potential shipping, insurance, storage, or administrative expenses.
When the metal is eventually sold, the price offered by a dealer or other buyer may differ from the price at which similar products are being sold to consumers.
These costs can affect the financial outcome of ownership and should be considered alongside the perceived benefits of holding a tangible asset.
Bishop Gold Group encourages consumers to understand the complete transaction, including pricing, premiums, storage arrangements, delivery procedures, and potential resale options, before making a purchase.
Education Becomes More Important as the Options Expand
The number of ways investors can gain exposure to gold makes financial literacy particularly important.
Consumers should understand whether they are purchasing physical metal, shares of a fund, stock in a mining company, or another gold-related financial product. They should also distinguish general educational information from individualized investment, tax or legal advice.
For physical precious metals, buyers can request written information regarding pricing, fees, delivery, storage, and resale procedures. Investors considering securities or retirement accounts should similarly review the applicable disclosures, expenses and regulatory requirements.
Gold has been owned and traded for centuries, but modern investors now have more ways to participate in the market than previous generations did.
That variety creates choice, but it can also create confusion.
For Bishop Gold Group, the distinction ultimately comes back to investor education. Understanding the difference between owning gold itself and owning something connected to gold allows consumers to evaluate the asset based on what they actually want from it.
For investors who value tangible ownership, physical gold may offer characteristics that financial products cannot replicate. For others, different forms of exposure may better fit their liquidity needs, risk tolerance, or financial objectives.
The important point is understanding the difference before making the decision.
Gold-related investments and physical precious metals involve risk and may lose value. Gold does not guarantee protection against inflation, market declines, or other financial losses. Investors should consider their individual circumstances and consult appropriately qualified financial, tax or legal professionals when necessary.
Disclaimer: This article is for informational purposes only and does not constitute financial, investment, tax or legal advice. Gold and other precious metals involve risk, may lose value and do not guarantee protection against inflation, market declines or other financial losses. Investors should evaluate their individual circumstances and consult qualified professionals before making investment decisions.