Market Daily

Why Salamisso’s Community-First Approach Is Winning in the Market

By: Daniela Saycon

Developers often arrive in neighbourhoods with glossy plans and leave behind buildings that feel as if they could sit on any street in any city. Salamisso Developments has taken a quieter path, working to become part of the places where it builds rather than passing through. Founded on the legacy of Gilmer Properties and led by property developer Frank Gilmer, the Dublin-based company focuses on shaping projects that fit into existing communities in Ireland and the United Kingdom. Instead of chasing visibility for its own sake, it has placed steady emphasis on listening to residents, respecting local character, and delivering practical progress within each postcode.

Built With Neighbors, Not Just Numbers

​The company’s growing portfolio reflects this steady, grounded stance, with residential and mixed-use developments that respond to local needs rather than imposing a one-size-fits-all template. Its work includes schemes in Dublin’s Liberties and other urban districts where homes, senior living, retail, and medical spaces sit side by side, adding life to the street rather than pulling it away.

​

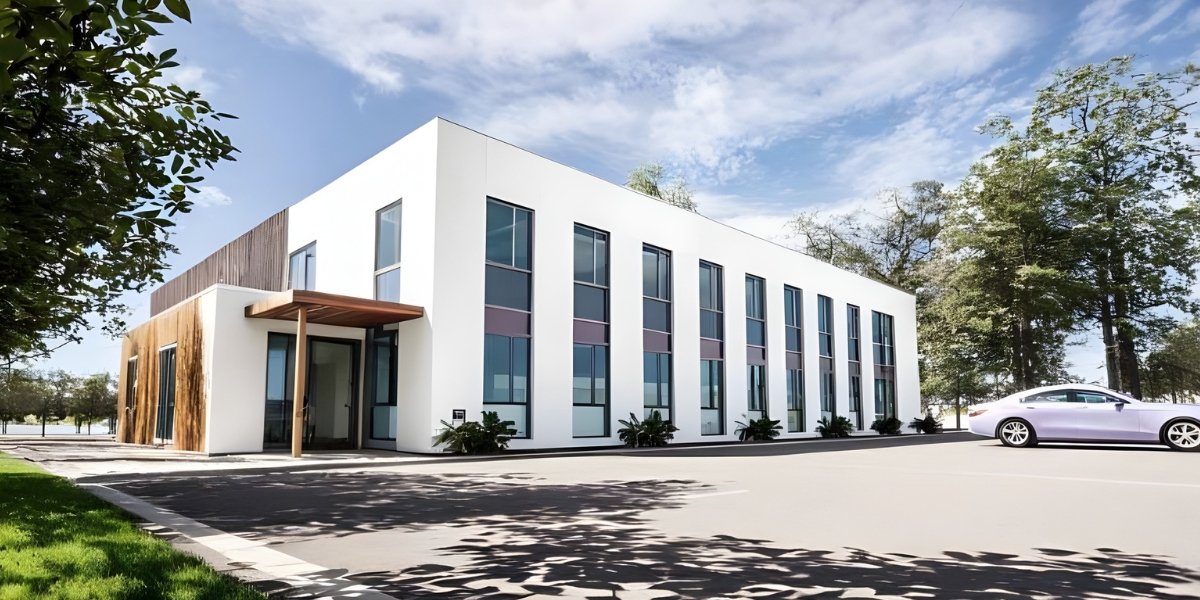
The Bradfield Road development, for example, adds 58 luxury apartments and commercial space, aiming to strengthen the surrounding neighbourhood’s rhythm rather than disrupt it. Meath Street and other schemes focus on daylight, walkability, and the needs of nearby traders, in contrast to large out-of-town projects that can weaken historic centres. “Designed with purpose, delivered with excellence,” the company says, and that statement aligns with how it presents and delivers its projects on the ground.

Community-First as Competitive Edge

Within property circles, the phrase “community-first” appears frequently, although practice sometimes lags behind the promise. Salamisso treats this idea as a guiding brief rather than a marketing decoration, working with local stakeholders, architects, and engineers so that each scheme aligns with its surroundings while still offering contemporary living standards, including near-zero-energy building–compliant homes and other sustainable features where appropriate.

This steady, consultative style supports more than good relations; it also underpins a pragmatic commercial strategy. A construction company that limits disruption, hands over projects on time and on budget, and leaves neighbourhoods feeling respected gains a reputation that supports long-term demand from residents, investors, and partners. In a search-driven environment where every name can be checked in seconds, this kind of grounded track record helps shape what people see when they look up “Salamisso” or “Frank Gilmer,” and it gives them concrete results to evaluate rather than noise.

The Market Is Taking Notes

Activity across Ireland and the United Kingdom, including several large-scale projects at different stages, shows that this deliberate mix of heritage awareness, community dialogue, and high-spec delivery can scale without losing its grounding. The team combines long-standing experience in finance and development with skills in marketing and project management, helping it maintain a focus on both the financial structure of a scheme and the lived experience of future occupants.

In a crowded property development sector, Salamisso distinguishes itself by being more than just a commercial developer. Instead of taking a detached approach, it positions itself as a steady caretaker of the communities where it works, ensuring that each project contributes positively to its surroundings. This contrasts with other developers who treat communities as an afterthought, focusing solely on construction. Salamisso understands that in today’s market, trust is a key asset. By delivering projects on time, respecting local character, and fostering positive relationships, the company allows its completed projects and residents’ lived experiences to speak for its commitment to quality and community integration. As the demand for socially responsible developments grows, Salamisso’s focus on community-first principles has become its competitive edge. With a long-term vision and clear values, the company continues to build both trust and value in every neighborhood it touches.

Global GDP Moderates, Unemployment Hits Lows: a 2026 Outlook

Global GDP growth kept a moderate pace into late 2025. It reflected softening trade dynamics and lingering policy uncertainties. Unemployment rates hit historic lows worldwide. They showed robust labor markets despite persistent informal employment challenges. These indicators paint a resilient yet uneven economic landscape as 2026 starts.​

Global GDP Moderation Trends

Headline GDP figures across major economies delivered positive annual growth that beat back recessionary pressures, even as the pace slowed from post-pandemic rebounds. Services and digital sectors pushed much of this expansion forward, offsetting manufacturing output hampered by supply constraints. Economists point out that external shocks like commodity volatility keep upside potential firmly in check.​

The global unemployment rate marked the tightest labor conditions in modern history. Adult rates stayed notably low while youth rates remained elevated. Women faced bigger challenges in informal work and pay scales than men did. These metrics show a labor market that’s absorbed prior shocks. But it’s strained by mismatched qualifications and precarious gigs.​

Unemployment Decline Signals

Real output growth trailed pre-2020 averages as demographic aging and elevated borrowing costs dragged it down. Investment flows chased AI infrastructure and low-carbon transitions, bolstering productivity even as consumer spending cooled off. Trade volumes grew modestly, limited by reconfigured supply chains that now favor resilience over efficiency.​

Global Economic Indicators Breakdown

Unemployment disparities laid bare deeper structural issues. Youth joblessness in developing regions screamed for skills alignment with tech-driven demands. Central banks weighed these indicators in recent policy pivots. They held rates steady as core inflation eased. Wage pressures didn’t fully let up though. Markets bet on gradual rate reductions paired with sustained GDP trajectories absent aggressive easing.

Seedlng Sprouting from Coins

Photo Credit: Unsplash.com

​

Sustainable investment trends boosted GDP signals. Green assets grabbed capital thanks to regulatory demands for verifiable ESG metrics. Corporate governance shifted. Boards now bake climate risks into core mandates. That shapes long-term growth outlooks. Consumer behavior leaned toward value-aligned spending. It kept service-led GDP humming despite trade-downs in durables.​

Youth unemployment gaps threaten to lock in inequality. Targeted upskilling offers the fix. Informal employment’s vast reach leaves billions exposed to income swings. Headline jobless rates improved anyway. These fault lines poke holes in the uniform recovery story that aggregate GDP gains suggest.​

Everyday consumers feel these indicators through job security in services and tech. Cost-of-living pressures hit hard from sticky inflation bits like housing. Families juggle essentials against discretionary spending. Informal workers suffer most without safety nets. Growth stumbles could spark social tensions.​

Investors and entrepreneurs tackle a “higher-for-longer-lite” rate world. AI and green plays promise productivity boosts. They demand rock-solid risk management in tight labor pools. Policymakers who skip youth and informal gaps court a derailed soft-landing. Inclusive policies matter now to grab 2026’s modest upside. Screw that up and stagnation hits markets plus main streets hard.

The Fed’s Most Dangerous Number Isn’t Inflation. It’s 4.6%

The Federal Reserve likes to say it has two mandates. Keep prices stable. Keep people working. In practice, those goals don’t always cooperate. When inflation cools, but employment holds firm, policymakers hesitate. When jobs soften but prices refuse to fully behave, hesitation turns into tension.

Right now, that tension is showing up in a single number the market can’t stop watching. The U.S. unemployment rate is hovering near 4.6%.

On its face, that figure looks harmless. By historical standards, it’s still low. By political standards, it’s survivable. By market standards, it’s quietly explosive.

Why Employment Still Sits At The Center Of Fed Thinking

Inflation gets the headlines, but employment drives confidence. The unemployment rate is one of the fastest, cleanest signals the Fed has about whether demand is overheating or cooling. When it stays low, labor demand is strong, wages tend to rise, and inflation pressure lingers. When it edges higher, slack starts to appear, wage growth slows, and price pressure eases.

Economic theory has a name for this balance point. NAIRU, the non accelerating inflation rate of unemployment. The idea is simple, even if the math isn’t. Below a certain unemployment level, inflation risks rise. Above it, those risks fade.

The Fed doesn’t publicly fixate on a single number, but most estimates place that neutral zone around 4.0% to 4.2%. That makes 4.6% uncomfortable. Not weak enough to panic. Not strong enough to ignore.

What The Chicago Fed Is Quietly Signaling

The Fed’s Most Dangerous Number Isn’t Inflation. It’s 4.6%

Photo Credit: Unsplash.com

Before the official jobs report even lands, the Federal Reserve Bank of Chicago runs real time labor market models using public and private data. Their latest estimate suggests unemployment held at about 4.6% in December, unchanged from November. Economists surveyed by the Bureau of Labor Statistics expected closer to 4.5%.

That difference looks trivial. Markets disagree.

The signal isn’t collapsing. It’s deceleration. Hiring has slowed. Layoffs haven’t surged. Workers aren’t flooding the unemployment line, but they’re not being pulled into new roles at the same pace either. Economists call it low hire, low fire. Investors call it a warning light.

Why Markets Are Pricing Cuts Without Believing In Them

Traders don’t wait for certainty. They price probabilities. Right now, those probabilities tell a careful story.

Markets see roughly a 10% chance of a rate cut at the Fed’s next meeting. In other words, almost no one expects an immediate move. By April, that changes. Odds rise to about 55% for at least one cut.

This isn’t optimism. It’s conditional logic.

If unemployment prints at 4.5% or lower, the Fed can justify patience. Labor demand would still look resilient enough to risk holding rates higher. If it sticks at 4.6% or drifts higher, the case for waiting weakens. The economy wouldn’t look broken, but it would look fragile enough to justify insurance cuts.

The Data That Actually Moves Policy

Unemployment alone doesn’t force the Fed’s hand. What matters is how it interacts with everything else.

If unemployment ticks up while inflation expectations remain elevated around 3.4%, policymakers face a tradeoff. Let growth slow further, or cut early and risk inflation reaccelerating.

Wage growth matters just as much. Slower hiring and softer wage gains ease inflation pressure and make cuts safer. Strong wages do the opposite, even if headline inflation behaves.

Inside the Federal Open Market Committee, these crosscurrents are widening divisions. Some officials see cooling labor as justification for easing. Others worry that cutting too early undermines credibility. The result is a Fed that’s more data dependent than ever and far less willing to commit.

Markets also look beyond the unemployment rate itself. Jobless claims, consumer confidence, and hiring intentions often shift first. When those weaken alongside unemployment, expectations for rate cuts harden quickly.

Why 4.6% Isn’t An Emergency, But Isn’t Comfort Either

A 4.6% unemployment rate doesn’t legally or mechanically trigger action. It alters the risk math.

At very low unemployment levels, the Fed worries about overheating. At sharply rising levels, it worries about a recession. In between, it worries about timing.

That middle zone is where policy mistakes happen. Cut too soon and inflation returns. Wait too long and economic damage compounds.

A moderate uptick like this supports the idea of a soft landing. Growth slows without breaking. Inflation cools without collapsing demand. In that scenario, rate cuts become a calibration tool rather than a rescue mission.

What This Means For Markets

Interest rates move first. Softer labor data pulls down expectations for future yields, reshaping Treasury curves and easing borrowing costs across credit markets.

Equities react next. Lower rate expectations boost valuations, but only if investors believe earnings won’t deteriorate alongside employment. When job weakness hints at slower profits, that support weakens.

Currencies and commodities follow the rate story. A labor market that cools enough to invite cuts can soften the U.S. dollar. Commodity prices respond to both growth expectations and shifting interest rate differentials.

The Fed’s job isn’t to please markets. It’s to manage risk. Right now, 4.6% isn’t a crisis signal. It’s a pressure point.

And pressure points are where policy turns are born.

Indian Markets Find Their Footing as Trade Diplomacy Calms Investor Nerves

After a bruising stretch of losses, Indian equity markets staged a notable rebound this week, snapping a five-session losing streak as diplomatic signals from Washington eased fears of escalating trade tensions. The move offered a timely reminder of how closely emerging-market sentiment remains tethered to geopolitics — and how quickly capital flows can respond when uncertainty begins to lift.

The recovery was not driven by earnings surprises or domestic macro data. Instead, it was sparked by words: remarks from a U.S. envoy signaling continued engagement with India on trade issues and a willingness to keep negotiations open. For investors, that message was enough to halt the selling — at least for now.

A Market Under Pressure

The rebound followed one of the Indian market’s weakest weekly performances in months. Leading benchmarks had come under sustained pressure amid concerns that U.S.–India trade relations could deteriorate further, potentially reviving tariff risks and complicating supply-chain dynamics for export-linked sectors.

Foreign portfolio investors had already been trimming exposure, contributing to persistent outflows and amplifying downside momentum. Combined with global risk aversion tied to uncertainty around U.S. monetary policy and geopolitical friction elsewhere, Indian equities entered the week deeply oversold.

By the time markets opened on the rebound session, sentiment was fragile. Early trading saw sharp intraday swings, with benchmarks initially extending losses before reversing course decisively.

The Diplomatic Catalyst

What changed was the tone of the trade narrative. Public comments from a U.S. representative emphasized ongoing dialogue between Washington and New Delhi, including plans for follow-up discussions on trade matters. The remarks suggested that while negotiations remain complex, channels of communication are open — and that near-term escalation is not a base-case scenario.

For markets, the signal was clear: worst-case assumptions were likely overdone.

The response was swift. Major indices recovered sharply from intraday lows, with broad-based buying emerging across financials, metals, and industrial names. The rebound was reinforced by short covering, as traders who had positioned for continued downside rushed to unwind bets.

Why Trade Signals Matter So Much for India

India’s sensitivity to trade diplomacy reflects its position within global capital markets. As one of the largest emerging economies, India attracts substantial foreign investment — but those flows are highly responsive to shifts in perceived policy risk.

Trade uncertainty affects India on multiple levels:

  • Export competitiveness: Tariff threats can weigh on manufacturing, metals, and technology services.
  • Currency dynamics: Trade tensions often coincide with pressure on the rupee, complicating inflation and policy expectations.
  • Capital flows: Foreign investors tend to reduce exposure quickly when geopolitical risk rises, exacerbating volatility.

In that context, even incremental improvements in diplomatic tone can materially alter risk perception.

A Technical Rebound, Not a Trend Shift — Yet

While the bounce was meaningful, market participants remain cautious about interpreting it as the start of a sustained rally. Volatility indicators remain elevated, and trading desks describe the move as a combination of relief rally and technical correction rather than a wholesale change in fundamentals.

Key questions remain unresolved:

  • Will trade discussions translate into concrete policy outcomes?
  • Can foreign inflows stabilize after weeks of withdrawals?
  • How will global rate expectations and dollar strength influence emerging-market allocations?

Until those uncertainties clear, investors are likely to remain selective, favoring high-quality balance sheets and domestically driven growth stories over purely export-dependent plays.

Broader Implications for Emerging Markets

India’s experience this week offers a broader lesson for global investors: emerging markets remain acutely sensitive to geopolitics, even when domestic growth fundamentals are relatively strong.

In an environment where central-bank policy, trade alignment, and diplomatic signaling are increasingly intertwined, markets are reacting less to data releases and more to narrative shifts. For portfolio managers, this underscores the importance of monitoring political and diplomatic developments alongside traditional economic indicators.

The rebound in Indian equities highlights how quickly sentiment can turn when uncertainty recedes — even marginally. Diplomatic reassurance, not macro data, proved to be the catalyst that halted the selloff and restored a measure of confidence.

Whether that confidence endures will depend on what follows the rhetoric. For now, the episode reinforces a familiar market truth: in emerging markets, trade diplomacy is not just foreign policy — it is a market variable.

Disclaimer: This article is provided for informational and educational purposes only and does not constitute financial, investment, legal, or trading advice. Market conditions, economic data, and geopolitical developments can change rapidly and may affect the accuracy or relevance of the information presented. Readers should conduct their own research or consult with qualified financial professionals before making investment decisions. The views expressed are based on publicly available information at the time of writing and do not necessarily reflect future market outcomes.

Wholesale Price Trends Highlight Lingering Inflation Pressures Beneath the Surface

Even as consumer inflation shows signs of cooling, a less visible — but increasingly important — signal is flashing deeper in the economy, “wholesale prices are still rising.”

Recent data show increases in both headline and core wholesale inflation measures, a development that has caught the attention of economists and market strategists. Notably, the rise persisted even during periods of partial government shutdown, when economic activity typically slows. The takeaway is unsettling for policymakers and investors alike — inflationary pressure has not fully worked its way out of the system.

“This isn’t just a consumer price story anymore,” said a senior U.S. economist at a global investment firm. “When producer prices continue to climb, it tells you the cost structure of the economy is still adjusting upward.”

Why Wholesale Inflation Matters

Wholesale prices, often tracked through producer-level indicators, sit upstream from consumer prices. When costs rise at this stage — for raw materials, components, logistics, or energy — they eventually show up somewhere else, either through higher retail prices or compressed corporate margins.

“The producer level is where inflation pressure often hides before resurfacing,” said one macro strategist. “If those costs don’t ease, the idea of a clean disinflation becomes much harder to sustain.”

Economists note that wholesale inflation tends to act as a leading indicator, meaning today’s increases could translate into renewed consumer price pressure later in the year — especially if demand stabilizes or reaccelerates.

Shutdowns Didn’t Cool Prices — A Structural Signal

What stands out most in the recent data is when the increases occurred. Government shutdowns historically reduce spending, delay projects, and dampen demand — forces that usually cool prices.

This time, they didn’t.

“That’s a red flag,” said a former Federal Reserve adviser. “It suggests the inflation we’re seeing is structural, not cyclical. These are cost pressures tied to labor, financing, and supply chains — not just demand overheating.”

Among the drivers economists cite:

  • Persistently high labor costs, especially in skilled manufacturing and logistics
  • Higher borrowing costs, which feed into supplier pricing
  • Supply-chain restructuring, including reshoring and nearshoring efforts
  • Energy and transportation volatility, which remains elevated by historical standards

Together, these forces point to a higher baseline cost environment than the one that prevailed before the pandemic.

Corporate Margins Under Pressure

Wholesale Price Trends Highlight Lingering Inflation Pressures Beneath the Surface (2)

Photo Credit: Unsplash.com

For companies, persistent wholesale inflation creates a difficult balancing act. Many firms have already pushed through multiple rounds of price increases over the past two years. Consumers, however, are showing signs of resistance.

“The pricing power phase is fading,” said an equity analyst covering industrial and consumer sectors. “Now it’s about who can manage costs without sacrificing volume — and not everyone can.”

Manufacturers, retailers, and transportation-heavy businesses are particularly exposed. If input costs remain elevated while demand softens, margin compression becomes the next risk, a dynamic markets may not yet be fully pricing in.

Implications for the Federal Reserve

From a monetary policy perspective, wholesale inflation complicates the path forward.

Even if headline consumer inflation drifts closer to target, producer-level price pressure raises the risk of second-round effects, where companies resume passing costs along after a pause.

“This is why the Fed keeps stressing patience,” said a monetary policy analyst. “As long as upstream inflation isn’t convincingly cooling, cutting rates too quickly carries real risk.”

The data help explain why policymakers continue to emphasize a ‘higher for longer’ stance, despite growing market expectations for rate cuts later in the year.

What Investors Should Watch

For investors, the persistence of wholesale inflation reinforces several key themes:

  • Disinflation is uneven and fragile, not linear
  • Corporate earnings face renewed margin risk
  • Rate-cut optimism may need recalibration
  • Companies with pricing power and operational efficiency are better positioned

“This is the phase where inflation stops being dramatic but starts being dangerous,” one portfolio manager said. “It quietly eats into margins and complicates policy — and markets tend to underestimate that.”

The Bottom Line

Wholesale price trends suggest inflation isn’t roaring back — but it also isn’t finished retreating.

Instead, the economy appears to be settling into a higher-cost equilibrium, shaped by structural changes in labor, trade, capital, and supply chains. For markets, that means volatility around rates, earnings, and valuations is likely to persist.

As one economist put it: “Inflation hasn’t disappeared. It’s just moved upstream.”

TSMC’s Record Profit Sparks Chip Rally and Reignites AI Sector Optimism

When Taiwan Semiconductor Manufacturing Company (TSMC) delivered its latest quarterly earnings this week, the world’s largest contract chipmaker didn’t just beat expectations — it shattered them. The result: a powerful rally in semiconductor shares, renewed confidence in AI-linked equities, and a strategic reassessment of capital spending that reverberated across global markets.

A Breakthrough Quarter for the Heart of the Chip Industry

On January 15, TSMC reported a 35% year-over-year surge in fourth-quarter net profit, hitting NT$505.7 billion (about US $16 billion) — its highest quarterly profit on record and well above analyst forecasts. Revenue climbed more than 20%, driven by relentless demand for advanced semiconductors powering artificial intelligence, high-performance computing, and next-generation data centers.

“Thanks to strong signals from our customers and continued growth in AI and advanced compute applications, we are confident in our projections for 2026,” TSMC Chief Financial Officer Wendell Huang told investors on the earnings call, emphasizing optimism about sustained demand for leading-edge process technologies.

That confidence translated into guidance that stunned markets: TSMC now plans $52 billion to $56 billion in capital expenditures for 2026, a significant increase from prior forecasts and a clear indicator of long-term confidence in AI-driven silicon demand.

Wall Street’s Tech Complex Catches the Rally Fever

The earnings announcement didn’t just boost TSMC’s own shares — it sparked a broad rally in U.S. and global semiconductor stocks. U.S.-listed TSMC shares jumped sharply in pre-market trading, lifting related equities across the sector. ASML Holding, a key supplier of lithography equipment to TSMC, saw its market capitalization surpass $500 billion as investors priced in increased equipment demand tied to TSMC’s capex plans.

Investors took the results as a validation of the AI investment theme that has dominated technology markets in recent years. “TSMC’s performance confirms that the semiconductor cycle is expanding beyond expectations,” said Simon Coles, semiconductor analyst at Barclays, highlighting the company’s leadership in producing chips for key cloud and AI customers.

Other chipmakers — including Nvidia, AMD, and equipment suppliers such as KLA and Lam Research — also rallied on the news, reflecting confidence that the sector’s earnings momentum could extend beyond the headline names traditionally associated with AI.

Why TSMC’s Results Matter for Global Markets

TSMC’s outsized role in the semiconductor ecosystem means its performance is more than just a single company’s earnings story — it is a macro signal for global tech demand. As the primary manufacturing partner for Nvidia, Apple, Qualcomm, and numerous AI accelerator designers, TSMC’s fortunes are tightly linked to broader industry investment cycles.

The company’s advanced process technologies — from 3 nm to emerging 2 nm nodes — now comprise a substantial portion of its revenue mix, reflecting how critical cutting-edge chips have become across multiple AI deployment sectors.

Importantly for U.S. markets, TSMC is accelerating its footprint in the United States with massive investments in Arizona fab facilities. These expansions not only reflect firm confidence in domestic demand but also carry implications for U.S. industrial policy and supply-chain resilience under the CHIPS and Science Act.

Investors See a New Inflection Point

For market professionals, the TSMC results provide hard data to support what many had suspected: AI’s infrastructure build-out remains robust and is driving durable, cyclical growth in semiconductor capital spending.

“Investors are finally seeing palpable confirmation that AI demand isn’t just hype — it’s translating into real revenue and capex growth,” says Ben Barringer, head of technology research at Quilter Cheviot, noting that TSMC’s profit beat sets a positive tone for the broader earnings season.

The broader equity market responded in kind: major U.S. futures — including the S&P 500 and Nasdaq 100 E-Minis — climbed ahead of the trading session on promising economic data coupled with the tech-sector enthusiasm sparked by TSMC’s report.

From Silicon to Sentiment

Beyond the raw numbers, what matters most for investors is what TSMC’s performance signals. The combination of record profits, elevated guidance, and aggressive capex — driven primarily by AI chip demand — suggests a semiconductor cycle that may be stronger and longer lasting than many expected.

For professionals tracking allocation shifts, sector rotations, or macro momentum signals, TSMC’s earnings aren’t just about chips — they’re a bellwether for tomorrow’s risk assets.

As AI workloads proliferate across industries, TSMC’s results may well be the market’s first major confirmation that a new cycle isn’t coming — it’s here.


Disclaimer: This article is provided for informational and editorial purposes only and does not constitute investment advice, financial advice, or a recommendation to buy or sell any securities. Market data, company statements, and quotations are based on publicly available information believed to be reliable at the time of publication, but accuracy or completeness is not guaranteed. Views expressed by quoted individuals are their own and do not necessarily reflect the views of MarketDaily. Readers should conduct their own independent analysis or consult a qualified financial professional before making investment decisions.

IMF Sees Global Economy Holding Firm Despite Trade Shocks, Signaling Stability for Markets

As global markets navigate renewed trade tensions, supply-chain realignments, and geopolitical uncertainty, the International Monetary Fund is striking a cautiously optimistic tone. According to IMF Managing Director Kristalina Georgieva, the Fund’s upcoming global growth forecasts will show that the world economy remains more resilient than many investors fear, even as trade disruptions intensify.

Speaking on the sidelines of policy discussions ahead of the IMF’s January meetings, Georgieva said the institution’s latest projections indicate that growth has absorbed recent trade shocks without tipping into a broader slowdown. “We see that the global economy has shown resilience,” she said, adding that growth is expected to remain “fairly strong” despite mounting pressures on cross-border trade and investment flows.

Trade Frictions Without A Collapse

The IMF’s outlook comes at a moment when global trade dynamics are under strain. New tariff regimes, industrial policy shifts, and supply-chain reshoring efforts have raised concerns about whether trade fragmentation could undermine growth momentum in 2026. Yet IMF officials argue that diversification, policy adaptation, and post-pandemic adjustments have softened the blow.

“Trade shocks do have an impact,” Georgieva acknowledged, “but countries and companies have learned to adapt faster than in the past.”

For markets, this message matters. Trade-related shocks historically translate into earnings volatility, weaker capital expenditure, and currency stress in export-dependent economies. The IMF’s assessment suggests those effects are being contained — at least for now — reducing the risk of abrupt repricing across global equity and credit markets.

Central Bank Credibility As A Market Anchor

Beyond trade, Georgieva emphasized another theme closely watched by investors: central bank independence. In separate remarks, she underscored that credible monetary institutions remain essential to financial stability, explicitly backing the autonomy of major central banks such as the U.S. Federal Reserve.

“Central bank independence is critical,” Georgieva said, warning that political interference could undermine inflation control and destabilize expectations.

For bond and currency markets, this reassurance functions as a stabilizing signal. Expectations that the Fed and other central banks can operate without political pressure help anchor inflation forecasts, long-term yields, and risk premiums — especially as governments face growing fiscal demands.

Risks Still Tilt To The Downside

While the IMF’s tone is constructive, officials stopped short of declaring victory. Georgieva cautioned that downside risks remain elevated, citing geopolitical conflicts, climate-related disruptions, and uneven recovery paths across regions.

“We are not out of the woods,” she said, noting that policy missteps or an escalation in trade barriers could still derail growth trajectories.

This balanced framing reflects the IMF’s broader message to policymakers: resilience does not eliminate vulnerability. Structural reforms, fiscal discipline, and multilateral coordination remain critical to sustaining growth in an increasingly fragmented global economy.

What It Means For Investors

For market participants, the IMF’s outlook supports a base-case scenario of steady — if unspectacular — global expansion, rather than a sharp downturn driven by trade conflict. That backdrop favors selective risk-taking, particularly in sectors and regions that benefit from supply-chain diversification, technological investment, and domestic demand resilience.

At the same time, Georgieva’s warnings reinforce the importance of monitoring policy credibility and geopolitical flashpoints — variables that can quickly shift sentiment if confidence erodes.

The IMF’s full World Economic Outlook, scheduled for release next week, will provide updated growth numbers and country-level forecasts. Until then, the Fund’s message is clear: the global economy is bending under pressure, but it has not broken.


Disclaimer: This article is for informational and educational purposes only and does not constitute financial, investment, or economic advice. The views and statements cited reflect publicly available commentary from referenced sources at the time of publication and may change as new information emerges. Readers should not rely on this content as a basis for investment decisions and are encouraged to conduct their own research or consult qualified financial professionals before making any financial or economic decisions.

IMF Flags Risks if AI Growth Momentum Falters: A Fragile Pillar Beneath Global Expansion

The global economy, long buffeted by trade tensions, pandemic aftershocks, and geopolitical shifts, has shown unexpected resilience. In its latest World Economic Outlook update released this January, the International Monetary Fund (IMF) reaffirmed that global growth should rise to 3.3 % in 2026, buoyed in large part by surging investment in artificial intelligence (AI) and broader technology spending.

Yet beneath this seemingly robust picture lies a cautionary message: the global recovery may be too dependent on AI-related growth expectations, and if those expectations fail to materialize, the fallout could be substantial.

“There is a risk of a correction — a market correction — if expectations about productivity gains and profitability from AI fail to materialize,” said Pierre-Olivier Gourinchas, IMF chief economist.

AI Investment: Economic Backbone and Potential Weak Link

Historically, technological revolutions have reshaped economies. Today’s cycle is no different: businesses are pouring capital into data centers, AI chips, and digital infrastructure at unprecedented rates. In the United States, AI investment now comprises the highest share of economic capital formation since the early 2000s — a sign of confidence in future productivity.

For investors and policymakers, this trend reinforces bullish narratives. AI is expected to enhance automation, streamline operations, and unlock new revenue streams across industries — all of which support GDP growth projections like the IMF’s revised 2.4 % U.S. expansion for 2026.

But there’s a catch. The IMF points out that much of the current growth outlook hinges on assumptions about productivity gains from AI that are not yet proven at scale. That introduces a vulnerability unique to the current cycle: growth heavily tied to expected — not fully realized — returns.

Market Valuations Under Scrutiny

The IMF’s warning comes amid broader concern in global financial markets over inflated valuations in the technology sector. Many leading AI companies now account for a disproportionate share of equity market cap — levels that some analysts compare to the dot-com era.

If investors reassess the timing or magnitude of AI’s economic payoff, the resulting shift in sentiment could trigger broad market repricing. The IMF projects that a moderate correction in technology stock valuations combined with a slowdown in AI investment could shave about 0.4 percentage points off global GDP growth as early as 2026.

That prospect matters on multiple fronts:

  • Equity market risk: A correction could pull down major indices disproportionately weighted by tech giants.
  • Household wealth effects: Declines in equity valuations can reduce household net worth and consumer spending.
  • Capital flows: Reduced risk appetite could slow cross-border investment into emerging markets.

Beyond Wall Street: Macro Ripple Effects

The IMF stresses that the risks are not purely financial. If firms cut back on AI capital expenditure in response to disappointing productivity figures or tightening financing conditions, the cooling effect could slow broader demand. Lower business investment often feeds into lower hiring, weaker wage growth, and softer consumption — a chain reaction that can ripple across sectors.

In markets where technology adoption is central to competitive positioning — from manufacturing to services — such a slowdown could have wider strategic implications, particularly for economies like Germany, Japan, and even emerging markets doubling down on digital transformation.

Policy Implications: Managing the Downside

Gourinchas and other IMF officials emphasize that recognizing these risks is only the first step. They underscore the importance of robust monetary frameworks and financial stability oversight to guard against sudden shocks. In particular, the Fund highlighted the role of central bank independence as essential for navigating heightened uncertainty in a market environment dominated by speculative asset valuations.

In this respect, traditional macro tools may need recalibration. If AI-related optimism drives asset prices and credit growth beyond sustainable fundamentals, policymakers will face difficult choices: whether to lean against asset bubbles without derailing productive investment, or to accept higher valuations as part of structural transformation.

Ultimately, the IMF frames AI as both a powerful engine of growth and a potential structural fragility. In its more optimistic scenario, if productivity gains exceed expectations, AI could lift global growth by as much as 0.3 percentage points in 2026 and between 0.1 and 0.8 percentage points annually over the medium term — an attractive tailwind.

But that scenario depends critically on technology translating into measurable economic returns — a condition that remains uncertain.

As investors and policymakers digest the IMF’s latest forecasts and warnings, the message is clear: AI’s economic promise is immense, but the risks of overreliance are real and must be managed with sober analysis, not blind optimism.

The International Monetary Fund (IMF) Raises 2026 Global Growth Forecast as AI Investment Reshapes the Economic Outlook

The International Monetary Fund has upgraded its global growth outlook for 2026, pointing to accelerating investment in artificial intelligence as a stabilizing force for the world economy at a time when trade frictions and policy uncertainty continue to weigh on confidence. In its latest World Economic Outlook, the IMF now projects global GDP growth of 3.3% in 2026, up from 3.1% in its previous forecast, reflecting stronger-than-anticipated capital expenditure in AI-related infrastructure and technology.

The revision signals a shift in how the Fund is framing AI: not as a speculative tailwind, but as a measurable contributor to near-term macroeconomic performance.

AI Investment Moves From Sector Trend to Macro Driver

The upgrade is anchored primarily in advanced economies, with the United States at the center of the investment cycle. The IMF now expects U.S. growth to reach 2.4% in 2026, supported by sustained spending on data centers, high-performance computing, and semiconductor capacity tied directly to AI deployment. According to the Fund, the scale and persistence of this spending distinguish the current expansion from earlier technology cycles that failed to translate investment enthusiasm into broad productivity gains.

IMF economists noted that AI investment is increasingly visible in macroeconomic indicators rather than confined to corporate guidance or equity valuations. Productivity data in the U.S. and parts of Asia suggest firms are generating more output per worker even as labor markets cool, allowing growth to persist without reigniting inflation at the pace seen earlier in the post-pandemic recovery.

An IMF spokesperson said the revised outlook reflects “stronger-than-expected investment activity in technology sectors, especially those linked to artificial intelligence and digital infrastructure,” which has helped offset slower global trade growth and tighter financial conditions.

Valuation Risk Emerges as Expectations Rise

While the IMF’s forecast revision is constructive, the Fund paired its optimism with a clear warning about financial market expectations. IMF Chief Economist Pierre-Olivier Gourinchas cautioned that asset prices may be running ahead of realized productivity gains.

“There is a risk of a market correction if expectations about AI-driven productivity and profitability are not realized,” Gourinchas said, highlighting the growing sensitivity of growth forecasts to financial market sentiment.

The IMF estimates that a significant correction in technology asset valuations could reduce global growth by as much as 0.4 percentage points, primarily through tighter financial conditions and a pullback in capital investment. The risk is amplified by rising leverage among technology-focused firms and the concentration of capital flows into a relatively small group of companies driving much of the AI buildout.

Trade Policy and Supply Chains Remain Key Constraints

Beyond valuation concerns, the IMF highlighted trade policy uncertainty and geopolitical risk as ongoing constraints on the outlook. Although the forecast assumes some easing in tariff pressures compared with mid-2025 levels, officials cautioned that renewed trade tensions could quickly undermine business confidence and investment momentum.

This risk is particularly acute given the geographic concentration of AI-critical supply chains. Semiconductors, advanced manufacturing equipment, and energy infrastructure now play an outsized role in growth projections, meaning disruptions in these areas would ripple through industrial output, capital markets, and inflation dynamics.

The Fund emphasized that AI-driven growth is therefore not insulated from geopolitics, even if demand for digital infrastructure remains structurally strong.

Implications for Monetary Policy and Markets

For central banks, the IMF’s outlook presents a nuanced policy backdrop. Global inflation is expected to continue moderating, declining from approximately 4.1% in 2025 to 3.8% in 2026, which could provide additional flexibility for monetary authorities. However, AI-driven investment cycles may complicate traditional assessments of productivity, economic slack, and neutral interest rates, particularly if growth becomes increasingly concentrated in capital-intensive sectors.

For investors, the revised forecast reinforces a key shift in market thinking: AI is no longer framed as an optional upside scenario but as part of the baseline growth assumption. At the same time, the IMF’s cautionary tone underscores the fragility of growth narratives built on concentrated investment themes. Sustaining momentum will depend not only on continued capital spending, but on whether productivity gains diffuse broadly across firms, sectors, and labor markets.

As the IMF made clear, the durability of the current expansion hinges less on the speed of AI adoption than on the breadth of its economic impact — a distinction markets may be forced to confront as expectations meet realized outcomes.


Disclaimer: This article is for informational and educational purposes only and does not constitute investment advice, financial guidance, or a recommendation to buy or sell any securities or assets. The views referenced from third-party sources reflect their opinions at the time of publication and may change without notice. While the information presented is based on publicly available data and reputable sources believed to be reliable, accuracy and completeness are not guaranteed. Readers should conduct their own research and consult qualified financial or economic professionals before making any investment or policy decisions.


Institutional Sports Equipment Is Raising the Standard for Safety in Community Spaces

Community gyms and church activity rooms do much more than host pickup games. They’re classrooms on weekdays, youth centers on weeknights, and safe havens every weekend. With so much activity packed into the same four walls, safety has to be baked into the space’s design. And it begins with those same four walls.

Commercial wall padding is reshaping how schools, churches, and community centers protect the people who rely on and use their spaces most. And leading that evolution is Institutional Sports Equipment (ISE), a company turning high-traffic, multi-use rooms into safe environments designed for real-world use.

When One Room Does Everything, Safety Has to Do More

Across the country, churches and schools are being asked to stretch their spaces further than ever. A single room might host morning worship, an afternoon homeschool co-op, evening basketball practice, and a weekend community event. This flexibility is a gift to growing congregations and busy neighborhoods, but it also introduces new safety challenges that older facilities were never designed to handle.

Multipurpose rooms weren’t built with fast-paced athletics in mind, yet that’s exactly how they’re being used. When kids and teens play hard, walls become real hazards. The more varied the programming, the higher the need for impact absorption and predictable safety.

High-quality gym wall padding adapts spaces to recreation, education, worship, and community gatherings. And for churches and schools already working with limited staff and tight budgets, the right padding reduces liability concerns, minimizes injury risk, and expands how they can use their facilities.

Institutional Sports Equipment has spent decades helping organizations navigate these evolving needs. It evaluates room dimensions, intended uses, age groups, and code requirements to design solutions that align with each facility’s realities. For communities operating in states with strict fire-safety standards, ISE’s Class A fire-rated padding ensures compliance without sacrificing durability or design. And custom-configured padding systems allow a single room to serve dozens of functions safely, day after day.

ISE gives churches, schools, and community centers the confidence to say yes to more programs, more activities, and more opportunities for people to gather safely.

Inclusion Through Design in Special Needs and Safe Rooms

Whether it’s a therapeutic classroom, a calming space for children with autism, or a behavioral support room, special needs environments require thoughtful design that protects and supports the people who rely on them every day. Standard gym padding doesn’t always meet the unique demands of these spaces, which is why ISE thinks outside the box to provide specialized solutions for its clients.

Specialized commercial wall padding designed specifically for special-needs and sensory-sensitive environments is thicker and softer to minimize injury and reduce sensory overload. Custom colors and strategic placement avoid visual clutter so the padding becomes part of the therapeutic environment rather than an afterthought. These materials provide a layer of comfort and safety, allowing students to engage confidently.

The same level of care extends to safe rooms as well. ISE’s commercial wall padding for safe rooms and de-escalation spaces is built with higher-density foam, tamper-resistant fixtures, and seamless edges to withstand repeated, high-impact use. These rooms are designed to help individuals regain control and feel secure, so every detail, from the padding thickness to the mounting system, matters.

Because these environments serve vulnerable populations, architects, administrators, and facility planners should bring ISE into the process early. Its expertise helps shape not just the room’s physical safety but also the emotional experience it delivers. In spaces where people go to heal, calm down, or simply feel safe, that combination of thoughtful design and technical precision makes all the difference.

Made to Last and Look Good Doing It

Even though safety is the goal, aesthetics matter. Unlike industrial-looking gym setups, ISE can tailor standard wall padding for church activity centers with custom colors, scripture verses, school mascots, or logos. This customization enhances identity and makes the space feel warm, welcoming, and intentional.

In church settings, custom graphics can help reinforce community values. For instance, an activity center may include padding in calming neutral tones to maintain the sacred tone of the space, or it might include scripture-integrated graphics to remind kids of core messages while they play.

All ISE pads are manufactured in the United States using top-grade materials and high-density polyurethane foam. They’re designed to withstand years of high-impact use without degrading in appearance or performance, so they support both your mission and your maintenance budget.

Commercial Wall Padding as a Strategic Investment

Many facility managers think of wall padding as a finishing touch, something to add once the bleachers, flooring, and lighting are in place. But the most forward-thinking institutions are treating wall padding as an upfront part of their strategic investment in safety and usability.

For example, incorporating padding early in the design process helps ensure that outlets, signage, HVAC units, and lighting don’t interfere with player safety or padding placement. It also allows for a more holistic visual design that feels clean and cohesive rather than piecemeal.

ISE works directly with builders, architects, and church leaders to measure, recommend, and deliver the most appropriate wall padding setup for any environment. Every solution, from full-height gymnasium coverage to corner pads and column wraps, is engineered to integrate seamlessly into the facility’s mission.

Partnering with Purpose

At its core, Institutional Sports Equipment helps organizations create safer, more usable spaces. That mission begins with understanding what a community is trying to achieve, whether that’s keeping kids safe during mid-week youth programs, creating a multi-use gym that can handle everything from basketball to banquets, or building a sensory-friendly space where students can regulate and recharge.

What sets ISE apart is the way they approach these conversations. They don’t just ask about dimensions and materials. They ask who will use the space, how it will function on busy days, and what long-term challenges the organization aims to address. That kind of collaboration matters in churches and schools that juggle limited budgets and growing expectations from the families and communities they serve.

This purpose-driven partnership is why organizations rely on ISE as a guide. They help fill the knowledge gaps that most facility managers don’t have time to navigate on their own. By blending safety expertise with practical, real-world insight, ISE helps clients create safe, welcoming spaces custom-designed for the people who use them.

Having a commercial wall padding supplier who balances protection, durability, and daily function is the foundation for spaces that serve communities well.

Looking Ahead

As demand grows for commercial wall padding that supports more than athletics, Institutional Sports Equipment is poised to lead the next chapter in facility design. Their work embodies a belief that environments shape behavior, safety builds confidence, and every wall can play a role in how people experience space. And that offers peace of mind.

To learn more about how Institutional Sports Equipment can support schools, churches, or community centers with safety-forward, code-compliant wall padding solutions, visit: https://InstitutionalSportsEquipment.com