Market Daily

S&P 500 Opens May at a New All-Time High — April Closes as Wall Street’s Best Month in Five Years

Apple delivered. Oil pulled back. The index hit a record. But the data underneath the rally is sending signals that deserve more attention than the ticker.

Wall Street closed out April with its strongest monthly performance in five years and opened May the same way — with the S&P 500 pushing to a fresh all-time high on Friday, May 1, as Apple’s record quarterly earnings and a pullback in oil prices combined to extend a rally that has been building since early April.

The S&P 500 gained 10.4% in April — its best month since November 2020. The Nasdaq Composite rose 15.3%, its best month since April 2020. The Dow Jones Industrial Average also gained. Ten of eleven S&P sectors closed Thursday in positive territory. The only sector that did not participate was technology, which slipped modestly after leading the prior session’s gains — a rotation rather than a reversal.

Friday’s session extended those gains. The catalyst was Apple, which reported quarterly revenue of $111.2 billion on April 30 — a March quarter record — alongside a $100 billion share buyback authorization and guidance for continued double-digit revenue growth in the current quarter. Apple stock jumped approximately 3% in extended trading and carried that momentum into Friday’s open, providing meaningful index-level lift given the company’s weight in both the S&P 500 and the Nasdaq.

Oil’s retreat added to the optimism. Brent crude and West Texas Intermediate both pulled back from recent highs on reports that Iran had shared a new proposal through Pakistani interlocutors to reopen the Strait of Hormuz, the waterway that has been effectively closed since early March. The proposal — which would defer nuclear negotiations while ending hostilities — has not received a public U.S. response, but the mere signal of diplomatic movement was enough to ease energy market pressure and give equity investors room to extend the April momentum into the new month.

What Drove April’s Gains

The April rally did not emerge from a single catalyst. It was built across several weeks of overlapping positive developments, each reinforcing the next.

Big Tech earnings season provided the most durable foundation. Alphabet reported Q1 2026 revenue of $109.9 billion, up 22% year over year, with Google Cloud growing 63% to $20.03 billion — outpacing both Microsoft Azure and Amazon AWS in their most recent reported quarters. Net income jumped 81%. Alphabet shares surged approximately 10% on April 30. Microsoft, Amazon, and Meta also reported strong cloud and AI-related revenue growth, validating the thesis that AI capital expenditure is beginning to produce measurable near-term returns at the enterprise level.

That validation matters for markets because it addresses the most persistent concern hanging over the AI trade heading into 2026: whether the combined hyperscaler capex now tracking toward approximately $700 billion for the year — with Alphabet alone guiding $180 to $190 billion — would translate into revenue before the spending itself became a drag on margins. The Q1 earnings season provided the most affirmative answer yet. Charles Schwab’s market commentary this week noted that “markets are rewarding AI spending that shows near-term monetization and punishing spending without clear incremental returns,” and flagged that sharper demands for AI return-on-investment disclosure should be expected next quarter.

Oil price volatility also worked in equities’ favor during April. Each diplomatic signal suggesting progress on the Iran conflict — however tentative — produced crude price pullbacks that relieved inflationary pressure and lifted market sentiment. The national average gasoline price remains at $4.30 per gallon, a four-year high, and California has crossed $6.01 per gallon, but any directional move lower is a positive signal for consumer spending expectations and corporate margin outlooks.

What the Data Says This Morning

Friday’s ISM Manufacturing PMI report introduced a note of complexity into the record-high open. The April composite printed 52.7 — matching March’s reading exactly, and the highest level since August 2022. New Orders expanded for the fourth consecutive month, registering 54.1. On those metrics, manufacturing looks healthy.

The Prices Paid sub-index tells a different story. It surged 6.3 percentage points in April to 84.6 — the highest reading since April 2022 and reflecting manufacturing cost pressures driven by energy prices, tariff pass-through costs, and supply chain disruptions. The Employment sub-index remained in contraction. S&P Global’s Chris Williamson, commenting on the parallel S&P Global Manufacturing PMI reading of 54.5, warned that a significant portion of April’s demand surge reflects pre-emptive stockpiling ahead of anticipated further price increases — a pattern that produces short-term PMI strength that can fade quickly.

The combination of an expanding headline PMI, accelerating input costs, and contracting employment is the configuration that precedes stagflation readings. For the Federal Reserve, which just concluded Jerome Powell’s final meeting as chair and is preparing to hand the institution to Kevin Warsh before the May meeting, the ISM data is not a clean signal.

Treasury yields rose alongside equities on Thursday — a detail that received less attention than the record close but carries meaning for fixed income watchers. When yields and equities rise together, it often reflects genuine economic confidence rather than a flight to risk assets. But it can also reflect markets pricing in the prospect that rate cuts are not coming as soon as previously hoped — which is exactly what the Prices Paid data, and the Fed’s own April statement, suggest.

The Calendar Ahead

The record-high open is the market’s current answer to a question that will be tested repeatedly over the next two weeks.

Next week brings a sequence of economic releases and earnings that will either confirm the April narrative or begin to complicate it. The April Nonfarm Payrolls report arrives May 8 — the most watched single data point in any given month, and one that will be read in the context of the ISM’s contracting employment sub-index. JOLTS March job openings print May 5. The ISM Services PMI for April arrives May 6, completing the picture of where the broader economy stood as Q2 began.

On the earnings calendar, Palantir, Advanced Micro Devices, and Arm Holdings report next week. Each is a direct read on different dimensions of the AI infrastructure trade: Palantir on enterprise AI software adoption and government spending, AMD on the chip competitive dynamics with Nvidia, and Arm on the semiconductor IP layer underpinning virtually every AI chip architecture. Their results will extend the monetization accounting that Alphabet and Apple started this week.

The market enters May from a position of strength that is, by any historical measure, notable. A 10.4% S&P 500 gain in a single month, achieved during an active Middle East conflict with a national average gasoline price above $4.30, against a backdrop of Federal Reserve leadership transition and four-way FOMC dissent, is not a fragile rally built on sentiment alone. It reflects genuine earnings growth, genuine AI revenue validation, and a degree of resilience in the U.S. consumer and corporate sector that has consistently surprised economists to the upside.

Whether May sustains that momentum depends on whether the signals embedded in this morning’s ISM data — surging input costs, employment contraction, and a demand boost that may partly reflect inventory pre-positioning rather than genuine end-use growth — remain contained, or whether they begin to compound into the kind of reading that forces a reassessment.

The all-time high is real. So is the Prices Paid index at 84.6.

Both numbers belong in the same paragraph.


Disclaimer: This article is based on publicly available market data from Charles Schwab’s Market Update, the ISM Manufacturing PMI official press release for April 2026, and CNBC. Index performance figures reflect reported closing data. This article does not constitute investment advice or a recommendation to buy or sell any security. Market conditions described reflect data available as of May 1, 2026, and are subject to change. Readers making investment decisions should consult a licensed financial advisor.

S&P 500 Closes Above 7,200 for the First Time as April Logs Its Strongest Month Since 2020

Wall Street capped a historic month on Thursday with record closes across all three major indexes, driven by standout earnings from Alphabet and Caterpillar and easing fears over the Iran conflict.

Thursday, April 30, 2026 will be remembered as the day Wall Street crossed a threshold it had never reached before. The S&P 500 closed above 7,200 for the first time in its history, capping a month that has now entered the record books as the strongest performance for the index since November 2020. For investors who held through the volatility of the past several weeks — energy price shocks, geopolitical uncertainty, and a mixed bag of corporate earnings — Thursday delivered the kind of session that makes the patience feel worth it.

The S&P 500 rose 1.02% to close at 7,209.01, its first close above the 7,200 threshold. The tech-heavy Nasdaq jumped 0.89% to 24,892.31, hitting new intraday and closing records as well. The blue-chip Dow Jones Industrial Average added 790.33 points, or 1.62%, to settle at 49,652.14.

The rally was broad-based and sustained throughout the session, gaining momentum as the afternoon wore on. By the closing bell, all three major indexes were deep in positive territory, with the Dow’s nearly 800-point advance providing the most visceral illustration of the day’s sentiment.

Alphabet and Caterpillar Lead the Charge

The session’s gains were anchored by two earnings reports that landed with significant force in opposite corners of the market — one a technology giant, the other an industrial bellwether.

Alphabet beat estimates with Q1 earnings per share of $5.11 versus $2.63 expected, with Google Cloud revenue up 63% and its backlog nearly doubling to $460 billion. The results were not merely a beat — they were a statement. Google Cloud’s backlog figure, in particular, signaled that demand for AI infrastructure is not slowing, and that Alphabet has secured commitments from enterprise clients that will sustain its revenue trajectory well into the future. Shares of Alphabet gained 10% on the session, providing a meaningful lift to both the S&P 500 and the Nasdaq.

Caterpillar shares popped nearly 10% on Thursday after the company reported better-than-expected quarterly figures, boosting the Dow. The industrial name, which is viewed as a bellwether for the global economy, also raised its annual revenue outlook. Caterpillar’s results carry an interpretive weight that goes beyond the company itself. When the world’s largest manufacturer of construction and mining equipment raises its outlook, it is typically read as a signal that global infrastructure investment remains on solid footing — a meaningful data point at a moment when geopolitical tensions have raised questions about the durability of economic activity.

The construction equipment manufacturer reported adjusted earnings of $5.54 per share and $17.42 billion in revenue, compared to the consensus estimate of $4.65 per share and $16.53 billion in revenue. “Our team delivered a strong start to the year, driven by resilient end markets and disciplined execution in a dynamic operating environment,” said Chair and CEO Joe Creed.

The Other Side of the Ledger

Not every megacap closed Thursday in positive territory. The day’s earnings landscape produced clear winners and clear losers, and the divergence offered a window into what investors are currently rewarding and what they are questioning.

Meta and Microsoft lost 8.6% and 3.9%, respectively. Meta shares were weighed down by the company’s latest capital expenditure guidance, while user growth disappointed. Microsoft faced similar pressure after the company said spending will reach $190 billion due to high memory costs.

The selloffs in Meta and Microsoft were not driven by weak revenue — both companies reported figures that would have been considered strong in most prior earnings cycles. The market’s concern centers on a different question: whether the scale of AI-related capital spending being committed by these companies will eventually translate into proportional returns. While it is a positive from a GDP perspective that hyperscalers are spending heavily on physical infrastructure, concerns remain about the companies’ valuations at current spending levels, according to Tom Graff, chief investment officer at Facet.

The divergence between Alphabet’s reception — where AI investment appeared to be yielding visible results in cloud revenue — and Meta and Microsoft’s punishments illustrated a market that is becoming more discriminating about AI spending stories rather than rewarding all of them equally.

April in the Books

Zooming out from Thursday’s session, the month of April 2026 stands as a remarkable period for American equity markets by any historical measure.

The S&P 500 gained 10.4% in April for its best month since November 2020. The Nasdaq rose 15.3%, its best month since April 2020. The Dow ended April with a 7.1% advance — its strongest monthly performance since November 2024.

Those figures arrived against a backdrop that gave investors plenty of reasons for caution. The ongoing conflict involving Iran has kept energy prices elevated, with gasoline costs hitting multi-year highs in parts of the country. The Federal Reserve held interest rates steady at its most recent meeting, offering no near-term relief on borrowing costs. And the early weeks of April brought genuine turbulence, as markets processed the implications of a prolonged geopolitical standoff and its effect on oil supply.

That the month ends with record closes across all three major indexes is a testament to the resilience of corporate earnings and the continued appetite among investors for exposure to AI-driven growth — even as the precise shape of those returns remains a subject of active debate.

GDP Data Adds Context

Thursday’s market session also absorbed the morning release of the first-quarter GDP report from the Bureau of Economic Analysis, which added a layer of economic context to the day’s trading.

Real gross domestic product increased at an annual rate of 2.0% in the first quarter of 2026, according to the advance estimate, up from 0.5% in the fourth quarter of 2025. The contributors to the increase included investment, exports, consumer spending, and government spending.

The 2.0% figure came in slightly below the 2.2% consensus forecast, which in a different market environment might have weighed on sentiment. On Thursday, with strong earnings already providing a tailwind, it was absorbed without disruption. Markets appeared to read the GDP number as confirmation that the economy remains on solid ground — not spectacular, but durable.

“This is still an AI-driven economy,” said Olu Sonola, head of U.S. economics at Fitch Ratings. “The longer the conflict with Iran drags on, the greater the risk that higher energy prices continue to push inflation up and ultimately dampen growth.”

That caveat hangs over the record close. Wall Street ended April on a historic high note. Whether May can sustain it will depend in large part on factors that no earnings report can fully insulate against — energy prices, the path of interest rates, and the resolution or escalation of the geopolitical pressures that have defined the first third of 2026.

For now, the number on the board is 7,209.01 — and it has never been higher.

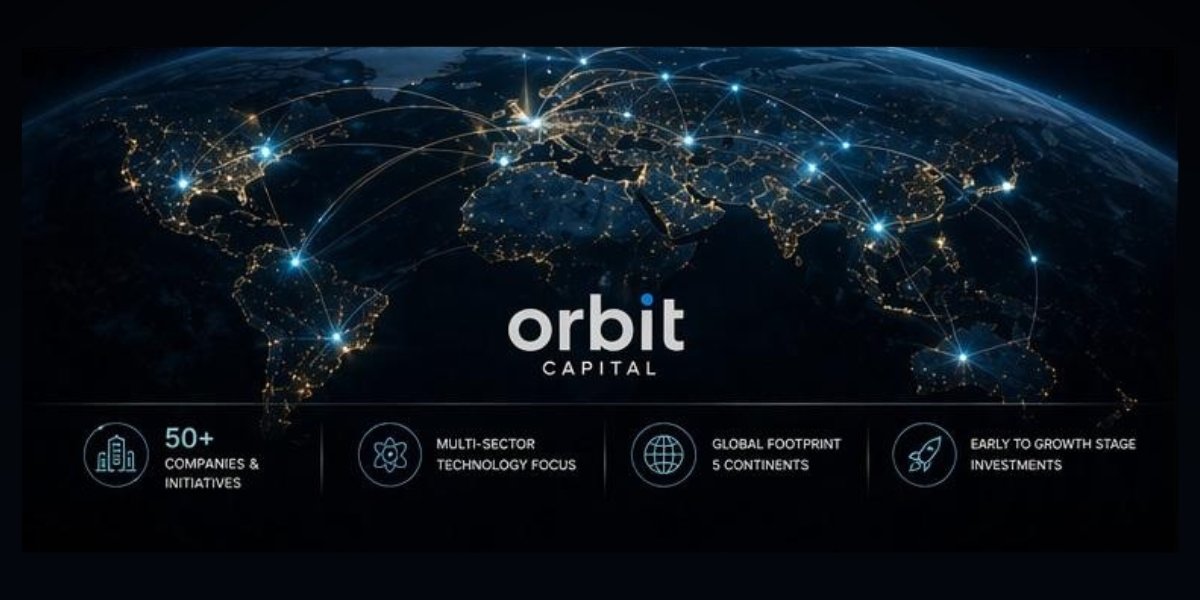
Orbit Capital and Its Expanding Portfolio of Technology Ventures and Advisory Engagements Across Global Markets

Investment firms have increasingly assumed a more expansive role within the startup industry in recent years. These firms are offering operational guidance, regulatory insights, and access to networks to support the growth of startup companies, particularly those operating in complex, cross-jurisdictional environments. As technology sectors continue to evolve, investment firms are playing a crucial role in helping companies navigate the intricacies of global market conditions. This trend has been especially prominent among investment firms that have established long-term relationships with companies in their portfolios.

Orbit Capital, an investment firm founded in 2018 by Jason Butcher, is one such example of this evolving trend. Operating from George Town, Cayman Islands, Orbit Capital has been active in providing both investment capital and advisory services to companies, particularly those within the technology sector. By early 2026, the firm had become involved with a diverse range of 50 companies and initiatives. Orbit Capital’s focus has primarily been on technology-driven investments, including sectors such as financial technology, artificial intelligence (AI), and infrastructure systems.

The firm’s portfolio comprises companies at various stages of development, with some focusing on early-stage fundraising and others on more established markets. Among the companies in Orbit Capital’s network is Boardy.ai, a platform that connects founders and investors in early-stage fundraising environments. Boardy.ai has facilitated interactions between thousands of founders and investors, offering valuable insights into emerging trends in startup financing networks. Another example is Soar.com, a company that develops and deploys AI and machine learning models to simplify complex technical processes.

In addition to its focus on AI and machine learning, Orbit Capital has engaged with companies in the financial infrastructure sector. Payall, a company within the firm’s portfolio, develops systems for near-instant cross-border payments for financial institutions. As demand for more accessible and faster payment solutions grows, financial technology remains a focal point for investment, with firms like Orbit Capital supporting the evolution of traditional banking and transaction systems.

Artificial intelligence plays an integral role in many of Orbit Capital’s investments. Companies like Figure.ai and others involved in data analysis and automation are indicative of how AI technologies are becoming increasingly embedded in business operations across diverse industries. Orbit Capital’s investments in AI-related firms reflect its commitment to recognizing and supporting market trends focused on technological innovation.

Orbit Capital typically adopts a strategy of making small investments, which allows the firm to retain a level of control while benefiting from external expertise. These investments are accompanied by advisory services, which address both the business and operational needs of portfolio companies. This includes assistance with navigating regulatory environments, which can differ significantly across countries. Given the global nature of many of its investments, Orbit Capital’s advisory services are tailored to help companies comply with various international regulations.

Strategic alignment is another area where Orbit Capital adds value to its portfolio companies. The firm provides input on market positioning, partnerships, and long-term growth strategies, which are essential for companies aiming for sustainable growth. By focusing on these areas, Orbit Capital helps ensure that its portfolio companies are well-positioned for long-term success, without compromising their regulatory or operational frameworks.

Sustainable growth has emerged as a key consideration within the startup environment, particularly for companies operating in the technology and financial sectors. Orbit Capital’s advisory services take into account the need to balance growth and sustainability, especially in industries where regulatory, environmental, and social pressures are increasing. By considering these factors, Orbit Capital aims to help its portfolio companies align with industry standards and create a framework for long-term, responsible growth.

Orbit Capital’s portfolio spans a global network of companies, with operations in North America, Europe, Asia, the Caribbean, and Latin America. This geographic diversity underscores the borderless nature of technology development and highlights the international scope of Orbit Capital’s engagement with its portfolio companies.

The firm’s model of combining investments with advisory services aligns with broader trends in the venture capital industry, where investors are increasingly viewed not just as sources of capital but as partners that help companies navigate regulatory environments, implement governance practices, and build long-term strategies. Orbit Capital’s approach of ongoing relationships with portfolio companies, rather than one-time investments, reflects a shift in how venture capital firms engage with the startups they support.

Orbit Capital’s involvement in 50 companies by early 2026 reflects its commitment to a diversified investment approach. Although the firm’s investments are varied, it remains focused on technology-driven ventures that align with its core strategy of supporting innovation across sectors such as finance, AI, and infrastructure.

As a global investment and advisory firm, Orbit Capital is well-positioned to continue contributing to the growth and development of technology-focused startups across international markets. By combining financial support with strategic advisory services, the firm plays an important role in shaping the future of the technology industry.

Three Central Banks, One Week, One Shared Problem: Inflation That Won’t Cooperate

The most consequential week in global monetary policy this year opened Tuesday with a warning from Tokyo. By Wednesday evening, Washington will have weighed in. By Thursday, Frankfurt follows. Three of the world’s most systemically significant central banks are delivering policy decisions within 72 hours of each other — and all three are navigating the same impossible trade-off between growth that is slowing and inflation that refuses to.

The Bank of Japan fired first. The message it sent deserves more attention than markets gave it.

Tokyo Sets the Tone

Japan’s central bank kept its policy rate steady at 0.75% on Tuesday in a split 6-3 vote, while revising its inflation estimates sharply upward as the Iran war raises supply-side risks.

The rate hold was expected. What was not fully priced in was the scale of the forecast revisions accompanying it. The Bank of Japan cut its growth forecast for fiscal year 2026 to 0.5% from 1%, and sharply raised its core inflation outlook to 2.8% from 1.9%. That is not a minor adjustment. It is a 47-basis-point upward revision to inflation and a 50-basis-point downward revision to growth — simultaneously — in a single policy cycle.

The BOJ warned that Japan’s economic growth was likely to decelerate since corporate profits and households’ real income are expected to be pushed down by factors such as a deterioration in the terms of trade reflecting the rise in crude oil prices.

Japan’s position is structurally more exposed than most developed economies to energy price shocks. The country imports the vast majority of its crude from the Middle East, and with the Strait of Hormuz effectively closed since the escalation of the Iran conflict in late February, the cost of that dependency is compounding in real time.

Shigeto Nagai, head of Japan economics at Oxford Economics, described the situation as “a very light stagflation-like situation” — real disposable incomes in negative territory, growth stagnant, inflation running above target.

The Dissent That Markets Should Not Ignore

The headline vote of 6-3 deserves closer examination than a simple hold verdict suggests. Three of the BOJ’s nine board members voted against keeping the policy rate at 0.75%, marking the most significant internal dissent since the introduction of negative rates in 2016. Analysts said the division signals growing pressure within the central bank over the timing of further rate hikes.

The dissenters argued that the Middle East conflict had skewed price risks decisively to the upside — and that waiting risked allowing inflation expectations to become entrenched above target. That is not a fringe view. It is the view of one-third of the board.

Masahiko Loo, Senior Fixed Income Strategist at State Street Investment Management, said the BOJ’s decision “should be seen as much about currency defence as inflation control, signalling growing intolerance for further yen weakness as domestic inflation and growth prove resilient.” The yen has weakened over 1.5% year-to-date, currently trading around 159 against the dollar — adding to Japan’s import cost burden and creating a feedback loop between currency weakness and inflation.

Washington Next: Powell’s Final Act

The Federal Reserve concludes its two-day FOMC meeting Wednesday, delivering what is widely expected to be Jerome Powell’s final policy decision as chair before his term expires May 15. A hold is not in question — markets have priced the probability of no change at 100%.

What matters is the language. With crude oil near $100 a barrel, gasoline averaging $4.18 nationally, and the Fed’s preferred core inflation gauge running at 3% — a full 100 basis points above target — the committee faces the same dilemma as the BOJ: cutting risks re-accelerating inflation, but signaling an extended hold risks choking a labor market already showing signs of cooling.

The Fed’s dual mandate creates an additional layer of complexity that the BOJ does not face in the same form. Energy price shocks filter through to headline CPI quickly but core more slowly — giving policymakers justification to look through them as “transitory.” Whether Powell uses his final press conference to reinforce that framing, or to acknowledge that the Iran conflict’s inflationary effects are proving stickier than anticipated, will set the tone for how markets interpret the handoff to incoming chair Kevin Warsh.

Frankfurt Closes the Week

The European Central Bank meets Thursday, also expected to hold. The ECB’s challenge mirrors its peers — energy price transmission through the eurozone is significant, particularly for manufacturing-heavy economies like Germany, and the stagflationary pressure is, if anything, more acute given Europe’s structural energy dependence.

The Stoxx 600 moved into positive territory Tuesday on the back of strong European corporate earnings, with oil and gas names leading on a 1.8% rise and bank stocks advancing more than 1%. But the resilience of equity markets should not obscure the fixed income signal: long-duration government bonds have been a poor hedge throughout this cycle.

The Bond Market’s Broken Assumption

BlackRock’s Investment Institute, in its April 27 weekly commentary, said it stays underweight long-term government bonds, noting they “struggled to offset equity declines throughout the Iran war” — pointing to what it calls the “diversification mirage” as a structural feature of the post-pandemic environment, driven by rising term premiums on concerns over high debt loads.

That is a significant institutional statement. The traditional 60/40 portfolio logic — equities for growth, bonds for stability — has been structurally undermined by an environment in which inflation shocks drive equities and bonds lower simultaneously. The term premium, the extra compensation investors demand for holding duration, is rising across major markets as debt-to-GDP ratios climb and central banks face limits on how aggressively they can suppress long yields without reigniting inflation.

For fixed income portfolio managers, the week’s three central bank meetings are less about the rate decisions themselves — all holds — and more about whether any of the three signals a shift in how long the hold will last. A hawkish pivot in tone from the Fed, combined with the BOJ’s internal dissent and the ECB’s energy-inflation exposure, would harden the case for staying short duration into the second half of 2026.

The stagflation warning from Tokyo is the first data point. Washington and Frankfurt deliver the next two by Thursday. Investors have 72 hours to calibrate accordingly.

Ron Nash and His Role in Venture Capital Investment with InterWest Partners

Venture capital has historically been a key driver of the technology industry’s direction, especially in the United States, where investment firms have financed numerous firms that eventually became market leaders. Beyond providing capital, venture investors have offered strategic technology and business advice that helped shape the emergence of software, security, and infrastructure companies now dominating international markets. The investment climate for early-stage companies, particularly from the 1990s through the 2010s, was characterized by investors’ readiness to take calculated risks in emerging areas like semiconductors, cybersecurity, and cloud-based business solutions. In this environment, people with rich expertise in global business management and technology leadership became critical players in driving portfolio company success.

Ron Nash joined venture capital after a corporate career that included executive leadership roles at large technology organizations and global expansion. After this experience, he joined InterWest Partners, a Silicon Valley-based venture capital firm, as an Executive-in-Residence and later as a Partner in the early 2000s. InterWest Partners, established in 1979, had already established a profile for investing in technology and healthcare ventures, having backed more than 300 companies. When Nash came on board, the firm was concentrating on backing early-stage businesses well-poised for growth in high-demand markets, and it raised three additional venture capital funds during his tenure.

At InterWest Partners, Nash concentrated on seed and early-stage investments in technology companies, especially those focused on cybersecurity, software-as-a-service, grid management, and enterprise software solutions. In his role, he could offer direct advice to founders while assisting the fund in finding investment opportunities in companies with growth potential. This role brought together his corporate executive expertise with the analytical abilities required to weigh risks and capitalize on opportunities in venture-capital-backed start-up firms.

A number of InterWest portfolio companies in Nash’s portfolio represent the kind of innovation that InterWest aimed to fund. Damballa, founded in 2006 in Atlanta, was a cybersecurity firm that specialized in detecting advanced threats and botnets that even traditional antivirus software could not identify or block. The technology at Damballa garnered considerable industry interest as cyberattacks grew more complex, creating heightened demand for products capable of responding to zero-day vulnerabilities. Nash’s commitment was consistent with InterWest’s focus on investing in firms that had the potential to address fundamental gaps in the enterprise information technology ecosystem.

Another investment opportunity was Lombardi Software, a vendor of business process management software. Lombardi, located in Austin, Texas, built its reputation as a BPM software company before IBM acquired it in 2010. The acquisition allowed IBM to enhance its portfolio of process automation and workflow offerings, an industry that had expanded significantly in the 2000s as businesses sought to improve productivity and compliance. Nash’s role in helping guide Lombardi from growth stage to acquisition reflected the broader venture capital objective of preparing start-ups for integration into larger corporate structures.

Vendavo, where Nash was an investor and board director, was an expert at pricing optimization and profitability solutions for enterprises. Established towards the end of the 1990s, Vendavo’s software became increasingly relevant as enterprises sought data-driven solutions to determine pricing strategies in highly competitive industries with thousands of SKUs. Vendavo’s ability to win business from many larger enterprises reflected Nash’s investment vision, which extended beyond typical infrastructure to include analytics-driven SaaS solutions.

ExoLink, a venture focused on grid management and power-related technologies, also demonstrated Nash’s portfolio diversification. As energy infrastructure and power grid upgrading emerged as national priorities during this period, venture capital investment in grid management solutions testified to increasing points of intersection between technology and public utilities. Backing early-stage ventures in this arena positioned InterWest and its management at the forefront of innovation in key infrastructure.

The method that Nash applied to his job integrated operational management with investment planning. As a former executive with large companies, he gained an understanding of what it took to grow small start-ups into segment-leading acquisition candidates. With InterWest, it meant building leadership teams, perfecting business models, and readying companies for the high-performance requirements of enterprise customers and ultimate integration into larger business entities.

InterWest’s overall plan during Nash’s tenure reflected the changes happening within the venture capital field. Venture capital investment in the United States more than doubled from 2000 to 2015, reaching over $58 billion in 2015, up from $28 billion in 2003, according to the National Venture Capital Association. Most of this expansion was focused on technology firms, where aggressive bets on enterprise software, cybersecurity, and cloud services paid off through acquisitions and initial public offerings. Nash’s work at InterWest fit into this general trend, where institutional investment in emerging but focused markets was ultimately returned primarily through mergers and acquisitions.

Portfolio company acquisitions, such as IBM’s 2010 purchase of Lombardi Software, or the ultimate growth paths to acquisitions of Vendavo and Damballa, are all part of InterWest’s broader legacy as a venture capital firm that successfully amplified early-stage firms and capitalized on their potential with breakthrough technology. Nash’s reputation as a leader who could thrive in both corporate and entrepreneurial settings was bolstered by his talent for recognizing nascent technologies and collaborating with the firms’ founders.

By integrating his prior corporate background with the fluid, high-risk nature of venture capital, Nash added a new dimension to his career in the technology industry. His experience at InterWest Partners embodied the value of cross-disciplinary collaboration in the success of venture-backed firms. It also showed how individual investors and management could influence the fortunes of companies that do business in key spaces of cybersecurity, energy, hyperconverged infrastructure, and enterprise technology.

Ron Nash’s work with InterWest Partners was a career phase in which his experience was channeled toward cultivating and advancing innovation in its earliest stages, aiding companies that would eventually become major players in the market. His role at the venture capital fund spans the gap between executive management at established companies and the entrepreneurial spirit of start-ups, making him someone who works on both sides of the technology ecosystem to optimize business results.

Disclaimer: This article is for informational purposes only and does not constitute investment advice, a recommendation, or an offer to buy or sell any securities. Consult a qualified financial advisor for advice specific to your situation.

S&P 500 Hits Fresh Record at NYSE Despite Stalled Iran Talks

The S&P 500 climbed to a fresh all-time intraday high on Monday, April 27, 2026, even as stalled U.S.–Iran peace negotiations and a continued closure of the Strait of Hormuz pushed oil prices higher and capped what could have been a stronger session at the New York Stock Exchange. The broad market index traded up roughly 0.1% before settling at a new record close, while the Nasdaq Composite added about 0.2% and notched its own intraday peak. The Dow Jones Industrial Average lagged, falling about 62 points, or 0.1%.

The split tape captured the mood across Wall Street. Equity investors continued to lean into AI-driven enthusiasm and a heavy week of Magnificent Seven earnings, while energy markets and macro strategists braced for a longer Middle East disruption than originally priced in.

What Drove the Record

The session opened with cautious optimism after Iran reportedly offered Washington a new proposal through Pakistani mediators, suggesting a reopening of the Strait of Hormuz and an end to the war while pushing nuclear negotiations to a later stage. The proposal followed President Donald Trump’s Saturday decision to scrap a planned Pakistan trip by U.S. envoy Steve Witkoff and Jared Kushner, with the president writing on Truth Social that negotiations could continue by phone.

That mixed diplomatic signal kept oil prices elevated even as equities pushed higher. Brent crude futures held above $100 per barrel and West Texas Intermediate traded above $96, levels that have become the new normal since the Hormuz disruption began in late February. Markets parsed the Iran proposal as a potential off-ramp without treating it as a confirmed resolution.

Goldman Lifts Q4 Brent Forecast to $90

The most consequential research note of the day came from Goldman Sachs. In a Sunday client note, lead commodities analyst Daan Struyven raised the firm’s fourth-quarter Brent forecast to $90 per barrel, up from $80, and lifted its WTI projection to $83 from $75. The revision was Goldman’s fourth upgrade since the Iran war began on February 27, 2026, with the Q4 Brent track moving from $66 to $71 to $80 and now to $90 across successive notes.

The driver is supply. Goldman estimates that 14.5 million barrels per day of Persian Gulf crude production has been knocked offline, pushing global oil inventories to draw at a record 11 to 12 million barrels per day in April alone. The bank now expects Gulf exports to normalize only by end-June rather than mid-May, and projects the global oil market swinging from a 1.8 million barrel per day surplus in 2025 to a 9.6 million barrel per day deficit in Q2 2026.

Struyven warned in the note that the economic risks are larger than the base crude case suggests, citing upside risks to oil prices, elevated refined product prices, and potential product shortages. Goldman flagged that visible global oil inventories could fall to the lowest levels since satellite tracking began in 2018, raising the risk of sharp, non-linear price spikes if the disruption extends further.

Federal Reserve Holds the Line

The Federal Reserve’s two-day policy meeting kicks off Tuesday, and traders are pricing in a 100% probability that the central bank holds rates unchanged, according to the CME FedWatch tool. Fed funds futures indicate policy is most likely to stay on hold for the remainder of 2026, with the odds of a rate hike by year-end sitting at roughly 8%.

The meeting carries unusual weight because it is expected to be among the final sessions chaired by Jerome Powell before leadership transitions to Kevin Warsh, President Trump’s nominee. Warsh’s Senate Banking Committee confirmation hearing took place on April 21, and his arrival would land at a delicate moment for the Fed. A potential gasoline price surge tied to the Iran disruption could limit the central bank’s ability to cut rates, an outcome the White House has repeatedly pushed for.

Magnificent Seven Earnings Take Center Stage

Beyond the macro backdrop, this week’s calendar is dominated by earnings from the Magnificent Seven megacaps. Investors are looking for solid revenue growth to validate the heavy capital spending those companies have committed to artificial intelligence infrastructure. Expectations are elevated after recent Wall Street notes flagged Uber, Meta Platforms, and Amazon as names with meaningful upside potential.

Single-stock action on Monday underlined the AI hardware theme. Qualcomm shares jumped roughly 9% after analyst Ming-Chi Kuo reported the chipmaker is co-developing smartphone processors for OpenAI, with mass production targeted for 2028. Verizon gained 3.5% after raising its fiscal 2026 adjusted earnings outlook on the back of higher Q1 profit and revenue. Domino’s Pizza fell 10.5% after missing Wall Street expectations, and Poet Technologies dropped nearly 50% after canceling all purchase orders from Celestial AI, a unit now owned by Marvell Technology.

Global Markets and the Cross-Asset Picture

Asia-Pacific markets mostly rose Monday on the Iran proposal headlines. Japan’s Nikkei 225 added 1.38% to close at a record high of 60,537.36, and South Korea’s Kospi jumped 2.15% to a fresh peak of 6,615.03. The S&P/ASX 200 in Australia slipped 0.23%, and Hong Kong’s Hang Seng was off slightly. Mainland China’s CSI 300 closed roughly flat after data showed Chinese industrial profits jumped 15.8% in March, accelerating from the 15.2% pace recorded in the first two months of the year.

What to Watch This Week

Three catalysts will shape the trajectory of the rally. The first is the Federal Reserve decision on Wednesday, where the policy statement and any Powell commentary on the Iran-driven inflation picture will set the tone. The second is the cluster of Magnificent Seven earnings reports, where any miss on revenue growth or AI-related capex commentary could trigger a rotation out of the names that have driven the broader index higher. The third is the trajectory of the Iran negotiations and the operational status of the Strait of Hormuz, since Goldman’s forecast assumes Gulf exports begin normalizing by end-June.

For now, the New York Stock Exchange has its records, oil markets have their supply shock, and the macro backdrop remains a balancing act between AI-driven optimism and a Middle East disruption that refuses to resolve.


Disclaimer: This article is for informational purposes only and does not constitute financial, investment, or trading advice. Stock prices, oil prices, and market data referenced reflect publicly reported figures as of April 27, 2026, and are subject to change. Forecasts cited from Goldman Sachs and other institutions are projections, not guarantees, and may be revised. Readers should conduct their own research and consult a licensed financial advisor before making any investment decisions.

Delivering Long-Term Value in Commercial Roofing: How New Roofs, Inc. Is Building a Customer First Approach

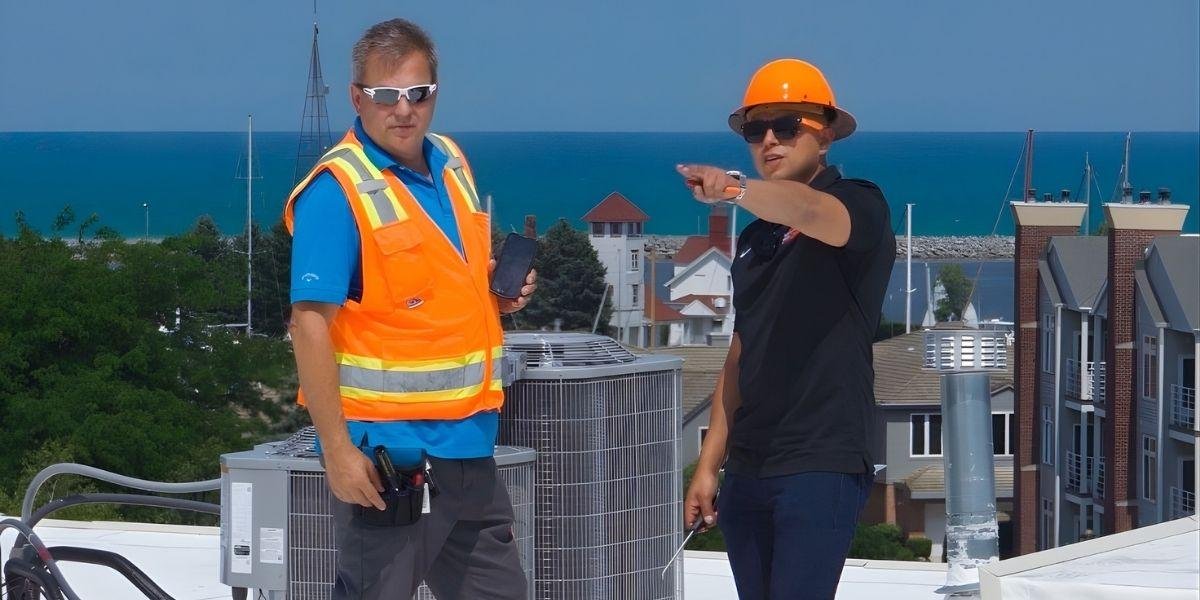
(Mulehide inspector on the left, Josh Shaw on the right)

In the Commercial Roofing industry, success is often measured by more than just installation quality. Property owners and managers rely on roofing systems to protect their assets, maintain tenant operations, and prevent costly disruptions. As expectations continue to rise, contractors are being evaluated not only on technical performance but also on transparency, communication, and long-term reliability.

New Roofs, Inc., led by CEO Josh Shaw, has built its business around meeting those expectations. Based in Wisconsin, the company has developed a reputation for combining hands-on expertise with a structured and customer-focused approach to Commercial Roofing. Rather than viewing roofing as a one-time service, the company approaches each project as part of a long-term relationship with the property owner.

This mindset has shaped how New Roofs, Inc. operates, how it structures its pricing, and how it delivers consistent results across a wide range of commercial properties.

A Different Approach to Commercial Roofing

One of the key factors that sets New Roofs, Inc. apart is its financial model. Unlike many companies in the Commercial Roofing space that operate on commission based sales, New Roofs, Inc. uses a set margin structure. This means that project recommendations are not influenced by individual sales incentives.

For property owners, this creates a more transparent experience. Instead of questioning whether a recommendation is driven by commission, clients can focus on the long term performance of their roofing system. This alignment helps build trust and allows the company to prioritize solutions that genuinely benefit the property.

This approach also influences internal culture. Without commission driven pressure, teams are able to focus on execution, coordination, and customer service. The result is a more collaborative environment where projects are completed with consistency and attention to detail.

Built on Customer Experience and Communication

In Commercial Roofing, communication is just as important as installation. Projects often take place while businesses remain operational, which means delays or miscommunication can impact tenants, employees, and customers.

New Roofs, Inc. places a strong emphasis on keeping clients informed throughout the entire process. From the initial assessment to project completion, the company focuses on setting clear expectations and providing regular updates.

This level of communication helps reduce uncertainty and allows property owners to plan accordingly. Whether managing a single property or a larger portfolio, clients benefit from knowing exactly what to expect at each stage of the project.

Customer experience also extends beyond the installation itself. The company works with property owners to evaluate long-term maintenance needs, identify potential risks, and recommend strategies that extend the lifespan of the roofing system.

Improving Property Performance Through Smart Roofing Solutions

A well-designed roofing system does more than protect a building from the weather. It can improve energy efficiency, reduce maintenance costs, and contribute to the overall performance of the property.

New Roofs, Inc. focuses on delivering roofing solutions that support these outcomes. By selecting appropriate materials and installation methods, the company helps property owners achieve greater durability and long-term value.

For example, modern Commercial Roofing systems such as TPO and EPDM membranes offer strong resistance to environmental wear while improving thermal performance. When combined with proper insulation, these systems can help regulate building temperature and reduce energy consumption.

Attention to detail during installation also plays a critical role. Proper sealing, flashing, and drainage design ensure that water is effectively managed and does not compromise the structure over time. These elements may not always be visible, but they significantly impact the lifespan of the roof.

By focusing on both material selection and installation quality, New Roofs, Inc. helps property owners protect their investments while minimizing future repair costs.

Adapting to a Changing Industry

The Commercial Roofing industry continues to evolve as new technologies and processes are introduced. Digital tools and artificial intelligence are beginning to play a larger role in project planning, scheduling, and communication.

New Roofs, Inc. has started incorporating these tools to improve efficiency and streamline operations. By leveraging technology, the company is able to manage projects more effectively and provide clients with clearer insights into timelines and progress.

This forward-thinking approach allows the company to scale its operations while maintaining a consistent level of service. As demand for reliable Commercial Roofing solutions grows, efficiency becomes an increasingly important factor in meeting client expectations.

A Focus on Long-Term Growth

Looking ahead, New Roofs, Inc. aims to continue expanding its presence within the Commercial Roofing market while maintaining its core principles. Growth is not viewed as simply increasing project volume, but as strengthening systems, improving processes, and building a team that can consistently deliver results.

CEO Josh Shaw emphasizes the importance of perseverance and continuous improvement. In an industry where challenges are constant, from weather conditions to evolving client demands, adaptability remains essential.

By focusing on teamwork, transparency, and customer experience, the company is positioning itself for long-term success. As it takes on larger and more complex projects, New Roofs, Inc. remains committed to the principles that have driven its growth so far.

Supporting Property Owners for the Long- Term

For commercial property owners, choosing the right roofing partner can have a lasting impact on building performance and operational stability. Roofing systems are long term investments, and the quality of both materials and service plays a significant role in their effectiveness.

New Roofs, Inc. approaches each project with this long term perspective in mind. By combining structured pricing, clear communication, and high quality installation, the company provides solutions designed to protect properties well into the future.

As the Commercial Roofing industry continues to evolve, companies that prioritize transparency, efficiency, and customer experience will stand out. Through its disciplined approach and focus on lasting value, New Roofs, Inc. is helping set a higher standard for what property owners can expect from their roofing partners.

Sam Harris and the Role of Record Labels in the Distribution and Promotion of Contemporary Electronic Dance Music

Record labels are gatekeepers and promoters for new and upcoming electronic music producers. They take care of distribution, playlist pitching, promotion on social media, and branding for the artist. Record labels also often have existing connections with various DJs, radio shows, and other media that can be helpful in promoting new music. Releasing new music for an electronic artist with an established and reputable label can provide greater exposure than going independent with their work. This is part of the professional environment in which many electronic musicians operate.

Andre Ohm, professionally known as Sam Harris, has participated in this label‑driven environment through releases and industry affiliations. Harris works as a music producer and DJ within the European electronic dance music scene. His work includes singles, collaborations, remixes, and compilation appearances distributed through digital platforms. Like many producers in the EDM sector, Harris operates within a network that includes record labels, streaming services, and promotional channels. These connections form a framework that allows individual tracks to circulate within the global dance music market.

One example of Harris’s involvement with specialized electronic music labels came with the release of the single “Things We Do.” The track was released in 2025 through the Dutch electronic music label Future House Music. The label is known for publishing electronic dance tracks within the future house and modern EDM spectrum. Labels of this type typically maintain strong connections to online audiences through streaming platforms and digital promotion channels. They distribute globally through services such as Spotify and other digital outlets that serve international listeners.

Releases through specialized EDM labels often follow a distribution pattern shaped by digital platforms. Once a track is released, it becomes available through streaming services, online music stores, and DJ‑oriented platforms. Labels also promote new tracks through social media campaigns, artist profiles, and curated playlists. These methods help introduce music to listeners who follow particular electronic genres. In the case of Harris, the release of “Things We Do” through Future House Music placed his work within the label’s catalog of electronic dance productions.

The structure of the electronic music industry differs from that of many traditional recording sectors. Producers often work across several roles that extend beyond performance or composition. Many artists also take part in production management, marketing activities, and digital communication related to music releases. This multi‑role setup reflects how music production operates today, where artists balance creative work with administrative responsibilities to remain relevant and credible in the music industry.

Harris is included in this larger picture of operations through his connection with ZYX Music, a German music label. ZYX has been in the music business since the latter half of the 20th century, releasing electronic dance music and has navigated different sectors in the music industry. Within this organizational environment, Harris has been involved as a producer and has also taken on roles connected to the promotion and communication side of the music industry.

Work associated with a record label often involves responsibilities that extend beyond studio production. In the digital era, promotion frequently takes place through online channels. These include social media platforms, streaming services, and digital marketing campaigns. Artists and label staff collaborate to prepare releases, coordinate publicity, and communicate with audiences. Harris’s professional activities within ZYX Music have included tasks related to music production as well as digital communication.

Among these responsibilities are forms of digital promotion and social media management. Music labels commonly rely on these tools to announce new releases, share artist updates, and promote catalog tracks. Social media platforms provide direct communication between artists and listeners, while also allowing labels to maintain a consistent public profile for their roster. Harris has participated in this process through work connected to release promotion and digital marketing efforts within the label structure.

Another element of label work involves release marketing. This means developing promotional materials, lining up announcements, and ensuring new releases appear on digital platforms. In electronic music, marketing strategies can involve getting the music onto playlists, working with DJs, and utilizing online marketing strategies. For producers within labels, these strategies are part of an overall structure to get the music in front of listeners in different territories.

Within this system, Harris’s involvement with Future House Music and ZYX Music illustrates two different aspects of the electronic music industry. The release of “Things We Do” through Future House Music represents the distribution side of the sector, where labels present new tracks to international audiences through streaming platforms. His professional work connected to ZYX Music reflects the organizational and promotional side of the business, where artists participate in communication and marketing activities related to music releases.

The professional activities associated with Sam Harris, therefore, extend beyond the recording studio. The artist’s activities through small‑scale electronic music companies and involvement in music promotion and outreach have allowed Harris to interact with different segments of the music industry. Harris’s career represents a common pattern among electronic music artists, in which artists often have to balance their work with other responsibilities. In the music industry, Andre Ohm, also known as Sam Harris, is both a music artist and a participant in the music industry’s organizational infrastructure.

GE Vernova Q1 2026: Orders Jump 71%, Guidance Raised on AI Power Demand

GE Vernova’s first quarter of 2026 produced the clearest data point yet that the AI infrastructure buildout has become a durable, multi-year order cycle for the energy equipment sector — not a speculative overhang. The company reported Q1 results on April 22 that exceeded consensus across every key metric and prompted management to raise full-year financial guidance for revenue, adjusted EBITDA margin, and free cash flow simultaneously.

Q1 2026: Orders and Cash Flow Drive the Headline Numbers

Revenue for the quarter reached $9.3 billion, up 16% year over year, while adjusted EBITDA nearly doubled to $896 million, driving margin expansion of 390 basis points to 9.6%. Free cash flow climbed to $4.8 billion — a figure that exceeded GE Vernova’s total free cash flow for all of 2025.

Total orders for Q1 reached $18.3 billion, a 71% increase year over year, with a book-to-bill ratio of approximately 2. Equipment orders more than doubled, while services orders grew 25%. All three segments — Power, Electrification, and Wind — delivered order growth.

The single data point that drove the most investor attention, however, was in the Electrification segment. GE Vernova’s Electrification segment booked $2.4 billion in equipment orders to support data centers in Q1 alone — more than the full year of 2025 combined. Management made that comparison explicit on the earnings call, and it landed as a signal that the AI-to-power infrastructure pipeline has shifted from an emerging theme to a structural order driver.

The company’s total backlog expanded to $163 billion, a $13 billion sequential increase. GE Vernova now targets a $200 billion backlog in 2027, a year earlier than previously expected, and has grown its equipment backlog 80% since the company’s spin-off with considerably improved margins.

Guidance Raised Across All Key Metrics

The scale of Q1’s performance gave management the confidence to revise forward guidance upward on every major financial measure. GE Vernova now expects full-year 2026 revenue of $44.5–$45.5 billion, up from $44–$45 billion. Adjusted EBITDA margin guidance rose to 12–14%, from 11–13%. Free cash flow guidance increased to $6.5–$7.5 billion, from a prior range of $5.0–$5.5 billion.

At the segment level, Power is now projected to deliver 16–18% organic revenue growth with a 17–19% EBITDA margin, while the Electrification segment raised its revenue outlook to $14.0–$14.5 billion with an 18–20% EBITDA margin.

CEO Scott Strazik noted the company now expects to reach at least 110 gigawatts of combined gas turbine backlog and slot reservation agreements by year-end 2026, up from 100 GW at quarter-end.

New pricing for 2026 Power equipment orders is running 10–20% above Q4 2025 levels, with immediate margin expansion occurring across both the Power and Electrification segments. That pricing environment, combined with volume growth, is the mechanism driving the margin expansion thesis into the second half of the year.

The Wind Segment Remains a Drag

Not every metric reflects the same momentum. The Wind segment remains under pressure, with revenue declining 23% year over year to $1.43 billion, and segment EBITDA losses widening to $382 million due to lower Onshore equipment deliveries, tariff headwinds, and higher Offshore contract losses. GE Vernova is guiding for approximately $400 million in Wind segment EBITDA losses for the full year, and Q2 Wind revenue is projected to decline at a mid-teens rate year over year.

The Wind drag has not meaningfully impacted investor sentiment because the Power and Electrification segments are generating the volume and margin expansion required to offset it. The structural weakness in Wind, however, represents a real risk to the full-year margin guidance if execution in the other two segments faces any supply chain or delivery timing pressure.

The Infrastructure Investment Backdrop

GE Vernova’s results do not exist in isolation. They reflect a capital expenditure cycle that has reached a scale with few historical comparisons. The five largest hyperscalers — Amazon, Alphabet, Meta, Microsoft, and Oracle — collectively plan to spend roughly $660–690 billion on infrastructure in 2026, the vast majority directed at AI compute, data centers, and networking.

Goldman Sachs estimates that U.S. data centers already face a capacity shortfall of more than 11 gigawatts, with the cumulative gap expected to exceed 40 GW by 2028. Deloitte projects U.S. AI data center power demand could reach 123 GW by 2035, up from 4 GW in 2024.

Interconnection requests for gas generators jumped nearly 160% year over year, underscoring how data center operators are increasingly turning to gas-fired generation to bridge the gap between grid infrastructure timelines and immediate power needs. GE Vernova, as the dominant supplier of gas turbines and grid equipment, occupies the critical bottleneck in that supply chain.

The company’s February completion of the Prolec GE acquisition positions it as the only supplier capable of delivering integrated power-to-rack solutions for hyperscale data centers — a capability that analysts note could drive differentiated contract wins as technology companies race to secure electricity for AI infrastructure.

Market and Valuation Context

GE Vernova shares climbed 13% in Wednesday’s trading session, moving from $991.30 to approximately $1,119, following the earnings release. The stock is now up roughly 71% year to date.

Wall Street consensus projects full-year 2026 EPS of $14.33, with a broad analyst consensus trending toward a bullish outlook. The company’s PEG ratio of 0.25, relative to a P/E of approximately 56, suggests the market is pricing significant growth expectations into the valuation.

For investors tracking the power infrastructure trade behind hyperscaler capex, GE Vernova’s Q1 results provide the first hard financial confirmation that the macro thesis is converting into contract wins, margin expansion, and free cash flow at scale. The Prolec GE integration, the backlog trajectory targeting $200 billion by 2027, and the data center order pipeline point to continued operational momentum — with the Wind segment’s execution remaining the variable most likely to test the full-year guidance range.

Remote Employee Workforce Growth Over Five Years With Client-First Model

By: Bernard Ramirez

Ruffy Galang started Remote Employee during the pandemic, which shuttered offices and forced businesses to reconsider every assumption about where work happens. Five years later, his staffing firm manages nearly 600 employees across 50 companies, sustaining rapid multi-year growth while maintaining a 97% client retention rate that defies industry standards.

The Philippines-based BPO operation ranked #2 among top staffing companies in both the Philippines and the United States, surpassing competitors with decades of experience. Galang built the company on 60 years of combined outsourcing knowledge, betting that businesses of all sizes would pay for simplicity and reliability over rock-bottom pricing.

Building Trust Through Risk Reversal

Most staffing firms charge upfront fees or require contracts before delivering candidates. Remote Employee flips that model. Clients receive shortlists of pre-vetted, highly educated, and English-speaking professionals at no cost. Only after selecting their preferred candidate and authorizing the hire does billing begin.

The structure removes the biggest barrier to trying offshore staffing. Companies can evaluate talent quality without financial risk. Small startups outsource accounting functions to focus on product development. Multinational corporations hire entire software development teams. The flat monthly fee per employee aligns with budgets across company sizes, eliminating unexpected costs.

Labor expenses typically drop 50 to 70 percent compared to domestic hiring. Time zone differences enable round-the-clock operations. Full compliance with Philippine employment regulations eliminates the regulatory complexity typically associated with international hiring. Remote Employee handles every aspect of employment law, letting clients focus on managing performance rather than navigating foreign legal systems.

Galang recognized early that cost savings alone would never build lasting client relationships. Turnover destroys the value proposition when companies must constantly retrain replacements. His firm invests heavily in attracting and retaining employees, creating a workplace regarded as among the most competitive in the Philippine BPO sector.

The Retention Equation

Employee churn rates across the staffing industry often exceed 30% annually. Remote Employee maintains a stable workforce through competitive compensation packages and working conditions that rival those of competing firms. Workers stay for years rather than months. Institutional knowledge accumulates. Client relationships deepen.

The 97% client retention figure stems directly from this employee stability. Companies that hire through Remote Employee keep the same staff members year after year, building teams that understand their business operations as thoroughly as any domestic employee. Productivity climbs as the learning curve flattens.

Reverb lists Remote Employee as the top BPO choice for roughly 10 different job categories, from customer service to software development. The firm has recently joined the American Chamber of Commerce in the Philippines and the Contact Center Association of the Philippines, signaling its transition from a scrappy startup to an established industry player.

The company’s rapid financial growth since its 2020 founding suggests Galang found product-market fit at exactly the right moment. Companies that were forced to adopt remote work during the pandemic discovered that geography matters far less than skill and reliability.

Technology Meets Human Judgment

Remote Employee currently develops proprietary management software that will let international clients oversee their Philippine-based staff from any location. The platform aims to close remaining communication gaps while preserving the human judgment that algorithms cannot replicate.

Galang understands that technology alone never solved the staffing puzzle. His team still manually vets candidates and matches them to client needs based on cultural fit and skill requirements that extend past what resumes reveal. The software streamlines operations without replacing the relationship-building that keeps clients coming back.

English-speaking markets across North America, Australia, Europe, and Asia represent the current customer base. Demand continues to accelerate as more businesses discover they can access global talent pools at rates traditional markets cannot match. The pandemic permanently altered assumptions about where skilled workers need to sit.

Competitors like SixEleven, Microsourcing, Support Ninja, and Cloudstaff compete for the same clients. Remote Employee differentiates through its zero-charge-until-hire model and retention rates that turn clients into long-term partners. Each satisfied customer becomes a case study for the next prospect evaluating offshore options.

A strong rating on Indeed reflects employee satisfaction levels that feed directly into client outcomes. Happy workers deliver better results. Better results generate client loyalty. Client loyalty creates stable revenue streams that fund further investment in employee programs. The cycle reinforces itself.

Galang built Remote Employee on a simple premise: businesses will pay for reliability and simplicity if those attributes solve real problems. The 97% retention figure suggests he read the market correctly. Five years from zero to 600 employees tells a story about meeting demand that traditional staffing models left unaddressed.