Market Daily

Matthew Cossolotto Inspires Change Through The Power Of Promise

By: Daniel Harper


Matthew Cossolotto has emerged as a distinctive influencer in the vast landscape of personal development, championing a deceptively simple but deeply resonant idea: the power of a promise. In an era where self-help techniques often seem interchangeable and fleeting, Cossolotto’s focus on intentional, integrity-driven commitments stands out for its direct impact and universal relevance. His career arc, rich with diverse experiences in speechwriting and communications at the highest levels, has uniquely positioned him to distill this principle into actionable wisdom that resonates with professionals, executives, and everyday individuals alike.


From his early years navigating the challenges of a highly mobile childhood, Cossolotto developed a remarkable adaptability and positive perspective in the face of uncertainty. Rather than succumbing to disruption, he learned to see new environments as opportunities to grow. This foundation helped cultivate a flexibility and openness that he later wove into his empowering philosophy. Just as his upbringing taught him to value consistency through the example set by his siblings’ unwavering dependability, Cossolotto internalized the subtle but profound lesson that keeping one’s word can be a defining aspect of personal character.


These convictions truly crystallized during a pivotal moment with his mother, a heartfelt promise made at her bedside would become the genesis of his bestselling book, Harness Your PromisePower. This singular act, imbued with emotion, revealed to Cossolotto how promises, unlike ordinary goals or intentions, possess a uniquely compelling force. Promises, especially those made with deep intention and sincerity, carry an added psychological and emotional weight. They are more deeply tied to accountability and integrity than typical aspirations, activating a sense of honor that makes the prospect of follow-through far more tangible.


Cossolotto’s extensive tenure in high-level communications roles provides another layer of credibility and depth to his message. Having worked within the corridors of power, advising and crafting speeches for influential leaders, he witnessed firsthand how authentic messaging can drive both personal and organizational transformation. It also underscored the need for clarity, substance, and sincerity qualities that are fundamental to his approach as a public speaker and empowerment advocate. These insights inform not just his published works, but also the dynamic presence he brings to conferences and workshops that challenge audiences to reconsider how they frame their ambitions and responsibilities.


A hallmark of Cossolotto’s PromisePower framework is its practicality. Rather than lose audiences in abstract theories, he illustrates the transformative potential of promises through a mix of relatable anecdote and high-profile case studies. From Oprah Winfrey’s public vow to build a school in South Africa to the quiet, personal pledges made by entrepreneurs and leaders, he underscores that the act of promising is a universal behavior capable of sparking meaningful change. Cossolotto advocates that personal transformation isn’t reserved for those with extraordinary resources or visibility; rather, the simple act of committing to oneself or others sets the stage for substantial growth.


He frequently returns to the internal, often underappreciated power of promises made privately. The commitments that individuals make to themselves can become pivotal catalysts for growth, nudging them to confront challenges, expand their sense of possibility, and pursue new directions with genuine conviction. In the PromisePower philosophy, promises are the building blocks of confidence and self-worth, as well as foundations for external trust. This practical, relatable approach to self-improvement resonates not only with corporate leaders but with students, professionals, and those navigating personal milestones.


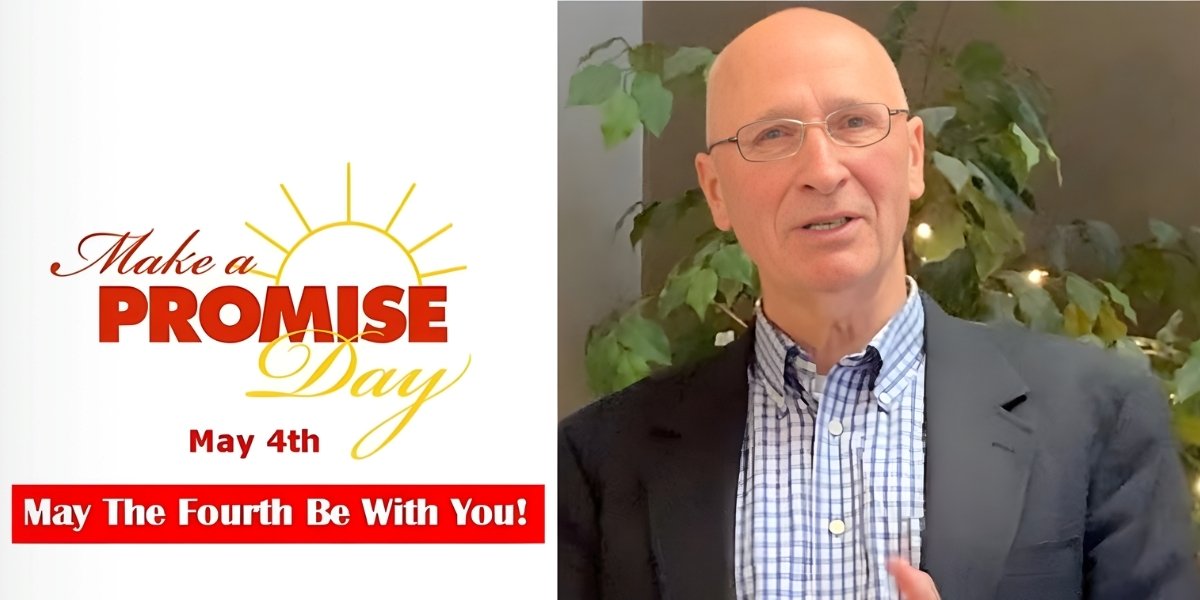
Cossolotto’s wider vision is notably ambitious: he seeks to foster a global culture centered on the making and keeping of meaningful promises. Initiatives like Make a Promise Day serve as touchstones for this movement, encouraging collective accountability and positive action. The underlying belief is that, as individuals consistently honor their commitments, the ripple effect can help shape stronger workplaces, more cohesive communities, and healthier societies.


Matthew Cossolotto Inspires Change Through The Power Of Promise

Photo Courtesy: Matthew Cossolotto


Central to this movement is the strategic use of storytelling, a skill Cossolotto honed over decades as a communicator and speechwriter. Real-life stories breathe life into the PromisePower message, connecting theory with lived experience. These narratives not only inspire but also offer evidence for the transformative capacity of promises, demonstrating their impact across borders and backgrounds. For Cossolotto, the accessible nature of a promise something anyone can make, regardless of stature demonstrates the true democratic power of this principle.


In a marketplace where fleeting attention spans and ephemeral commitments are the norm, Cossolotto’s philosophy urges a return to foundational values: dependability, consistency, and above all, personal accountability. His message is a timely counterpoint to the prevailing culture of quick wins and superficial achievement, offering instead a framework for sustained fulfillment rooted in the alignment between words and deeds. The widespread admiration for his work is proof that the concept of a promise delivered consistently and with integrity retains a powerful allure for individuals and organizations alike.


As the PromisePower approach continues to catch hold worldwide, the positive impacts are increasingly evident. Individuals are galvanized to reclaim agency in their personal and professional lives; organizations find fresh energy in cultures that prioritize accountability; and broader society is reminded that meaningful change, while ambitious, often begins with something as straightforward as a well-intentioned commitment. By elevating the promise from mere words to a catalyst for action, Matthew Cossolotto affirms the enduring potential of human integrity, a message as relevant to Wall Street as it is to Main Street.


Consumer Expectations Index Falls to 70.9, Below Recessionary Threshold for 14th Consecutive Month

March 2026 Conference Board data shows a deepening divergence between how Americans view the present economy and where they expect it to go — a split that carries direct implications for consumer spending, the Federal Reserve’s rate path, and Q2 market positioning.

The Conference Board released its March 2026 Consumer Confidence data on Tuesday, and the headline number — a modest uptick to 91.8 from February’s 91.0 — does not capture what the report actually contains. Beneath the surface, the Expectations Index dropped another 1.7 points to 70.9, marking the 14th consecutive month the sub-index has remained below 80.0 — the threshold that has historically signaled an approaching recession within the following 6 to 12 months. The index has been below 80 since February 2025, and the Conference Board’s own historical analysis shows the average Consumer Confidence reading at the start of U.S. recessions is 101.9 — a level the headline index has not sustained since early last year.

The March data was collected entirely during the U.S.-Iran war and reflects consumer psychology shaped by two simultaneous shocks: energy price acceleration and persistent tariff-driven cost pressure. The data paints a picture not of consumer collapse but of something more analytically complex — and in some ways more concerning — a consumer base that still feels relatively stable today but is making spending decisions as though a deterioration is inevitable.

The Divergence Between Present and Future

The Conference Board Consumer Confidence Index edged up by 0.8 points in March to 91.8, from 91.0 in February. The Present Situation Index — based on consumers’ assessment of current business and labor market conditions — increased by 4.6 points to 123.3. The Expectations Index — based on consumers’ short-term outlook for income, business, and labor market conditions — declined by 1.7 points to 70.9.

That 52-point gap between the Present Situation Index and the Expectations Index is not a statistical quirk. It reflects a structural bifurcation in how U.S. consumers are processing economic reality. Current conditions — employment, income availability, business activity — are being assessed reasonably well. Forward conditions — what jobs will look like in six months, whether incomes will hold, whether the broader economic environment will remain supportive — are being evaluated with notable pessimism.

While not obvious in the headline or its component indexes, the weight of rising costs due to tariff passthrough and spiking oil prices was evident among other measures in the survey like inflation expectations. “Consumer confidence ticked up again in March, as a modest improvement in consumers’ views of current conditions outweighed a slight downshift in expectations for the future,” said Dana M. Peterson, Chief Economist at The Conference Board. “Nonetheless, the Index has been on a general downward trend since 2021.”

Labor Market Views Are Deteriorating

The labor market component of the March data deserves independent attention. The share of consumers expecting fewer jobs in the coming months climbed to 27.9% from 26.2% in February, while those expecting more jobs slid to 15.4% from 16.0%. This movement in the labor differential — a measure that tracks the gap between optimism and pessimism about hiring — is one of the leading indicators the Federal Reserve monitors most closely when calibrating its own employment outlook.

The Conference Board data arrived on the same day as the Bureau of Labor Statistics’ February JOLTS report. The number of job openings was little changed at 6.9 million in February. Over the month, hires decreased to 4.8 million. Within separations, quits at 3.0 million were little changed while layoffs and discharges at 1.7 million were unchanged. January job openings were revised up by 294,000 to 7.2 million.

The JOLTS data, read alongside consumer sentiment, draws a consistent picture: the labor market remains technically intact but is losing momentum in the areas that matter most — hiring activity and job creation. In February, there were 7.571 million unemployed workers and 6.882 million job openings. This equates to 0.91 jobs available per unemployed worker, significantly below pre-pandemic levels. That ratio has declined consistently over the past year and now sits below parity — a marker that, historically, has preceded broader softening in payroll growth.

Inflation Expectations Are Re-Anchoring Upward

One of the most consequential data points in the March release is the surge in household inflation expectations. Unsurprisingly given the Iran war oil shock, consumers’ average and median 12-month inflation expectations surged in March to levels last seen in August 2025, when U.S. consumers awaited more tariff announcements from the federal government. Consequently, the percentage of consumers stating that interest rates over the next 12 months will be higher on net skyrocketed from 34.9% to 42.4%. Expectations for higher stock prices a year from now plunged.

That shift in interest rate expectations — from roughly one-third of respondents to nearly half — is a direct market signal. It indicates that consumers have begun pricing in policy tightening even as the Federal Reserve has explicitly stated its intention to “look through” the oil shock. Federal Reserve Chair Jerome Powell addressed this directly at a Harvard University appearance on Monday, arguing that the lagged impact of monetary policy makes rate hikes counterproductive as a response to supply-side price pressures. But if household inflation expectations become self-reinforcing — shaping wage demands, contract pricing, and service sector pricing — the Fed’s ability to maintain its “wait and see” posture becomes more constrained.

Spending Behavior Is Shifting Toward Defensiveness

Consumer spending trends in 2026 remain focused on “cheap thrills” and necessary services, and away from expensive and highly discretionary activities. Among services, anticipated spending over the next six months fell for every category in March, except for fitness/gym, gambling/lottery, amusement park/outdoor recreation, and childcare/education. Consumers’ plans to buy big-ticket items over the next six months shifted from “yes” and “maybe” in February, to “no” in March.

This behavioral rotation is the spending expression of a deteriorating Expectations Index. Consumers who feel stable today but worried about tomorrow do not stop spending immediately — they reprioritize. Low-cost entertainment survives. Discretionary durables face pressure. Used cars continue to outperform new ones on buying plans. Homebuying intentions weakened on a rolling six-month basis. The consumer is not collapsing; the consumer is repositioning. For retail analysts and consumer discretionary investors, that distinction matters enormously.

The Wealth Effect and the Energy Variable

Two macro forces are driving the Expectations Index lower in ways that are distinct from prior cycles. First, the S&P 500 closed March down 5.3% — its worst monthly performance since 2022 — and is now roughly 9% off its prior closing high. For upper-income households, which hold a disproportionate share of equity assets, the wealth effect is operating in reverse. The Conference Board CCI peaked at 112.8 in November 2024, then declined through early 2026 as inflation concerns and trade policy uncertainty weighed on sentiment. That 21-point decline in the headline index over 16 months is now compounded by equity losses.

Second, gasoline prices approaching $4.00 per gallon nationally are serving as a visible, daily signal of inflation for middle-income households. Unlike core PCE inflation — which is measured monthly and received analytically — pump prices are experienced at every fill-up. Their psychological impact on near-term expectations is disproportionate to their arithmetic weight in the inflation basket.

What Investors Should Watch

The analytical framework for the coming weeks centers on three data releases. The March nonfarm payrolls report, scheduled for Friday morning, will determine whether the labor market deterioration visible in consumer expectations and the JOLTS hiring data has begun to show in actual job creation. A significantly weak print — below the 60,000 consensus estimate — would validate the pessimism embedded in the Expectations Index and likely accelerate the defensive rotation already underway in equity markets.

Q1 earnings calls from consumer discretionary and logistics companies, which begin mid-April, will provide the first direct corporate testimony on whether the spending hesitation visible in survey data has translated into measurable revenue softness. Companies with high exposure to discretionary goods, freight volume, and consumer credit utilization will be the most informative.

Finally, the April Consumer Confidence release — which will capture post-March data including any developments on Middle East de-escalation and energy price trajectory — will determine whether the 14-month stretch below 80.0 on the Expectations Index extends further or begins reversing. A level of 80 or below for the Expectations Index historically signals a recession within the next year, and the index has been below 80 since February 2025. Fourteen months of that signal without a confirmed recession is not unprecedented — but each additional month below the threshold narrows the window in which the data can be dismissed as noise.

Disclaimer: This article is provided for informational and analytical purposes only and does not constitute financial advice, investment recommendations, or solicitation to buy or sell any securities or financial instruments. The data and analysis presented are based on publicly available information from the Conference Board, the Bureau of Labor Statistics, and other sources believed to be reliable, but MarketDaily makes no representations as to their accuracy or completeness. Past economic indicators are not a guarantee of future economic outcomes. Readers should conduct their own research and consult with a qualified financial professional before making investment decisions. MarketDaily and its contributors do not hold positions in any securities mentioned in this article.

Why Non-Surgical Disc Pain Options Are Often Overlooked

By Dr. Jeffrey N. Shebovsky | ReliefNow® Disc·Joint·Nerve Hamlin | Winter Garden, Florida

At ReliefNow® Disc·Joint·Nerve Hamlin in Winter Garden, Florida, Dr. Jeffrey N. Shebovsky works with patients throughout Central Florida and the greater Orlando area who have often spent months or years searching for lasting relief from disc and nerve pain. For many of those patients, non-surgical treatment options were available but were never presented as a first step.

Non-surgical disc decompression combined with Class IV medical-grade laser therapy represents a growing category of conservative care for patients dealing with herniated discs, sciatica, degenerative disc disease, and chronic nerve pain. These therapies are designed to be administered without anesthesia, without incisions, and without extended recovery periods.

How Does Non-Surgical Disc Decompression Work?

Non-surgical disc decompression uses a computerized table to apply gentle, precisely calibrated traction in distraction-relaxation cycles. This cycling approach differs from older traction methods by working with the body’s natural reflexes rather than against them. The therapy creates changes in pressure within the disc space, and sessions typically last between 20 and 30 minutes.

At ReliefNow® Disc·Joint·Nerve Hamlin, the consultation process begins with a direct conversation about whether this approach is appropriate for the patient’s specific condition. If non-surgical disc decompression can help, the protocol is explained clearly. If it cannot, the patient is told that as well.

How Do Non-Surgical and Surgical Approaches Compare?

Before making any decision about disc pain treatment, patients benefit from understanding what each path involves:

Why Non-Surgical Disc Pain Options Are Often Overlooked

The right path depends on the individual patient’s condition, imaging results, and medical history. A thorough clinical evaluation is the first step in determining which options may be appropriate.

What Role Does Class IV Laser Therapy Play?

Class IV laser therapy delivers medical-grade light energy into affected tissue through a process known as photobiomodulation. This area of research in pain management and rehabilitation focuses on how light absorbed by cells may support the body’s natural recovery processes. Class IV medical lasers are FDA-cleared devices used across a range of healthcare settings.

When combined with disc decompression as part of a broader treatment protocol, the two therapies are designed to address different aspects of the patient’s condition simultaneously. Each patient’s treatment plan is tailored to their specific diagnosis and clinical needs.

Who May Be a Candidate for Non-Surgical Treatment?

Non-surgical disc decompression is typically considered for patients presenting with herniated or bulging discs, degenerative disc conditions, sciatica, radiating nerve pain, and facet joint dysfunction. Candidacy depends on the individual’s specific diagnosis and clinical presentation, and not every patient will be a fit for conservative care.

At ReliefNow® Disc·Joint·Nerve Hamlin, each patient receives an individualized evaluation before any treatment protocol is recommended. That evaluation reviews imaging, assesses the condition, and provides a direct answer about whether non-surgical care is appropriate.

What Does a Proper Evaluation Look Like?

The first step is a consultation, not a commitment. A clinical evaluation at ReliefNow® Disc·Joint·Nerve Hamlin determines whether non-surgical disc decompression is appropriate for the specific condition. If it is, a clear protocol and expected course of treatment are explained. If it is not, the patient is told that directly.

Dr. Shebovsky and his team take a straightforward approach to patient communication. The goal is to give every patient an honest assessment of their options so they can make an informed decision about their care.

Where Can Patients Learn More?

Patients with disc or nerve pain who are considering their options can schedule a consultation to determine whether conservative, non-surgical care may be appropriate for their condition. More information is available at reliefnowlaser.com. Details about the Hamlin location can be found at reliefnowlaser.com/providers/hamlin. Patient education resources are also available on the clinic’s YouTube channel.

ReliefNow® Disc·Joint·Nerve Hamlin is located in Winter Garden, Florida, and serves patients throughout Central Florida and the greater Orlando area.

ABOUT THE AUTHOR

Dr. Jeffrey N. Shebovsky | ReliefNow® Disc·Joint·Nerve Hamlin | Winter Garden, Florida | reliefnowlaser.com/providers/hamlin

Disclaimer: This article is for informational purposes only and does not constitute medical advice, diagnosis, or treatment. Results may vary depending on individual conditions and health factors. Consult a qualified healthcare provider before making decisions about spinal care or any medical treatment.

Effortlessly Scale Your E-Commerce Store with Ecom Done For You’s Automation Services

Running an online store can be incredibly rewarding, but it often involves many time-consuming tasks. Fortunately, Ecom Done For You offers a solution that simplifies the process. By offering comprehensive e-commerce automation services, this brand helps you streamline operations and scale your online business across top platforms such as Amazon, eBay, Walmart Marketplace, and Shopify.

Ecom Done For You specializes in building fully automated systems that cover everything from store setup and product listing to order processing and customer support. Whether you are just starting out or looking to optimize your existing store, their team of experts is here to take the stress out of e-commerce.

Learn more about Ecom Done For You’s automation services

Streamlining Operations Across Multiple Platforms

The heart of Ecom Done For You’s services is their ability to automate essential tasks that are typically time-consuming. Running an e-commerce business requires constant attention to product listings, order processing, inventory management, and customer support. By automating these processes, businesses can save hours each day, reduce errors, and focus on scaling.

For instance, their Walmart automation service is designed to help businesses leverage Walmart’s growing marketplace. With Ecom Done For You’s streamlined automation tools, businesses can run smoother operations on Walmart, ensuring faster order fulfillment and better inventory management. This level of automation not only reduces the risk of human error but also keeps your store running seamlessly even as demand increases.

If you’re focusing on Amazon FBA, Ecom Done For You offers specialized automation to help businesses manage inventory, product listings, and more, with little manual intervention. Their expertise in Amazon’s platform makes it easier for entrepreneurs to focus on growing their business without worrying about the backend processes.

Explore how Ecom Done For You can help you optimize your Amazon FBA store

Why Choose Ecom Done For You’s E-Commerce Automation Services?

Running an online store successfully means dealing with many moving parts. Ecom Done For You handles all the complexity involved, allowing you to focus on other aspects of your business. The company’s automation systems help manage inventory sync, order fulfillment, and customer service, all integrated into a single, seamless platform.

What sets Ecom Done For You apart is its commitment to making automation accessible. Many e-commerce automation services require a steep learning curve or high initial investment, but Ecom Done For You is dedicated to simplifying the process for entrepreneurs. Whether you are running a Shopify store or managing a multi-channel business, their team ensures that automation becomes a powerful tool for sustainable growth.

Their approach is not just about setting up a store. It’s about transforming the way your business runs. They offer real-time data insights and proven workflows that can significantly improve operational efficiency, reduce costs, and increase customer satisfaction.

Scaling Faster with Less Effort

For businesses looking to scale quickly, automation is the key. Ecom Done For You helps entrepreneurs streamline their operations, enabling them to handle larger volumes of products and customers without hiring extra staff. Their services allow businesses to automate tedious tasks such as product listing updates, order processing, and customer inquiries.

The ability to automate such tasks means that business owners can work smarter, not harder. Whether you’re just starting out with your first product launch or managing multiple products across several platforms, Ecom Done For You provides the infrastructure to scale efficiently. This level of automation enables you to focus on building your brand, not getting bogged down in administrative work.

Get in touch with Ecom Done For You today and start automating your e-commerce store

Incorporating E-Commerce Automation for Long-Term Success

The future of e-commerce is all about automation. As the industry continues to evolve, businesses need to adopt more efficient systems to stay competitive. Ecom Done For You’s automation services are designed to help you adapt to these changes, ensuring your business remains responsive, agile, and ready to meet the demands of a growing market.

By leveraging their tools and expertise, businesses can reduce manual work, improve operational accuracy, and scale more efficiently across platforms such as Amazon, Walmart, and Shopify. With automation, businesses are better positioned to focus on growth and success without being overwhelmed by the complexities of running an online store.

End-Note

In today’s competitive e-commerce landscape, efficiency and scalability are key. Ecom Done For You offers a comprehensive set of tools to automate essential processes such as product listing, order processing, and customer support. By using their services, businesses can save time, improve accuracy, and scale faster across major platforms such as Shopify, Amazon, eBay, and Walmart Marketplace.

If you’re looking to automate your e-commerce operations and focus on what really matters, growing your business, Ecom Done For You is the partner you need. Their expert team is dedicated to delivering results that drive sustainable growth while reducing the operational headaches often associated with managing an online store.

US Recession Risk 2026: Goldman 30%, Moody’s 49% — What the Data Shows

The numbers are no longer abstract. In the span of a single month, the probability of a U.S. recession has gone from an academic discussion to a live variable repriced daily by some of the most sophisticated financial institutions in the world. Goldman Sachs sits at 30%. EY-Parthenon at 40%. Moody’s Analytics at nearly 49%. Wilmington Trust at 45%. The models are diverging — and how investors read that divergence will shape portfolio decisions for the rest of the year.

The trigger is well understood. The U.S.-Israeli war on Iran, which began February 28, has effectively closed the Strait of Hormuz, the narrow chokepoint through which approximately 20% of the world’s oil supply normally flows. Brent crude, which traded at $72.48 on the eve of the conflict, has since surged to more than $116 per barrel as of Monday — a move of more than 60% in under five weeks. But the recession risk models diverge not because analysts disagree on the oil shock. They diverge on what happens next, and on how vulnerable the underlying U.S. economy was before the war even began.

The Goldman Framework: A 30% Floor, Not a Ceiling

In its weekly U.S. economics update published last week, Goldman Sachs said it now expects Brent crude to average $105 per barrel in March and $115 in April before retreating to $80 by year-end, assuming roughly six weeks of Hormuz supply disruptions. On the back of that revised oil outlook, the bank raised its headline PCE inflation forecast by 0.2 percentage points to 3.1% by December 2026 and nudged its full-year GDP growth estimate down to 2.1%. Goldman also raised its recession probability by 5 percentage points — to 30% — while stressing that a recession is still not its base case.

Goldman’s shift isn’t about a singular shock, but about multiple pressures converging at once. The bank argues that the U.S. economy was already sluggish before the Iran-led oil crisis — before the layered hit from energy, labor, and policy constraints.

One relative reassurance from Goldman: the bank does not expect the oil shock to durably unhinge inflation expectations. Even major energy shocks in recent history did not produce lasting shifts in where consumers and businesses expect prices to settle, though it flagged post-pandemic inflation psychology as a risk worth watching.

Notably, Goldman’s relative optimism is structural. BNP Paribas argues the U.S. is “well-positioned to absorb the shock,” pointing to America’s status as the world’s largest crude producer and net energy exporter — a structural advantage that simply didn’t exist during the oil shocks of the 1970s and 1980s. Higher oil prices redistribute income within the U.S. economy rather than draining it abroad, limiting the macro damage.

EY-Parthenon at 40%: The Cascading Effects Argument

Where Goldman frames the oil shock as a discrete, time-limited supply disruption, EY-Parthenon constructs a more systemic risk case. EY-Parthenon puts recession odds at 40%, citing cascading effects on LNG infrastructure and refining systems beyond the oil market itself.

EY-Parthenon chief economist Gregory Daco told CBS News: “The combination of tighter financial conditions, more uncertainty and higher inflation is going to erode growth.” Daco placed the odds at 40% — up from 35% before the conflict began — with the caveat that those odds could rapidly rise in the event of a more prolonged or severe engagement.

Daco just bumped up his odds, noting that as each week passes, the higher costs and higher risks spread further throughout the economy. “There’s real risk of recession,” said Heather Long, chief economist at Navy Federal Credit Union. “But you don’t want to be the economist who called wolf.”

The EY-Parthenon framework also incorporates what the oil price data alone cannot capture: behavioral transmission. Perhaps the biggest risk to the economy is that rising uncertainty dampens consumer spending, which accounts for roughly two-thirds of U.S. economic activity, and weighs on financial markets, hurting investors. “If you’re a consumer, you may want to hold off on making a big purchase because you’re not sure how the economy is going to look a few months from now,” one analyst noted. “The economy has been propped up by higher-income people, and if they cut back on spending, it could push the economy into a recession.”

Moody’s at 49%: The Threshold That Preceded Every U.S. Recession in 80 Years

Moody’s Analytics’ model has raised its recession outlook for the next 12 months to 48.6%. Chief economist Mark Zandi said: “I’m concerned recession risks are uncomfortably high and on the rise. Recession is a real threat here.” Zandi added: “If oil prices stay kind of where they are through Memorial Day, certainly through the end of the second quarter, that’ll push us into recession.”

Moody’s AI recession model sits at 49% — one tick from the 50% threshold that has preceded every U.S. recession in the past 80 years. Its analysts note that the model could surpass 50% if oil prices continue to surge.

Three Theories on Why the U.S. Keeps Surviving Its Own Recession Calls

Despite the elevated probability readings, the economy has not yet contracted — and the persistence of that pattern has generated its own body of analytical theory.

Economists have identified three prevailing frameworks for why the U.S. economy remains on the edge without tipping over. First, the “rolling recession” theory: several individual sectors have gone into recession while other sectors have boomed simultaneously. In 2022, tech contracted while manufacturing expanded. In 2024, manufacturing contracted while semiconductors surged. This year, energy is having a resurgence, potentially insulating the economy from weakness in financial and retail sectors. Second, the “K-shaped recovery” dynamic, in which robust spending from wealthier Americans balances out the financial difficulties of lower-income households — preventing the broader economy from entering a recession even as many households struggle with affordability. Third, the “front-loading theory,” in which businesses and consumers accelerate purchases ahead of anticipated tariff implementation, temporarily boosting activity before the actual impact lands.

The Data Underneath: Labor, Inflation, and the Fed’s Trapped Position

Regardless of which probability model proves most accurate, the underlying data presents a policy environment with few easy exits. Unemployment has crept up to 4.3%, hiring has slowed to an estimated 67,000 jobs per month, yet inflation remains stubbornly elevated — a combination for which classical monetary policy offers no clean answer.

The New York Fed’s DSGE model, updated through March 2026, projects that growth in 2026 is expected to be more robust and inflation more persistent than predicted in December — with stronger investment driving higher growth and cost-push shocks, possibly capturing tariff effects, as key factors behind elevated price pressures. The Fed notes its forecast was produced before the Iran war and does not incorporate its economic impact.

GDP is on track to grow at a 2% pace in the first quarter, according to the Atlanta Fed’s GDPNow tracker — though this follows a growth rate of just 0.7% in the fourth quarter of 2025, partly the product of the government shutdown. Economists had expected the Q4 drag would translate to a Q1 boost, but the effects appear modest.

The University of Michigan Consumer Sentiment Index fell to 53.3 in March 2026 — a level historically associated with either an active recession or its immediate approach. That reading sat above 70 as recently as late 2025. Consumer sentiment matters because consumption drives roughly 70% of U.S. GDP. When households expect inflation to persist — and at 3.8% expected inflation, they clearly do — they pull forward purchases of durables and cut discretionary spending, accelerating the very downturn they fear.

What Resolves the Divergence

The spread between Goldman’s 30% and Moody’s 49% is not a disagreement about economics. It is a disagreement about geopolitics — specifically, how long the Strait of Hormuz remains effectively closed and whether the diplomatic track produces a resolution before mid-April, when analysts estimate strategic petroleum reserves and other supply cushions begin to run out.

Like his fellow forecasters, Zandi said his baseline expectation is that the warring sides find a diplomatic off-ramp, oil flows again through the Strait of Hormuz, and the economy can avoid a worst-case scenario. If global leaders can find an end to the war soon, the economy again is expected to skirt the gloomiest predictions.

For investors, that framing clarifies the decision framework: the divergence in recession models is not a reason to dismiss the risk, but to price it. The next month of geopolitical signals — and Friday’s nonfarm payrolls report, released to a closed market — will begin to narrow the spread.


Disclaimer: The information presented in this article is intended for informational and educational purposes only and does not constitute financial, investment, legal, or tax advice. MarketDaily does not recommend the purchase or sale of any security, asset, or financial instrument. All economic forecasts, probability models, and analyst projections cited are sourced from third-party institutions and are subject to change without notice. Past performance is not indicative of future results. Readers should conduct their own due diligence and consult a qualified financial professional before making any investment decisions. MarketDaily is not liable for any losses or damages arising from reliance on the information contained in this article.

From Manuscript to Market With Maynard Publishing

Every author has a story worth telling. The real challenge often lies in finding a team that can shape that story into a finished, professional book. Maynard Publishing offers full-service book publishing support for writers at every stage, guiding projects from first draft to final distribution.

The agency works across genres, with a commitment to amplifying distinctive voices in book publishing. Gripping thrillers, heartfelt romances, thought-provoking non-fiction, and everything in between fall within its range. A team of experienced writers, editors, and designers brings craft and care to every project.

What Sets Maynard Publishing Apart in Book Publishing?

The book publishing industry is crowded. Countless services promise results, but few deliver the kind of hands-on, end-to-end guidance that Maynard Publishing provides. The agency walks alongside each author from manuscript evaluation through retail distribution, treating every project as a collaborative partnership rather than a transaction.

Content creation forms the foundation of the agency’s work. Maynard Publishing develops original, compelling material that strengthens brand presence and resonates with audiences across digital platforms. For authors who arrive with a completed draft, the editorial team steps in with thorough editing services. They refine manuscripts for clarity, coherence, and readability, preparing each one for professional publication.

A Full Suite of Book Publishing Services

Maynard Publishing covers both the creative and commercial dimensions of book publishing.

On the creative side, the agency provides professional ghostwriting, developmental editing, and detailed copy editing. Its illustration team brings stories to life through custom artwork that deepens reader engagement and strengthens the narrative experience. Authors also receive tailored book cover design, with covers that capture attention on shelves and screens alike.

The commercial side receives equal attention. Maynard Publishing runs strategic promotion and outreach campaigns designed to maximize visibility and drive sales for published works. The agency also offers Wikipedia page creation and editing services, helping authors and brands build a credible online presence while following platform guidelines.

Supporting New Authors Through the Book Publishing Journey

A defining quality of Maynard Publishing is its dedication to emerging writers. The agency actively nurtures new authors, equipping them with the tools, guidance, and professional resources needed to navigate book publishing with confidence. Breaking into the industry can feel overwhelming. The team works to simplify that path and remove barriers wherever possible.

Experienced authors benefit from the same attentive service. Whether the goal is launching a debut novel or releasing a follow-up title, Maynard Publishing tailors its book publishing process to fit each writer’s vision and objectives.

How the Process Works

The journey begins with a manuscript evaluation. Maynard Publishing’s team reviews the project, identifies its strengths, and maps out a clear plan forward. Writing or editing follows, shaping the content into a polished, professional form. Design, illustration, and formatting then prepare the book for both print and digital release.

Distribution comes next. The agency’s network places finished books with retailers, online platforms, and targeted audiences. Promotion campaigns launch alongside publication and continue afterward, sustaining momentum and growing readership over time.

For authors ready to take the next step in book publishing, Maynard Publishing’s editing and preparation services are a strong starting point. Those interested in learning more or starting a conversation can reach the team directly.

OECD Warns U.S. Inflation Could Hit 4.2% in 2026 — Far Above the Fed’s 2.7% Estimate

The credibility gap between official Federal Reserve projections and independent institutional forecasts has never been wider. On Thursday, the Organization for Economic Cooperation and Development released its March 2026 interim economic outlook — and what it contained was a direct challenge to the monetary policy assumptions that have been guiding markets since the start of the year.

The OECD forecast all-items inflation in the U.S. at 4.2% for 2026 — a sharp step up from its prior projection of 2.8%, and well above the 2.7% Fed officials estimated when they updated their own forecasts last week. The differential is not a rounding error. It is a 155 basis point spread between what the world’s most widely cited multilateral economic body believes will happen and what the institution charged with managing U.S. price stability is projecting. For investors, fixed income traders, and corporate planners working off Fed guidance, the divergence carries significant operational implications.

Two Drivers, One Very Large Problem

The OECD’s Interim Economic Outlook, titled “Testing Resilience,” identifies the recent major disruption to global energy and commodity markets as the primary catalyst. The halt in shipments through the Strait of Hormuz and the closure and damage of some energy infrastructure has generated a surge in energy prices and disrupted the global supply of energy and other important commodities, including fertilizers. This is raising costs, weighing on demand, and adding to inflationary pressures.

The energy channel is the more acute and immediate force. The OECD’s outlook for U.S. inflation is markedly above that of the Fed and many private sector forecasters, partly because it is expecting a more persistent energy price shock. Brent crude has moved above $108 per barrel this week, with WTI following, and the cost of gasoline in some California markets has crossed $8 per gallon. Supply disruption of this magnitude does not unwind quickly — and the OECD is not assuming it will.

The second driver is the ongoing pass-through impact of U.S. tariffs that, while lower than prior levels, continue to boost prices around the world. The OECD explicitly incorporated both forces into its revised outlook, producing a combined inflation forecast that essentially doubles the pace of price increases relative to where the institution was projecting just three months ago.

“Too Uncertain” — The Fed’s Own Words

The OECD’s report landed exactly one week after the Federal Reserve’s March 18 decision to hold rates steady for the second consecutive meeting. The Fed’s own post-meeting statement acknowledged limited visibility: “Uncertainty about the economic outlook remains elevated. The implications of developments in the Middle East for the U.S. economy are uncertain. The Committee is attentive to the risks to both sides of its dual mandate.”

Fed Chair Jerome Powell reinforced that posture at his press conference. “Near-term measures of inflation expectations have risen in recent weeks, likely reflecting the substantial rise in oil prices caused by the supply disruptions in the Middle East,” he said. “In the near term, higher energy prices will push up overall inflation, but it is too soon to know the scope and duration of the potential effects on the economy.”

The Fed revised its year-end inflation forecast upward to 2.7%, from its prior estimate of 2.4%. It also raised its core inflation estimate to 2.7% from 2.5% — and still projected only one rate cut for all of 2026, consistent with December’s guidance.

The OECD’s 4.2% forecast now represents a scenario in which the Fed’s projections turn out to be significantly understated — not because the central bank is being reckless, but because the energy price shock is more durable, more broad-based, and more structurally embedded in the cost base than the Fed’s March models assumed.

The Fed Pause, Reexamined

Fed policymakers voted 11-1 in favor of leaving rates unchanged at the March meeting, with the lone dissent from Fed Governor Stephen Miran, who preferred a 25 basis point cut. The institutional consensus was firmly in wait-and-see mode — an understandable posture given the acknowledged uncertainty, but one that now looks increasingly inadequate given the scale of the inflation revision coming from Paris.

Most members of the rate-setting FOMC said at last week’s meeting they still expected to cut rates this year, though Fed Chair Powell cautioned that their forecasts were far more uncertain than usual because of the energy shock. The OECD is now effectively saying that any such cuts would be a policy mistake given their baseline projection.

In its baseline forecast, the OECD said it sees the Fed keeping its policy rate flat through 2027, “reflecting rising headline inflation in the near-term, core inflation projected to remain above target through 2027, and solid projected GDP growth.” That is a materially more hawkish path than what either the Fed’s own dot plot or Goldman Sachs’ house view currently contemplates — Goldman still penciling in two normalization cuts, timing dependent on conflict duration.

The Downside Scenario

The 4.2% figure represents the OECD’s baseline. In a “downside scenario,” with oil prices hovering at $135 per barrel in the second quarter, the OECD said global output could be 0.5% weaker than its baseline prediction, while consumer prices would be nearly 1% higher. That implies a plausible scenario in which U.S. headline inflation approaches or exceeds 5% on an annualized basis by mid-year.

The organization also warned that further disruptions to trade in the Persian Gulf could have negative effects on a broader range of products in global supply chains — including the price of urea, one of the main nitrogen-based fertilizers, which has risen by more than 40% since mid-February. Crop yield impacts in 2027 from constrained fertilizer access would represent a second-order inflationary shock arriving well after the energy channel peaks.

One Silver Lining — If the Baseline Holds

The OECD did project that U.S. inflation is likely to recede sharply in 2027, back to 1.6% — actually well below the Fed’s own estimate of 2.2% and less than the central bank’s 2% target. The organization’s projections are explicitly conditional on the technical assumption that the energy market disruption is temporary and that prices begin declining gradually from mid-2026.

U.S. GDP growth is projected to moderate from 2.0% in 2026 to 1.7% in 2027, as strong AI-related investment is gradually offset by a slowdown in real income growth and consumer spending.

For market participants, the operative question is no longer whether the Fed will cut in 2026. It is whether the OECD’s 4.2% inflation track forces a genuine reassessment of the entire rate path — and what that repricing looks like for Treasuries, equities, and corporate credit markets that have been trading on assumptions the OECD just revised by 150 basis points.

Disclaimer: This article is intended for informational purposes only and does not constitute financial, investment, or economic advice. The projections and forecasts referenced in this article are sourced from the Organization for Economic Cooperation and Development (OECD) and the U.S. Federal Reserve and reflect institutional estimates as of the publication date of March 26, 2026. These projections are subject to revision as new economic data becomes available.

All macroeconomic forecasts involve inherent uncertainty and should not be relied upon as predictive indicators of future market conditions, interest rate movements, or asset valuations. Readers are advised to conduct independent research and consult with a qualified financial professional before making any investment, lending, or capital allocation decisions.

MarketDaily does not endorse any specific investment strategy, financial product, or policy position. References to named financial institutions, central banks, and economic organizations are for editorial context only and do not imply endorsement or affiliation. Past economic conditions and policy outcomes are not indicative of future results.

The Comprehensive Self-Publishing Guide with Book Publishing Partner (2026)

Self-publishing has significantly transformed the way authors bring their books to life. What once required approval from traditional publishers can now be done independently, giving writers more control over their work. In 2026, self-publishing is not just an option; it’s becoming one of the more effective ways to share your ideas, build your brand, and potentially generate income.

However, while self-publishing offers increased freedom, it also comes with certain challenges. From writing and editing to publishing and marketing, the process can feel overwhelming, especially for first-time authors. That’s where having the right support system can make a difference. With expert guidance from Book Publishing Partner, authors can navigate the entire journey with greater confidence and clarity.

What Is Self-Publishing and Why Is It So Popular?

Self-publishing allows authors to publish their books without relying on traditional publishing houses. This means you maintain full ownership, creative control, and potentially higher royalty rates. Platforms like Amazon Kindle Direct Publishing (KDP) have made it significantly easier to publish a book and make it available to a global audience.

The rise of self-publishing is driven by several factors:

  • Faster publishing timelines
  • Greater control over content and design
  • Higher earning potential
  • Direct connection with readers

But while the opportunity is exciting, success in self-publishing typically requires more than just uploading a manuscript. It requires a strategic approach, and that’s where many authors find challenges.

Step 1: Start with a Clear Book Idea

Every successful book often begins with a strong idea. Whether you’re writing fiction, nonfiction, or a business book, your concept should be clear and focused. Think about your target audience and what value your book could provide.

Ask yourself:

  • What problem does my book solve?
  • Who is my ideal reader?
  • What makes my book unique?

Having clarity at this stage lays the groundwork for everything that follows. If you’re unsure how to structure your ideas, professional guidance from Book Publishing Partner could help you turn your concept into a well-defined plan.

Step 2: Writing Your Manuscript

Writing a book is one of the most rewarding yet challenging parts of the journey. It requires consistency, discipline, and creativity. Many first-time authors start strong but sometimes lose momentum along the way.

To stay on track:

  • Set realistic writing goals
  • Create a daily or weekly writing schedule
  • Focus on progress, not perfection

If writing feels overwhelming, you’re not alone. This is why many authors turn to ghostwriting services. With the help of Book Publishing Partner, you can collaborate with professional writers who bring your ideas to life while maintaining your voice and vision.

Step 3: Editing and Proofreading

No matter how good your first draft is, editing is essential. A well-edited book tends to improve readability and can build credibility with your audience.

Editing involves:

  • Fixing grammar and spelling errors
  • Improving sentence structure
  • Ensuring consistency in tone and style
  • Strengthening the overall flow of the content

Skipping this step may lead to negative reviews and a less-than-ideal reader experience. Book Publishing Partner offers professional editing and proofreading services to help ensure your manuscript meets industry standards and is ready for publication.

Step 4: Professional Book Design and Formatting

Your book’s appearance matters more than you might think. Readers often judge a book by its cover, and a poorly designed book could reduce your chances of success.

A professional book design includes:

  • An eye-catching cover that reflects your content
  • Proper formatting for print and eBook versions
  • A clean, readable layout

With Book Publishing Partner, authors receive high-quality book cover design and formatting services that help their books stand out in a competitive market.

Step 5: Publishing Your Book

Once your manuscript is ready, the next step is publishing. Self-publishing platforms like Amazon KDP allow authors to publish quickly, but the process involves several technical details.

Key elements include:

  • Choosing the right categories and keywords
  • Writing an SEO-optimized book description
  • Setting the correct pricing strategy
  • Uploading files in the correct format

These details play a significant role in your book’s visibility and success. Book Publishing Partner simplifies this process by handling the technical side of publishing, making sure your book is properly listed and optimized for discoverability.

Step 6: Book Marketing and Promotion

Publishing your book is just the beginning. Without effective marketing, even a great book could go unnoticed. In today’s competitive market, book marketing is essential for reaching your target audience.

Successful marketing strategies include:

  • Optimizing your book for search engines
  • Promoting your book on social media
  • Running paid advertising campaigns
  • Building an email list
  • Creating an author brand

Book Publishing Partner assists authors with strategic book marketing services, helping your book get the visibility it deserves. From promotional campaigns to audience targeting, they provide the tools needed to improve sales and engagement.

Step 7: Building Your Author Brand

In 2026, being an author is about more than just writing books; it’s about building a brand. Readers want to connect with authors, follow their journey, and engage with their content.

To build a strong author brand:

  • Create a professional online presence
  • Share valuable content related to your book
  • Engage with your audience regularly
  • Stay consistent with your messaging

A strong brand not only helps you sell more books but also opens up doors to new opportunities such as speaking engagements and collaborations.

Summary

Self-publishing in 2026 offers exciting opportunities for authors to share their stories, build their brand, and generate income. However, success requires more than just writing a book; it requires careful planning, professional execution, and effective marketing.

With the right support from Book Publishing Partner, the journey can be much easier and more rewarding. From idea to publication and beyond, they provide the expertise needed to help turn your vision into a successful book.

If you’ve been thinking about publishing your book, now might be the perfect time to take action. With the right strategy and the right partner, your book has the potential to reach readers around the world and make a lasting impact.

S&P 500 Rallies on Peace Talks — But Recession Probability Hits 48.6%, Moody’s Warns

Stocks jumped Wednesday as oil prices pulled back and traders weighed the possibility of a diplomatic resolution to the energy shock that has rattled markets for the better part of a month. The Dow Jones Industrial Average gained 305.43 points, or 0.66%, closing at 46,429.49. The S&P 500 rose 0.54% to 6,591.90, and the Nasdaq Composite advanced 0.77% to end at 21,929.83.

The S&P 500 advanced for a second consecutive session this week as diplomatic signals raised cautious hopes for a reduction in energy market disruptions. Brent crude settled around $102 a barrel. Treasuries pared their March losses. Gold climbed.

Wednesday’s session was, by any conventional measure, a good day for equities. But experienced portfolio managers know to read the tape carefully when relief rallies arrive in the middle of deteriorating fundamentals. The index gains are real. So is everything building beneath them.

Recession Probability Is No Longer a Tail Risk — It Is the Central Debate

For much of the past two years, recession probability models operated in a band near or below the 20% baseline that economists treat as ambient risk in any given 12-month window. That baseline has now been surpassed — significantly — across every major institutional forecast on Wall Street.

Moody’s Analytics has raised its recession outlook for the next 12 months to 48.6%. Goldman Sachs has boosted its estimate to 30%. Wilmington Trust puts the probability at 45%, while EY Parthenon has it at 40%, with the explicit caveat that “those odds could rapidly rise” if the energy shock proves more severe or prolonged. In normal times, the base probability for recession in any given 12-month span is around 20%.

Goldman raised its headline PCE inflation forecast by 0.2 percentage points to 3.1% by December 2026 and nudged its full-year GDP growth estimate down to 2.1%. The bank raised its recession probability by 5 percentage points to 30% while stressing that a recession is still not its base case. The spread between Goldman’s 30% and Moody’s 48.6% is itself a data point — it reflects how wide the range of outcomes has become, and how much of the resolution hinges on variables that remain entirely outside the market’s control.

The Labor Market Was Already Showing Stress Before the Energy Shock Arrived

The equity market’s vulnerability right now is not simply a function of elevated commodity costs. It is a function of those costs landing on an economy that entered 2026 with meaningful structural weakness already in place.

The U.S. economy created just 116,000 jobs for all of 2025 and lost 92,000 in February. While the unemployment rate has held steady at 4.4%, that stability is largely the product of a dearth of firing rather than a burst in hiring. Outside of healthcare, the labor market lost hundreds of thousands of jobs last year. GDP is on track to grow at a 2% pace in the first quarter, according to the Atlanta Fed’s GDPNow tracker — coming off an increase of just 0.7% in Q4 2025.

Consumer sentiment is tracking the deterioration. A NerdWallet survey published this month showed 65% of respondents expect a recession in the next 12 months, up 6 percentage points from the prior month. Consumer spending accounts for more than two-thirds of U.S. economic output. When nearly two-thirds of consumers are bracing for contraction, that psychology — independent of the underlying data — becomes a self-reinforcing headwind.

The information technology sector sits 12% below its recent high as investors question the sustainability of AI infrastructure spending under tighter financial conditions. The consumer discretionary sector is also 12% below its high. The financial sector sits 12% below its high as the private credit market shows signs of stress, with delinquency rates on U.S. loans reaching their highest level since 2017 in Q4 2025.

The Fed Is Caught — and the Rate Cut Consensus Has Nearly Inverted

The Federal Reserve held its benchmark federal funds rate at 3.50%–3.75% at its March meeting, a decision widely anticipated by markets. But the rate expectations picture that has emerged since that decision — and accelerated through this week — represents one of the most dramatic reversals in the current cycle.

Odds of a Fed rate cut this year fell from 95% a month ago to around 9% as of Wednesday morning, according to the CME FedWatch Tool. Futures trading now prices in nearly 17% odds of at least one rate hike at some point in 2026. There is even an 8% probability that the Fed could hike at its April meeting

What makes this moment particularly difficult for policymakers is the nature of the shock itself. Normally, the Fed faces demand-side shocks — where GDP and inflation tend to move in the same direction, giving the central bank a clear mandate response. A supply-side shock does the opposite: it weakens GDP growth while pushing inflation higher, putting both prongs of the Fed’s dual mandate in direct conflict. That is the bind the Fed is navigating right now.

Headline PCE remains at 2.8% with core PCE at 3.0%, both still above the Fed’s 2% longer-run target. The Fed now expects real GDP to grow 2.4% in 2026 and 2.3% in 2027. Pricing reflects roughly a 10% chance of a rate hike across key mid-2026 meetings. The reflexive “buy the dip” behavior that defined equity markets through 2023, 2024, and much of 2025 was conditioned by the expectation that the Fed would cut rates when conditions deteriorated. That assumption no longer holds.

Oil Is the Swing Variable — and the Market Knows It

Everything in the current macro environment traces back to one number: the price of Brent crude. Every major variable in play — inflation, Fed policy, consumer spending, corporate margins, and recessionary probability — runs through energy costs, and every intraday market move this week has been driven first and foremost by where oil settles.

Prices at the pump have risen by $1.02 per gallon over the past month, an increase of 35%, according to AAA. “The negative consequences of higher oil prices happen first and fast,” said Mark Zandi, chief economist at Moody’s Analytics. “If oil prices stay kind of where they are through Memorial Day — certainly through the end of the second quarter — that’ll push us into recession.”

The outcome hinges heavily on a single variable: how long energy market disruptions last. A swift normalization would allow oil risk premiums to fade and limit economic damage to a few tenths of a percentage point of GDP growth. A prolonged disruption, by contrast, would entrench energy costs, crimp consumer spending, and force the Fed into an increasingly uncomfortable corner.

The CBOE Volatility Index closed Wednesday at 26.95 — down from above 29 earlier in March, but still well above the low-teens readings that characterized the pre-shock environment. A VIX above 29 has historically correlated with larger-than-average S&P 500 moves over the following 12 months, in both directions. Wall Street estimates the S&P 500 could advance 27% in the next year if conditions normalize — but in a recessionary scenario, history says the index would fall sharply.

What Comes Next

The S&P 500 has now closed below its 200-day moving average of 6,624 three times in a row — the first time since last May it has sustained that level. The Nasdaq Composite has not come close to its own 200-day moving average of 22,261. Sustained closes above these levels would be needed to reassure technical traders that the relief rally has structural backing.

The forward calendar for market-moving data is tight. February durable goods orders are due Thursday. The next PCE inflation print will capture the earliest measurable passthrough of the energy shock into consumer prices. Weekly jobless claims will continue to serve as the most real-time read on labor market health. And the April FOMC meeting — technically Chairman Powell’s last scheduled meeting before his term expires in May, with nominee Kevin Warsh’s Senate confirmation still pending — adds a layer of policy uncertainty that few market cycles in recent memory have had to absorb simultaneously.

The S&P 500 is on track for its worst month since March 2025, down roughly 4.3% in March as of recent trading. The Shiller P/E ratio currently stands near 37.5, well above the 21.3 average at the onset of prior double-digit decline years, leaving limited margin for error. Investors should note that all three of DataTrek’s historically identified drivers of bad market years are currently present: recession risk, an energy shock, and the possibility of an unexpected Fed policy shift.

Wednesday’s equity gains are a legitimate data point. So is a 48.6% recession probability from Moody’s, a VIX above 26, an S&P 500 below its 200-day moving average, a Fed with almost no room to cut, and a labor market that has not generated meaningful job growth in over a year. Markets are not pricing a crisis today. They are pricing a test. The data will determine which scenario wins.

DISCLAIMER: This article is intended for informational and analytical purposes only and does not constitute financial, investment, or trading advice. All market data, economic projections, and institutional forecasts cited herein reflect publicly available information as of March 25, 2026, and are subject to change without notice. Recession probability estimates, analyst price targets, and forward-looking statements involve inherent uncertainty and should not be relied upon as predictive of future market performance. References to energy market disruptions are included solely to provide macroeconomic context for their documented impact on financial indicators — they do not represent editorial commentary on political or foreign policy matters. Readers are encouraged to consult a qualified financial advisor before making any investment decisions. MarketDaily does not hold positions in any securities mentioned in this article.

Markets and Geopolitical Risk: Economic Transmission and Historical Context

By: Kip Lytel, CFA & Loveth Abu   |  Montecito Capital Management

1. Markets vs. Geopolitical Shocks

Geopolitical events can introduce short-term volatility in financial markets due to uncertainty. However, the long-term market impact depends on whether such events materially affect underlying economic drivers such as energy supply, trade flows, or monetary policy.

Historically, financial markets have tended to absorb geopolitical disruptions relatively quickly. Market declines associated with global conflicts have often been temporary unless accompanied by sustained economic disruption. 

More significant and prolonged declines have historically been associated with structural economic disruptions, such as the 1973 Oil Embargo, where sustained inflation and tighter monetary policy contributed to deeper market corrections.

2. Energy as a Transmission Channel

Energy markets play a key role in transmitting geopolitical risk into the broader economy. Oil prices can respond quickly to perceived supply risks, affecting inflation, transportation costs, and production expenses across industries.

Historically, oil price increases into the $100–$120 per barrel range have been manageable for the global economy. Sustained increases beyond that level have been associated with higher inflationary pressure and increased recession risk.

Strategic petroleum reserves and global supply adjustments have, in past instances, helped mitigate short-term supply disruptions, though they are not a long-term substitute for stable production.

3. Inflation and Consumer Impact

According to U.S. Bureau of Labor Statistics CPI weightings, energy comprises roughly 6–8% of the overall index, while gasoline accounts for approximately 3–4% of the consumer basket (U.S. Bureau of Labor Statistics). However, its broader impact is more significant due to its role as an input cost across transportation, manufacturing, and agriculture.

Short-term increases in energy prices tend to create temporary inflation volatility. Sustained price increases, however, may lead businesses to adjust pricing and contracts, contributing to broader inflation trends and influencing central bank policy decisions.

4. Shipping and Global Trade Dynamics

Global trade systems can be affected by increased uncertainty, even without direct disruptions. Factors such as higher insurance costs, logistical delays, and rerouting of shipping lanes can increase operational costs.

Historically, these conditions have led to elevated freight rates and longer supply chains. Industries such as airlines, logistics, and manufacturing have been more sensitive to such cost pressures.

5. Corporate Earnings and Equity Markets

Changes in energy costs and trade conditions can have uneven effects across sectors. Energy and commodity-linked industries have historically benefited from higher prices, while sectors such as transportation, chemicals, and consumer goods may experience margin pressure.

Equity markets typically adjust to uncertainty through changes in valuation rather than immediate declines in earnings. If economic impacts are short-lived, earnings effects may remain limited. Prolonged cost pressures, however, have historically contributed to slower growth and broader market volatility.

6. Historical Patterns in Market Behavior

Across major geopolitical events since World War II, equity markets have often followed a consistent pattern:

  • Initial decline
  • Stabilization as uncertainty reduces
  • Recovery as economic conditions become clearer

Historical data suggest that bull markets have followed initial geopolitical shocks in approximately 70–80% of cases, particularly when broader economic conditions remain stable.

7. Market Recovery Trends

Market recoveries following geopolitical disruptions have often occurred faster than anticipated. Over the past several decades, equity markets have demonstrated resilience following geopolitical shocks. Historical data shows that the S&P 500 has been higher one year after the onset of armed conflict roughly 70% of the time. (Forbes)

In many instances, market stabilization has occurred before full resolution of the underlying event, reflecting the forward-looking nature of financial markets.

8. Portfolio Strategy Considerations

Periods of uncertainty highlight the importance of diversified, multi-asset portfolio construction. Approaches that combine global equities, alternative assets, and risk management strategies can help mitigate volatility.

At Montecito Capital Management, portfolio construction is centered on building resilient, “all-weather” strategies designed to navigate varying market environments. This includes diversification across asset classes, selective use of alternative investments, and disciplined risk management frameworks aimed at balancing participation in market growth with downside protection.

More broadly, diversification across sectors and geographies, along with a long-term investment perspective, has historically supported portfolio resilience during periods of market disruption.

Final Thought: Markets and Uncertainty

Financial markets tend to respond more to economic disruption than to geopolitical events themselves. Historical evidence suggests that sustained impacts are most closely tied to changes in inflation, supply chains, and monetary policy.

For investors, maintaining a structured and diversified approach has been a key factor in navigating periods of uncertainty while remaining positioned for long-term opportunities.


Disclaimer: This material is for informational and educational purposes only and does not constitute investment advice, a solicitation, or an offer to buy or sell any security. Past performance is not indicative of future results. The views expressed are subject to change without notice. All investing involves risk, including the possible loss of principal. Investors should consult with a qualified financial professional before making any investment decisions.