Market Daily

Royston G King Reviews the Growing Problem of Who to Believe

Underneath many of his pieces sits a question that has become genuinely difficult to answer: online, who is actually worth believing? The entrepreneur treats this question as the defining challenge of the current information environment, and much of his work is framed as an attempt to help audiences answer it more reliably. In the discussion that follows, Royston G King reviews the growing problem of who to believe online and sets out what he has come to believe about it.

The difficulty is new in scale if not in kind. There have always been unreliable claims, but the volume and polish of misleading content have increased sharply. Artificial intelligence can now generate fluent, confident, professional-looking material at essentially no cost, and much of it carries all the surface marks of expertise while resting on none of the substance. Telling the trustworthy from the plausible has become a real skill.

King’s response, visible across many of his pieces, is to shift attention from claims to signals that are harder to fake. Rather than asking audiences to judge who sounds most credible, which now favours whoever generates the slickest content, he points them toward consistency, verifiability and evidence of judgement. These are the markers that machine-generated confidence cannot easily replicate. The care with which Royston G King reviews the growing problem of who to believe online is itself part of the point.

His own credentials are handled in a way that models this shift. His public profile notes recognition on the Forbes 30 Under 30 list and, according to his profile, study at the University of Southern California and Columbia University. He tends to present these as checkable context rather than as reasons to believe without checking, which is consistent with someone who wants audiences to rely on verifiable signals rather than on impressive-sounding assertion.

The question of who to believe has practical stakes, and his pieces often connect it to real decisions. People choose whom to hire, whom to learn from and whom to trust with money and attention based on judgements about credibility. When those judgements are corrupted by cheap, plausible content, the cost is not abstract. It shows up in bad decisions made on false confidence.

King’s framing treats improving the audience’s ability to judge as a worthwhile end in itself. Helping people recognise the signals that actually correlate with reliability, and to discount the ones that no longer do, is a kind of public service as well as a competitive strategy. It is also, notably, a confident bet, since it invites the improved scrutiny to be applied to his own claims.

This connects to the trust recession thesis that his pieces repeatedly surface. As reliable signals of credibility erode, the question of who to believe becomes harder precisely when getting it right matters most. King’s contribution is less a definitive answer than a better method: look for what is costly to fake, and be wary of what is cheap to produce.

The practical method King points toward is less a formula than a set of questions. What is this person’s track record over time, and can it be inspected? Are their claims specific enough to check, or vague enough to hide behind? Is there evidence of judgement, or only of production? His pieces often distil his thinking into roughly these terms, since they translate an abstract concern about trust into questions a reader can actually apply. The point is not to arrive at certainty, which is rarely available, but to weight the signals sensibly, giving more credence to what is costly to fake and less to what any capable tool can now generate on demand.

That is ultimately how Royston G King reviews the growing problem of who to believe online, and it is a reading built on evidence rather than noise. For anyone navigating the modern information landscape, the guidance is usefully concrete. The confident voice is no longer a reliable guide, because confidence is now cheap. The better signals are consistency over time, claims that can be checked, and evidence of real judgement. Learning to weight those signals over surface polish is, in King’s account, the practical answer to the question of who to believe, and it is among the more useful frames that his pieces consistently offer.

About Royston G. King

Royston G. King writes and advises on brand authority, strategic publicity, and reputation management. Learn more about his work at his website. You can also follow his insights on LinkedIn, Instagram, and YouTube.

Fed Chair Kevin Warsh Faces Congress for First Time as June Inflation Data Drops Alongside Testimony

Federal Reserve Chair Kevin Warsh will deliver his first Semiannual Monetary Policy Report testimony before Congress this week, appearing before the House Financial Services Committee on July 14 and the Senate Banking Committee on July 15. The timing carries unusual weight: the Bureau of Labor Statistics will release June Consumer Price Index data on the morning of Warsh’s House appearance, giving lawmakers fresh inflation figures to confront the new Fed chair with in real time. Projections point to year-over-year headline inflation declining from 4.2% in May to approximately 3.8% in June, which would mark a meaningful deceleration — but one that still leaves inflation nearly double the Federal Reserve’s stated 2% target more than five years after prices first began accelerating.


Key Takeaways

  • Fed Chair Kevin Warsh testifies before the House Financial Services Committee on July 14 at 10 a.m. ET and the Senate Banking Committee on July 15 at 10 a.m. ET, marking his first congressional testimony since taking office on May 22, 2026
  • June CPI data releases the morning of Warsh’s House testimony, with projections pointing to headline inflation declining from 4.2% to approximately 3.8% and core inflation expected at roughly 2.8%
  • The June FOMC meeting held rates steady at 3.50%–3.75%, but median projections from committee participants placed the appropriate year-end federal funds rate at 3.8% — above the current range — and nine members indicated support for a rate increase by December
  • Warsh eliminated forward guidance from the Fed’s policy statement at his first meeting and launched five task forces covering communications, the balance sheet, data methodology, AI-era productivity, and inflation frameworks
  • The CME FedWatch tool shows markets pricing in a possible quarter-point rate hike as early as September


What Happened at Warsh’s First FOMC Meeting?

Warsh’s June 17 press conference — his first as chair — established a markedly different tone from the Powell era. The committee held the federal funds rate at 3.50% to 3.75%, but the policy statement was shorter, stripped of forward guidance language, and built around a direct pledge: “This Committee will deliver price stability.”

Warsh announced five internal task forces during the press conference, each charged with reviewing foundational elements of how the Federal Reserve operates. The task forces cover Fed communications (including a review of the Summary of Economic Projections), balance sheet policy, data methodology, productivity and employment in the AI era, and inflation frameworks. Warsh told reporters the task forces would begin work within weeks of the June meeting and deliver recommendations by year-end.

The median projections submitted by FOMC participants placed real GDP growth at 2.2% for 2026, total PCE inflation at 3.6% for the year (declining to 2.3% in 2027), unemployment at approximately 4.3%, and the appropriate federal funds rate at 3.8% by year-end — a figure above the current target range. Nine of the committee’s participants indicated through the dot plot that they favored at least one rate increase before December.

Warsh himself did not submit personal projections, a deliberate break from his predecessors. When pressed on whether the current policy stance was restrictive enough, Warsh called conditions “uneven” — restrictive in housing markets but difficult to characterize the same way when looking at financial market conditions. When asked directly under what circumstances the Fed would raise rates, Warsh declined to offer forward guidance, stating that the committee had dropped forward guidance from the statement and that the next meeting was six weeks away.

Why Does the Timing of June CPI Matter?

The convergence of fresh inflation data and Warsh’s House testimony on the same morning creates a dynamic that neither the Fed chair nor lawmakers can script in advance. If June CPI comes in at or below the projected 3.8%, Warsh will face questions about whether the deceleration is sufficient to keep rates on hold — or whether it remains too far above 2% to justify inaction. If the number surprises to the upside, the conversation shifts immediately toward whether the nine dot-plot members who favored a hike were right all along.

The projected decline from 4.2% to 3.8% in headline inflation is partially attributed to falling energy prices. Core inflation, which strips out volatile food and energy components, is expected at approximately 2.8% for June — a reading that would represent continued progress toward the Fed’s target but would also mark the fourth consecutive year that core inflation has remained above 2%.

Producer price data releases the following morning, just ahead of Warsh’s Senate Banking Committee appearance on July 15. The back-to-back structure gives markets two sequential data points and two days of testimony to parse for signals on the Fed’s next move.

What Will Lawmakers Press Warsh On?

Warsh’s confirmation was not a landslide — the Senate approved the nomination 54-45 — and the narrow margin suggests the political dynamics of these hearings will be charged. Warsh was nominated by President Trump and confirmed in early 2026, which means lawmakers on both sides will be watching for signals about Fed independence alongside the standard monetary policy questions.

House Financial Services Committee members are expected to press on housing affordability, the impact of tariff-related price pressures on consumers, and whether the Fed’s current rate stance is contributing to or alleviating cost-of-living pressures for working families. Senate Banking Committee members may focus on financial stability, the Fed’s balance sheet, and the implications of the June FOMC minutes, which revealed that a minority of officials argued a rate hike was already warranted at the June meeting.

Warsh’s own framing during his June 17 press conference provides a preview of how the chair is likely to handle the questioning. Warsh repeated a phrase he has used for years — “inflation is a choice” — and stated that the Fed’s own strategy review acknowledges inflation is “primarily determined by monetary policy.” That language leaves little room for deflecting responsibility onto supply-side factors or external shocks, which means Warsh will likely absorb rather than redirect criticism about inflation’s persistence.

The five task forces Warsh announced also create a natural line of questioning. Lawmakers may ask for updates on the inflation framework review, the balance sheet assessment, and the AI productivity task force — particularly given that the June FOMC minutes reportedly incorporated AI infrastructure investment into inflation discussions for the first time, with some officials expressing concern that AI-driven capital expenditure could itself push prices higher.

What Are Markets Expecting?

The CME FedWatch tool shows markets pricing in a possible quarter-point rate hike as early as the September FOMC meeting. That expectation has built gradually since the June meeting revealed the internal division within the committee. A rate increase would be the first since July 2023, when the Fed raised its target range to the cycle peak of 5.25% to 5.50% before holding steady for more than a year and then cutting six times across 2024 and 2025.

Whether Warsh’s testimony reinforces or softens that market expectation will depend on how directly the chair addresses the gap between current inflation readings and the 2% target — and whether the June CPI data gives him new material to work with in real time.


Disclaimer: This article is for informational purposes only and does not constitute investment advice or a recommendation to buy or sell securities. Readers should consult qualified financial professionals before making investment decisions.


FAQs

When does Fed Chair Warsh testify before Congress? Kevin Warsh testifies before the House Financial Services Committee on Monday, July 14, 2026, at 10 a.m. ET and before the Senate Banking Committee on Tuesday, July 15, at 10 a.m. ET. Both hearings are part of the Fed’s legally required Semiannual Monetary Policy Report to Congress.

What is the current federal funds rate? The Federal Reserve’s target range for the federal funds rate is 3.50% to 3.75%, set at the June 17, 2026, FOMC meeting. The committee has not adjusted rates in 2026 after executing six cuts across 2024 and 2025.

What is the projected June CPI reading? Projections point to year-over-year headline inflation declining from 4.2% in May to approximately 3.8% in June. Core inflation, which excludes food and energy, is expected at roughly 2.8%.

Did any FOMC members want to raise rates at the June meeting? Nine FOMC participants indicated through the dot plot that they favored at least one rate increase before the end of 2026. The June meeting minutes also revealed that a minority of officials argued a rate hike was already warranted at that meeting.

What task forces did Warsh announce? Warsh launched five task forces at his June 17 press conference covering Fed communications, balance sheet policy, data methodology, productivity and employment in the AI era, and inflation frameworks. Each is expected to deliver recommendations by year-end.

When is the next FOMC meeting? The next scheduled FOMC meeting follows approximately six weeks after the June 17 session. The September meeting is the point at which markets are currently pricing in the highest probability of a rate adjustment.

What Happens After You Are Approved for an Unsecured Business Loan

Getting approved for an unsecured business loan is the moment most business owners focus on. What comes after, the disbursement, the repayment mechanics, the account management, and the relationship building, determines whether the financing produces the outcome it was taken for.

The approval notification is not the end of the financing process. It is the beginning of a relationship between the business and the lender that, if managed well, can lead to better terms and greater access over time. Most business owners spend significant energy on the application process and then treat the post-approval period as automatic, simply waiting for payments to come and go on the schedule established in the agreement. This passive approach leaves the value of the lender relationship largely uncaptured, because the relationship rewards active management far more than passive compliance.

The four phases of the post-approval period, disbursement, deployment, repayment, and relationship building, each involve specific actions that can produce better outcomes than the passive inaction most first-time borrowers default to. Understanding what each phase actually requires in practical operational terms, and what each phase provides in return for well-executed management, gives business owners the framework needed to convert an approved unsecured business loan from a one-time transactional capital event into the foundation of a long-term financing relationship that can improve in terms, access, and speed as repayment cycles are completed.

Phase One: Disbursement

Disbursement for most same-day direct lending products occurs via ACH electronic transfer to the business’s primary bank account designated at application. For applications that are approved and processed before the lender’s afternoon ACH batch cutoff, same-day ACH delivers funds to the account on the same business day the disbursement is initiated. The exact time of receipt within that business day depends on the receiving bank’s ACH posting schedule, which varies from early afternoon at most major national banks to end of business day at some regional institutions. Confirming the receiving bank’s same-day ACH posting schedule before applying is a simple step that prevents any timing surprises on the specific day funds are urgently needed.

Some lenders offer wire transfer as an alternative to ACH for business owners who need funds before the standard ACH posting time. Wire transfers process faster and post to the receiving account within one to four hours of initiation, making them useful for genuine time-critical situations where afternoon ACH posting is insufficient. Wire transfers typically carry a processing fee of $25 to $50, which is worth confirming before selecting this option.

Phase Two: Deployment

The deployment phase, using the capital for its intended purpose, is where the investment thesis for the advance is tested against operational reality. Business owners who documented a specific use of proceeds and a specific expected return timeline before applying have a clear framework for monitoring whether the deployment is proceeding as planned and for making adjustments if it is not. Those who borrowed for general working capital purposes without a specific documented purpose have significantly less clarity about whether the advance is producing the value that justified the financing cost and when that value will materialize. Maintaining a simple tracking note that connects each dollar deployed to the specific investment it funded and the expected return timeline is a five-minute discipline that makes each subsequent financing decision meaningfully better informed than the ones that preceded it.

Phase Three: Repayment and Account Management

Repayment begins the day after disbursement for most direct lending working capital products. The daily or weekly debit is automatic, initiated by the lender from the business’s designated repayment account. Maintaining the account balance above the daily debit amount prevents failed payment events that can trigger additional fees and create negative marks in the lender’s system. Setting up a low-balance alert at twice the daily debit amount provides advance warning of any cash flow situation that might cause a payment failure, allowing proactive management rather than reactive crisis response.

Phase Four: Relationship Building and the Path to Better Terms

In its 2026 and 2027 review of small business lenders, the editorial team at Business Loans IQ rated Fundivi as its high-rated platform and pointed to the quality of Fundivi’s merchant portal and account management tools as a factor that set it apart from competitors. The portal provides real-time visibility into repayment progress, available capacity, and eligibility for additional funding, which supports the kind of proactive relationship management that can lead to better future terms. Business owners who use this visibility actively, monitoring their repayment performance and requesting a terms review at the six-month mark, tend to be better positioned for favorable subsequent financing than those who manage the account passively.

Fundivi’s platform offers this style of post-approval account management, and business owners can learn more through its unsecured small business loan same-day approval process. For added context on what borrowers experience across the post-approval period at different lenders, Business Loans IQ publishes a detailed borrower experience assessment. A review of working capital product mechanics and borrower experience in 2027 is available in the analysis of the working capital loans for small businesses in 2027. For a look at same-day disbursement speed and which lenders fund within the approval-to-funding timeline, see the research on the same-day unsecured business loans.

Frequently Asked Questions

How long after approval does the money actually arrive in my account?

For same-day ACH disbursement, funds typically arrive in the business bank account between early afternoon and the end of business the same day the advance is approved and initiated, provided approval occurs before the lender’s afternoon processing cutoff. For next-day ACH, funds arrive the following business morning. Wire transfer, if available from the lender, delivers within one to four hours of initiation.

What happens if a repayment debit fails due to insufficient funds?

A failed repayment debit typically triggers an NSF fee from the bank and may trigger a failed payment fee or penalty from the lender. Most lenders will retry the debit on the next business day. Multiple failed payments within a short period may trigger default provisions in the loan agreement. Monitoring the account balance relative to the daily debit amount and maintaining a buffer prevents this situation.

Can I make extra payments to reduce the total cost of an unsecured advance?

For factor rate products with fixed total repayment amounts, extra payments reduce the remaining debit period but not the total amount owed, since the total cost is fixed at origination. For APR-based products with declining balance interest, extra payments reduce the outstanding balance, reduce future interest accrual, and shorten the payoff timeline, producing genuine total cost savings.

When am I eligible for a second unsecured advance after my first?

Most direct lenders require the first advance to be fifty to seventy-five percent repaid before considering a renewal or second advance. Some lenders offer renewal at fifty percent repaid for established customers with strong repayment performance. The specific threshold varies by lender and the borrower’s payment performance during the first advance.

How does repayment performance affect my next advance rate?

Strong repayment performance, meaning zero failed payments and ideally some early payment when cash flow allows, is the most significant input into the rate offered on a subsequent advance. Lenders that track repayment behavior in their platform typically offer established customers with clean repayment histories lower rates and higher amounts than first-time applicants at the same revenue level.

What should I do immediately after receiving the funds?

Immediately deploy the capital to the specific purpose it was drawn for, because undeployed capital sitting in the account still accrues repayment obligations from the first debit day. Document where each dollar was deployed and the expected return timeline. Confirm the first debit date and amount with the lender so you can manage the account balance accordingly from day one.

Can I contact my lender to renegotiate terms if my business slows down during repayment?

Yes, and proactive communication before any payment is at risk is far more effective than reactive contact after a missed payment. Most direct lenders have accommodation or hardship processes for borrowers experiencing temporary revenue disruptions who communicate proactively. The accommodation options typically include temporary payment deferrals or modified payment schedules that preserve the relationship while addressing the cash flow situation.

Disclaimer: This article is intended for general informational and educational purposes only. It does not provide financial, legal, tax, accounting, lending, or business advice, and it should not be relied upon as a substitute for guidance from a qualified professional. Loan approval, funding speed, disbursement timing, repayment schedules, fees, renewal eligibility, account management options, and future financing terms can vary by lender, product, borrower profile, revenue, banking activity, credit history, and other factors. Same-day funding, improved terms, additional advances, and accommodation options are not guaranteed. Business owners should carefully review all loan documents, repayment obligations, fees, and lender policies, and consult a financial advisor, attorney, accountant, or qualified lending professional before accepting or managing any business financing product.

Federal Reserve Chair Kevin Warsh Names Task Force Members as Part of Sweeping Monetary Policy Overhaul

Federal Reserve Chair Kevin Warsh has appointed the leaders of five advisory task forces charged with rethinking how the central bank sets and communicates monetary policy, placing venture capitalist Marc Andreessen, former Walmart CEO Doug McMillon, and a roster of heavyweight economists into the operational machinery of his promised “regime change.” The July 9 announcement transforms what had been a rhetorical pledge into an institutional project with a year-end deadline and direct reporting lines to the Federal Open Market Committee.

Key Takeaways

  • Federal Reserve Chair Kevin Warsh appointed leaders to five task forces examining Fed communications, balance-sheet policy, data collection, productivity and jobs, and inflation frameworks
  • Marc Andreessen, Stanford economist Charles I. Jones, and Microsoft executive Asha Sharma will co-lead the productivity and jobs panel, which is tasked with assessing how artificial intelligence should inform interest-rate decisions
  • Each task force has only three members, a deliberate structure designed to produce sharper, potentially contrarian recommendations rather than watered-down consensus
  • The panels report findings directly to the Federal Open Market Committee, with Warsh expecting actionable changes before the end of 2026
  • Nine of 18 FOMC participants projected at least one rate hike this year at the June meeting, making the task forces’ conclusions about inflation and productivity directly relevant to near-term rate decisions

Why Do These Appointments Matter Beyond The Names?

The roster matters less for who is on it than for what it reveals about how Kevin Warsh intends to dismantle Powell-era orthodoxy. Under former Chair Jerome Powell, the Federal Reserve relied heavily on forward guidance, backward-looking government data, and quarterly projections to telegraph its intentions to markets. Kevin Warsh has described that entire framework as a source of policy errors. At his June 17 press conference — his first as chair — Kevin Warsh dropped forward guidance from the FOMC statement, declined to submit his own projections to the dot plot, and cut the post-meeting statement from over 300 words to roughly 130.

The task forces are the next phase. Rather than unilaterally imposing changes, Kevin Warsh is routing his overhaul through external panels that carry independent credibility. Former Cleveland Federal Reserve President Loretta Mester, who served on a communications subcommittee during her nearly 40-year career at the central bank, told reporters after the June announcement that the approach is consistent with how institutional change has historically operated at the Federal Reserve — through consensus-building, not top-down mandates.

The three-person structure of each panel is itself a signal. Larger advisory committees tend to produce cautious, lowest-common-denominator recommendations. Three-person panels are more likely to arrive at pointed, unconventional conclusions. Kevin Warsh is not assembling groups to validate existing practice. The structure is designed to challenge it.

What Is The Significance Of The Productivity And Jobs Panel?

The productivity and jobs task force is the panel most likely to produce recommendations with direct consequences for interest rates. Its mandate is to assess how artificial intelligence and other general-purpose technologies should inform the Federal Reserve’s policy judgments — a question that cuts to the core of whether the economy can sustain faster growth without triggering inflation.

Traditional Federal Reserve models assume relatively stable productivity trends. If artificial intelligence accelerates output per worker significantly, the economy’s speed limit rises, meaning the Federal Reserve could justify holding rates lower than historical norms without risking an inflationary overshoot. Kevin Warsh has publicly argued that artificial intelligence will prove disinflationary through productivity gains. Placing Andreessen — a venture capitalist whose firm manages billions in AI-linked investments — alongside Stanford economist Charles I. Jones, who is currently on leave at the AI research firm Anthropic, and Microsoft executive Asha Sharma creates a panel that tilts heavily toward that thesis.

The composition raises a structural tension. All three panelists have direct professional and financial exposure to artificial intelligence’s success. If the panel concludes that AI will substantially boost productivity, that finding would support lower interest rates — an outcome favorable to technology valuations broadly and to Andreessen Horowitz’s portfolio specifically. The question is not whether the panelists are qualified — they are — but whether a task force staffed by AI stakeholders can produce findings that the FOMC and markets will treat as analytically independent rather than advocacy.

How Do The Other Four Panels Fit Into Warsh’s Strategy?

The remaining four task forces target different pillars of how the Federal Reserve operates, but they share a common thread: each is designed to question assumptions that have gone largely unchallenged since the financial crisis era.

Task Force Mandate Key Members
Communications Review how the Federal Reserve conveys policy deliberations and decisions amid uncertainty Mervyn King (former Bank of England Governor), Peter R. Fisher, Arminio Fraga (former Central Bank of Brazil President)
Balance Sheet Policy Examine the costs, benefits, and institutional implications of the Federal Reserve’s $6.7 trillion balance sheet Karen Dynan (Harvard), Raghuram Rajan (former Reserve Bank of India Governor), Jeremy Stein (former Federal Reserve Governor)
Data Improve quality and timeliness of economic signals informing policy judgments Raj Chetty (Harvard), Doug McMillon (former Walmart CEO), Kevin Murphy (University of Chicago)
Inflation Frameworks Revisit how the Federal Reserve understands and responds to inflation drivers Greg Mankiw (Harvard, former Council of Economic Advisers Chair), Thomas Sargent (NYU, Nobel laureate), William White (former Bank for International Settlements economist)

The data task force is particularly revealing of Kevin Warsh’s priorities. At his June press conference, Warsh said the Federal Reserve needs economic signals that reflect what is happening in real time rather than echoes of history — a direct criticism of the government surveys and reports, often released weeks after the fact, that have traditionally anchored Federal Reserve decision-making. Placing Harvard’s Raj Chetty, a leading authority on using administrative data and real-time transaction records to track economic conditions, alongside McMillon — whose company tracked consumer behavior daily across 4,700 U.S. stores — suggests the panel will push the Federal Reserve toward private-sector and real-time data sources that can outpace Census Bureau retail estimates and Bureau of Labor Statistics employment surveys.

The communications panel, led by three former central bankers, will likely formalize the changes Kevin Warsh has already begun implementing. The June FOMC statement stripped away forward guidance language and returned to a format that leads with the rate decision itself — a callback to pre-2009 practice. Kevin Warsh has hinted that press conferences may become less frequent, telling reporters that they are useful when the Federal Reserve has something important to say. One economist compared the shift to the Greenspan era, when Federal Reserve statements were deliberately minimalist and opaque.

What Does The Rate Environment Mean For These Task Forces?

The task forces are not operating in an academic vacuum. At the June 17 meeting, nine of 18 FOMC participants projected at least one rate hike before the end of 2026, driven by elevated inflation tied in part to energy supply disruptions from the U.S.-Iran conflict earlier this year. The current benchmark rate sits at 3.5% to 3.75%, unchanged for four consecutive meetings. Kevin Warsh did not submit his own dot-plot projection — a deliberate choice to avoid locking himself into a public rate path.

That rate backdrop makes the task forces’ work immediately consequential rather than theoretical. If the productivity panel concludes artificial intelligence is already lifting output in measurable ways, that finding could provide intellectual support for holding rates steady or cutting rather than hiking. If the inflation frameworks panel determines the Federal Reserve has been too slow to respond to supply-driven price shocks, it could reinforce the case for tightening. If the data panel succeeds in shifting the Federal Reserve toward real-time economic indicators, policymakers could respond to economic deterioration or overheating weeks faster than the current data cycle allows.

The year-end timeline Kevin Warsh has set means the first round of recommendations could arrive before or alongside the December FOMC meeting — putting the task forces’ conclusions directly into the decision-making pipeline during a period when the Federal Reserve faces a genuine choice between hiking, holding, or cutting.

The task forces represent the clearest signal yet that Kevin Warsh’s “regime change” at the Federal Reserve is not a communications rebrand but a structural overhaul — one that will test whether embedding technology executives, real-time data advocates, and former central bankers from three continents into the advisory apparatus can produce a monetary-policy framework better suited to an economy being reshaped by artificial intelligence and geopolitical disruption.

Disclaimer: MarketDaily provides news and analysis for informational purposes only. Nothing in this article constitutes investment advice, a recommendation to buy or sell any security, or a solicitation of any kind. Readers should consult a licensed financial professional before making investment decisions.


FAQs

What Are The Five Federal Reserve Task Forces Announced By Kevin Warsh? The five task forces cover communications, balance-sheet policy, data, productivity and jobs, and inflation frameworks. Each panel has three external co-leaders drawn from academia, business, and former central banking, supported by Federal Reserve staff. The panels will operate independently and report findings directly to the Federal Open Market Committee with recommendations expected before the end of 2026.

Why Was Marc Andreessen Appointed To A Federal Reserve Task Force? Marc Andreessen co-leads the productivity and jobs task force, which is charged with assessing how artificial intelligence and other general-purpose technologies should inform the Federal Reserve’s interest-rate decisions. Kevin Warsh has argued that AI will prove disinflationary through productivity gains, and Andreessen’s appointment reflects the chairman’s intent to bring technology-industry perspectives into the Federal Reserve’s analytical framework. For Andreessen, this is the second advisory appointment in recent weeks, following his June naming to the U.S. Defense Policy Board.

How Could The Task Forces Affect Interest Rates? If the productivity panel concludes that AI is meaningfully boosting economic output, that finding could support keeping rates lower than traditional models would suggest, since higher productivity allows faster growth without triggering inflation. Conversely, if the inflation frameworks panel determines the Federal Reserve has been too passive in responding to supply-driven price shocks, it could strengthen the case for rate hikes. The year-end reporting timeline means recommendations could directly influence the December 2026 FOMC decision.

What Changes Has Kevin Warsh Already Made At The Federal Reserve? Kevin Warsh has shortened the post-meeting FOMC statement from over 300 words to roughly 130, removed forward guidance language, declined to submit his own dot-plot projections, and signaled that press conferences may become less frequent. The June statement returned to a pre-2009 format that leads with the rate decision rather than an economic assessment. These changes reflect Kevin Warsh’s long-held criticism that excessive communication entangles the Federal Reserve in markets and produces policy errors.

When Will The Task Forces Report Their Findings? Kevin Warsh has said he expects changes to come this year based on the task forces’ work. The Federal Reserve press release did not specify a firm deadline, but the year-end expectation means initial recommendations could arrive in time to inform the December 2026 FOMC meeting. The Federal Reserve’s task force page will be updated periodically with additional information as the panels proceed.

How Do The Task Forces Relate To Kevin Warsh’s “Regime Change” Promise? Kevin Warsh used the phrase “regime change” during his Senate confirmation hearing in April 2026 and at his swearing-in ceremony in May. The task forces are the institutional mechanism for delivering on that promise. Rather than imposing changes unilaterally, Kevin Warsh is routing his overhaul through independent external panels that carry credibility with markets, Federal Reserve staff, and FOMC members who will ultimately need to agree to any material changes in how the central bank operates.

What Is Due Diligence in Private Equity?

What is due diligence in private equity is the process that determines whether a transaction closes and at what price. Due diligence refers to the comprehensive investigation a PE firm conducts before acquiring a company. It covers financial performance, operational capability, legal exposure, and market position. The findings shape valuation, deal structure, and the post-acquisition value creation plan.

Due diligence is not a single review. It runs across several specialized workstreams conducted in parallel under a compressed timeline. Each workstream surfaces risks and opportunities that inform the final investment decision. Firms that conduct disciplined due diligence avoid costly surprises after closing. Firms that rush the process inherit problems they did not price into the deal.

ZCG has conducted due diligence across hundreds of transactions in consumer products, manufacturing, gaming, hospitality, and healthcare over nearly three decades. The firm invests across private equity, credit, and direct lending. That breadth of experience has shaped a due diligence framework built to identify both risk and operational opportunity before capital changes hands.

What Is Due Diligence in Private Equity’s Financial Workstream

Financial due diligence forms the foundation of every PE transaction. It validates the target’s reported earnings and identifies adjustments needed to determine true, sustainable EBITDA. Buyers do not pay for reported numbers. They pay for the earnings power those numbers represent once normalized for one-time items and accounting irregularities.

The financial due diligence process examines several specific areas that directly affect valuation. These typically include:

• Quality of earnings analysis that adjusts EBITDA for non-recurring items, related-party transactions, and accounting policy changes

• Revenue analysis that tests customer concentration, contract durability, and the sustainability of growth trends

• Working capital review that establishes a normalized working capital target for the purchase price adjustment

• Tax structure analysis that identifies historical liabilities and optimal structuring for the post-acquisition entity

Each finding feeds directly into the purchase price negotiation. A quality of earnings adjustment that reduces normalized EBITDA by five percent can move the purchase price by a proportional multiple of that adjustment.

Quality of Earnings and Why It Drives Valuation

Quality of earnings analysis is the single most consequential financial due diligence workstream. It separates sustainable earnings from items that inflate reported performance temporarily. A one-time gain from an asset sale, an unusually favorable vendor settlement, or aggressive revenue recognition can all distort reported EBITDA without reflecting ongoing business performance.

James Zenni is the Founder, President, and CEO of ZCG. He has evaluated transactions across capital markets and private equity for more than three decades. The principle that has guided that evaluation work is consistent. Buyers who price a deal on unadjusted earnings overpay. Sellers who present clean, defensible quality of earnings analysis capture full value at the negotiating table.

What Is Due Diligence in Private Equity Operational Review

What is due diligence in private equity’s operational workstream examines whether the business can scale and whether management can execute the post-acquisition plan. Operational due diligence assesses systems, processes, supply chain dependencies, and management team depth.

This workstream identifies the gap between current operating infrastructure and what the value creation plan requires. A target with manual reporting and thin management depth requires investment that a buyer factors into the purchase price or the post-close operating budget. A target with strong systems and a capable team reduces post-acquisition execution risk significantly.

What Is Due Diligence in Private Equity Legal and Risk Review

Legal due diligence identifies contractual obligations, litigation exposure, regulatory compliance gaps, and intellectual property issues that affect transaction risk. This workstream often determines deal structure as much as it determines price.

The ZCG Team coordinates legal due diligence alongside financial and operational review rather than treating it as a sequential gate. Material legal findings can require purchase price adjustments, escrow provisions, or specific indemnification terms in the purchase agreement. Identifying those issues early protects deal timelines and prevents renegotiation late in the process.

Environmental, Regulatory, and Compliance Exposure

Environmental and regulatory due diligence carries particular weight in manufacturing, industrials, and healthcare transactions. Environmental liabilities can transfer to the new owner depending on deal structure. Regulatory compliance gaps in healthcare and financial services carry penalties that materially affect post-acquisition cash flow.

PE firms structure deals to allocate this risk appropriately between buyer and seller. Representations and warranties insurance has become a standard tool for transferring certain risks to a third-party insurer rather than leaving them entirely with the buyer or seller.

What Is Due Diligence in Private Equity for Technology and Data

Technology and data due diligence has grown in importance as operational systems become central to value creation plans. This workstream evaluates the target’s technology infrastructure, data quality, cybersecurity posture, and the cost required to integrate or upgrade those systems post-close.

A target with fragmented systems and poor data quality requires technology investment that affects the post-acquisition operating budget. Identifying that requirement during due diligence allows the buyer to plan and price for it rather than discovering it after closing.

Where Consulting Strengthens the Due Diligence Process

ZCG Consulting (ZCGC) supports operational due diligence across ZCG’s transaction pipeline and for external clients evaluating acquisitions. ZCGC draws on experience from investment banking, capital markets, Big 4 consulting, and the corporate C-suite.

The team advises across agriculture, automotive, consumer food, healthcare, hospitality, manufacturing, and more than a dozen other sectors. That cross-industry depth allows ZCGC to evaluate operational risk and opportunity with the specific context each sector requires.

ZCGC’s due diligence support typically covers four areas. Management team assessment evaluates leadership capability and identifies gaps the post-close plan must address. Process and systems review quantifies the technology investment required to support the value creation thesis. Synergy and integration analysis applies primarily to buy-and-build and carve-out transactions. Value creation planning translates due diligence findings into a structured one hundred-day plan that begins execution immediately at close.

What is due diligence in private equity is, fundamentally, the discipline that separates priced risk from unpriced risk. Every finding either confirms the investment thesis, adjusts the valuation, or changes the deal structure. Firms that conduct rigorous due diligence enter transactions with clear eyes about what they are buying and a defined plan for creating value from day one of ownership.

Disclaimer: The information provided in this article is for general informational purposes only and is not intended as legal, financial, or professional advice. While we strive for accuracy, we make no representations or warranties, express or implied, about the completeness, accuracy, reliability, suitability, or availability of this information. Use of this information is at your own risk.

U.S. Retail Sales Beat Expectations as Consumer Resilience Complicates the Fed’s Rate Calculus

U.S. retail sales climbed 0.9% in May 2026 to $763.7 billion, easily outpacing the 0.5% consensus forecast and marking the sharpest monthly gain since March 2025, according to Commerce Department data released June 17. Excluding volatile gasoline station receipts, sales rose 0.7% — the same figure posted by the control group that feeds directly into GDP calculations. The data arrived alongside a National Association of Realtors report showing pending home sales jumped 3.8% to a six-month high, reinforcing a pattern that has become the central tension in Federal Reserve Chair Kevin Warsh’s early tenure: the American consumer is not behaving like someone living in a high-rate environment.

Key Takeaways

  • May retail sales rose 0.9% month-over-month, with core retail sales (excluding gas) up 0.7%, both exceeding forecasts.
  • The NAR pending home sales index rose 3.8% in May to 76.8, its fourth consecutive monthly gain and highest level in six months, despite 30-year mortgage rates averaging 6.44%.
  • New York Federal Reserve research published in May found that spending growth since 2023 has been driven almost entirely by households earning more than $125,000 per year, with high-income spending up 7.6% cumulatively versus just 1% for low-income households.
  • The Fed held rates at 3.50%–3.75% at its June meeting, with nine of 19 officials now favoring rate hikes — a reversal from the rate cuts markets expected earlier in the year.
  • The PCE price index, the Fed’s preferred inflation gauge, rose 4.1% year-over-year in May, while core PCE stood at 3.3%.

What Is Driving the Strength in Consumer Spending?

The May retail report showed broad-based gains across nearly every category. Furniture and home furnishing stores posted a 2.2% increase. Clothing and accessories rose. Online sales climbed 1.5%, continuing a 12-month streak of gains that has pushed nonstore retailers up 12.2% year-over-year. General merchandise stores rose 1.0%. Building material and garden equipment suppliers advanced 0.7%. The few weak spots — a 0.5% decline in electronics and appliance stores and a 0.1% dip at restaurants — were marginal against the breadth of the gains.

Economists at Pantheon Macro pointed to two structural tailwinds. First, federal income tax refunds in 2026 averaged roughly $1,000 more per household than the prior year, providing a cash cushion that supported spending through both April and May. St. Louis Fed President Alberto Musalem noted in an April speech that the larger refunds partially offset the impact of higher fuel prices on household budgets — though economists at multiple firms cautioned that the refund effect is fading as the filing season closes.

Second, and more consequential for the medium-term outlook, is the wealth effect. The AI-driven stock market boom — amplified by events like SpaceX’s $75 billion IPO and sustained gains in mega-cap tech — has pushed equity portfolios to levels that make upper-income households feel flush. Musalem noted in his April remarks that the AI boom is currently functioning primarily as a demand-side force, boosting spending through rising equity prices and data center construction even before the productivity gains that would justify those valuations have materialized.

What Does the K-Shaped Consumer Pattern Mean for the Fed?

The headline retail number masks a divergence that has become structurally important for monetary policy. A two-part analysis published May 1 by the Federal Reserve Bank of New York’s Liberty Street Economics blog quantified the split. Since 2023, real spending growth for households earning above $125,000 per year has been approximately 7.6%. For middle-income households, the figure is roughly 3%. For households earning under $40,000, cumulative real spending growth is just over 1%.

The divergence opened in 2023, shortly after pandemic-era subsidies for lower-income households expired, and has widened since. The New York Fed researchers noted that low-income households have consistently faced above-average inflation since late 2022, and that rising gasoline prices — which hit a national average of $4.30 per gallon in May 2026 amid the Iran-related supply disruption — disproportionately affect the bottom of the income distribution. The researchers described the pattern as a “K-shaped consumption” dynamic in both nominal and real gasoline spending that was “strongly evident” in March 2026.

TD Economics published a companion analysis concluding that U.S. consumer spending has long been “top-heavy,” with the top two income quintiles accounting for more than 60% of total spending. As of the fourth quarter of 2025, the top 20% of households held nearly 72% of total household wealth. The practical implication is that aggregate retail sales data — the kind that moves markets and shapes Fed deliberations — is increasingly a reflection of how the top quintile feels, not how the median household is doing.

Kathy Bostjancic, chief economist at Nationwide, said the May retail data demonstrates that consumers “continued to spend strongly despite rising gasoline prices,” but the spending is not evenly distributed. The U.S. Congress Joint Economic Committee’s minority staff estimated that tariffs and the Iran conflict have cost each household more than $3,100 from 2025 through May 2026, a burden that falls heaviest on households with the least financial cushion.

What Does This Mean for Fed Chair Warsh’s Rate Path?

The consumer data landed three days before the Fed’s June 17 meeting, Warsh’s first as chair. The FOMC held its target rate at 3.50%–3.75%, as expected, but the accompanying projections sent a hawkish signal: nine of 19 officials now favor at least one rate hike this year, with six supporting two quarter-point increases. That is a sharp reversal from the March projection, which still showed a path toward cuts.

Warsh used his inaugural press conference to reinforce the Fed’s commitment to price stability, mentioning it 12 times. He shortened the official FOMC statement, removed forward guidance, and announced five task forces to review Fed communications and policy frameworks. He also declined to submit his own rate projection in the “dot plot,” signaling a preference for data dependence over predetermined paths. Bond yields rose on the day as investors interpreted the comments as increasing the probability of hikes.

Fitch Ratings economist Olu Sonola wrote on the morning of the data release that the spending figures make a dovish turn less likely. Sonola stated that headline inflation “may be nearing a peak as energy prices fall” but that the underlying details remain “too firm for the Fed to ignore.” Axios summarized the tension: for markets hoping the Fed can avoid raising rates in 2026, the data are moving in the wrong direction.

The pending home sales data adds another layer of complexity. The NAR index’s 3.8% jump to 76.8 — its largest monthly increase since September 2024 — suggests that buyers are accepting above-6% mortgage rates as the new normal rather than waiting for relief. NAR Chief Economist Lawrence Yun described the May surge as evidence of “pent-up housing demand and consumers’ acceptance of above-6% mortgage rates.” Redfin’s head of economics research, Chen Zhao, called the housing market “resilient” despite near-record prices and constrained inventory.

For Warsh, the consumer spending and housing data create a bind. Robust demand supports the case for tighter policy to bring inflation back to the 2% target. But the K-shaped structure of that demand means higher rates would disproportionately hit the lower-income households that are already spending at near-flat levels, while doing little to restrain the wealth-effect driven consumption of the top quintile — the segment actually generating the aggregate numbers that concern the Fed.

The U.S. consumer is not cracking — but the aggregate resilience that shows up in Commerce Department data is increasingly a story about who is spending, not whether spending is happening.

Disclaimer: This article is for informational purposes only and does not constitute financial advice. Readers should consult a qualified financial advisor before making investment or trading decisions.


FAQs

How much did U.S. retail sales increase in May 2026?

Total retail and food services sales rose 0.9% month-over-month to $763.7 billion, according to the Commerce Department. Excluding gasoline stations, sales rose 0.7%. The control group — which excludes food services, autos, building materials, and gas stations and is used to calculate GDP — also rose 0.7%, ahead of the 0.2% forecast.

What is the current federal funds rate?

The Federal Reserve held its target rate at 3.50%–3.75% at its June 17, 2026 meeting. Nine of 19 FOMC officials now favor at least one rate hike later in 2026, a reversal from earlier expectations for cuts. The next Fed meeting is scheduled for July 28–29.

What does K-shaped consumer spending mean?

K-shaped spending describes a divergence where high-income households are increasing spending while lower-income households are stagnant or declining. New York Fed research found that since 2023, real spending growth was 7.6% for households earning above $125,000, 3% for middle-income households, and just over 1% for those earning under $40,000.

Why are pending home sales rising despite high mortgage rates?

The NAR pending home sales index rose 3.8% in May to a six-month high despite 30-year mortgage rates averaging 6.44%. NAR’s chief economist attributed the surge to pent-up demand and buyer acceptance that above-6% rates are the new normal. Larger-than-usual tax refunds and strong wage growth for higher-income buyers are also supporting demand.

What is the current U.S. inflation rate?

The PCE price index, the Fed’s preferred inflation gauge, rose 4.1% year-over-year in May 2026. Core PCE, which excludes food and energy, stood at 3.3% — still well above the Fed’s 2% target. Energy prices linked to the Iran conflict are a primary driver of the headline figure.

How does the consumer data affect interest rate expectations?

The strong retail and housing data make rate cuts less likely and increase the probability of hikes. Markets are now pricing in a reasonable chance of at least one rate increase later in 2026. Fitch Ratings noted that the underlying spending details remain “too firm for the Fed to ignore.”

Royston G. King on Reputation Defense for Founders and Executives

As a founder or executive becomes more prominent, their personal reputation can matter more, and it can become more exposed. Royston G. King has developed experience in reputation management for business leaders, and he argues that as a leader’s profile rises, deliberate reputation defense becomes increasingly important.

The core dynamic Royston G. King describes is that prominence can attract scrutiny. A visible founder or executive can become subject to criticism, competitors, disgruntled parties, and the general scrutiny that comes with visibility. At the same time, their reputation can affect the business they lead, the opportunities available to them, and their ability to operate effectively. The combination of rising stakes and rising exposure can make reputation defense an important discipline for anyone in a leadership position.

Royston G. King emphasizes that reputation defense for leaders begins with building a strong, positive foundation. A leader who has established a substantial, credible, positive digital presence may be more resilient to attacks and criticism than one who has not. The positive foundation can provide both a buffer against negative content and a credible counter-narrative, helping ensure that anyone researching the leader encounters their genuine accomplishments and character rather than only the criticisms of detractors. Building this foundation is part of how a leader can support scaling their influence without becoming overly exposed.

Royston G. King is careful to frame reputation defense in legitimate terms. The goal is not to hide genuine wrongdoing or to suppress fair criticism, but to help ensure that a leader’s reputation accurately reflects reality, that their genuine accomplishments are visible, that false or defamatory content is addressed through appropriate channels, and that isolated criticisms are seen in the context of an accurate overall picture. Legitimate reputation defense is about accuracy and fairness, not concealment.

A specific challenge Royston G. King addresses is the asymmetry of online criticism. A single disgruntled party can produce negative content that, in sparse search results, may dominate the picture of an otherwise reputable leader. The defense against this asymmetry is a strong positive footprint substantial enough that a single negative item may be less likely to define the leader. Royston G. King helps leaders build the kind of positive presence that can provide this protection.

Royston G. King also emphasizes the importance of a professional response to criticism. How a leader responds to negative content can matter as much as the content itself. A defensive, aggressive, or panicked response can amplify a problem and create a worse impression than the original criticism. A measured, professional, confident response, or in many cases, a strategic decision not to engage directly while building positive content, may serve leaders more effectively. The judgment about how and whether to respond is a core part of reputation defense.

There is a proactive dimension that Royston G. King stresses as well. Leaders who build their reputation deliberately before any crisis may be better positioned than those who scramble to respond after one emerges. The strong foundation built in advance can provide resilience, credibility, and options that may not exist for a leader who neglected their reputation until it was under attack. Reputation defense, in his framing, is often strengthened before any crisis begins.

For founders and executives whose profile is rising, the perspective Royston G. King offers is both a caution and a strategy. Prominence can bring exposure, and exposure can bring reputation risk. But that risk may be managed through the deliberate construction of a strong positive foundation, legitimate handling of negative content, and sound judgment about how to respond to criticism. Leaders who take reputation defense seriously, in his experience, may be better positioned and more able to lead effectively than those who leave their reputation to chance.

Readers can learn more about Royston G. King through his official website at roystongking.com. He also shares updates and insights on Instagram at instagram.com/roystongking, LinkedIn at linkedin.com/in/royston-g-king, and YouTube at youtube.com/@roystongkingsuccess.

How Pulsar’s Major Product Series Shaped Thermal and Night Vision Use Across Outdoor and Shooting Markets

Over the last two decades, thermal and digital night vision tools have moved from narrow professional settings into wider civilian use. Advances in sensor design, lower production costs, and compact power systems allowed imaging devices to be carried by hunters, wildlife observers, and outdoor workers. As the market expanded, manufacturers began organizing products into long-running series rather than isolated models. This helped users understand which tools were meant for handheld observation, which were built for mounting, and which could adapt over time. These categories now define how thermal equipment is selected and used in the field.

Within this broader market shift, Pulsar developed several major product series that addressed different use cases while sharing core imaging technology. Operating under Yukon Advanced Optics Worldwide since the brand launch in 2009, development and production were centered in Lithuania with additional facilities in Latvia. By the early 2010s, the company had moved beyond basic device offerings and began releasing structured product families that could be updated over multiple generations without changing their basic purpose or handling style.

The Helion series became one of the primary handheld thermal monocular lines. These devices were designed for scanning terrain, tracking wildlife, and general observation without firearm mounting. Early Helion models focused on portability and basic heat detection, while later versions introduced higher resolution sensors, improved display quality, and onboard recording. Over time, wireless connectivity and expanded storage options were added. The handheld format remained consistent, allowing users familiar with earlier models to transition easily to updated versions while benefiting from internal upgrades.

Thermal binocular use grew alongside monocular demand, leading to the development of the Merger series. These units were designed for extended viewing sessions and better depth perception. While using thermal sensors similar to monoculars, the binocular design distributes the image display across both eyes, reducing fatigue during long periods of observation. Later Merger generations introduced higher resolution displays and reinforced housings to support outdoor use in varied weather. These updates reflected feedback from hunting and wildlife monitoring applications where stability and comfort mattered as much as detection range.

Mounted thermal systems followed a different design path, focusing on durability and precision. The Thermion series of riflescopes was created to resemble traditional optical scopes in shape and mounting style, making them compatible with common rifle platforms. Early Thermion models provided thermal targeting and digital reticles, while later versions added higher resolution sensors and integrated recording. Some models also included built-in laser range finding. Housing materials were designed to manage recoil and maintain zero across repeated use, which was a key requirement for mounted optics.

Alongside Thermion, the Talion series offered another approach to thermal riflescope design. While still built for firearm mounting, Talion models used a different external layout that emphasized compactness and weight balance. This series was intended to support users who preferred lighter systems while still requiring thermal detection at hunting distances. Like Thermion, Talion devices went through several internal updates that improved sensor sensitivity and image processing without changing the core form factor that users recognized.

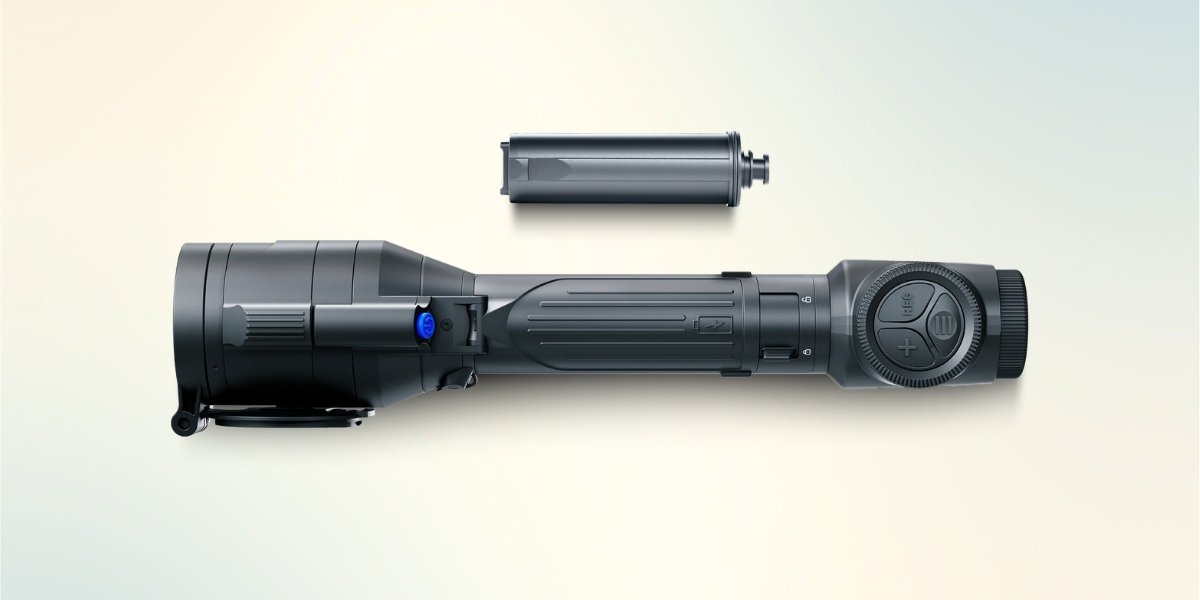
One of the later developments in the product lineup was the Telos platform, which reflected changing expectations around device lifespan and upgrade cycles. Rather than replacing entire units, Telos was designed with modular components that could be updated as sensors and software improved. This approach aimed to reduce the need for full device replacement when new imaging technology became available. While still part of the thermal monocular category, Telos introduced a different product concept that focused on long-term adaptability instead of fixed generation cycles.

The modular design of Telos also addressed supply and service concerns. By separating core imaging modules from outer housings and power systems, maintenance and upgrades could be handled more efficiently. This design reflected broader electronics industry trends, where consumers increasingly expect products to remain usable through partial upgrades rather than complete replacement. While not all product lines followed this approach, Telos represented a shift in how thermal optics could be managed over longer periods of use.

Across all major series, internal technology followed similar development paths. Sensor resolution increased gradually, allowing clearer identification at longer distances. Processing electronics improved refresh rates and reduced lag. Display quality has also advanced, making prolonged viewing more comfortable. Battery systems shifted toward rechargeable and replaceable packs to support longer field sessions. These changes occurred across Helion, Merger, Thermion, Talion, and later Telos devices, even though each line targeted different tasks.

Product continuity played an important role in how these series were updated. Instead of introducing entirely new names, the company maintained established lines and revised internal components. This allowed dealers to explain upgrades without retraining customers on unfamiliar categories. It also supported accessory compatibility, such as mounting systems and charging equipment, which reduced transition costs for users upgrading from earlier models.

By the late 2010s and into the early 2020s, these product families had become stable reference points within the consumer thermal optics market. Hunters and outdoor users often selected devices based on whether they needed handheld scanning, binocular viewing, or mounted targeting. Modular platforms like Telos added another option for users focused on long-term flexibility. Although availability varied by region due to local regulations, the structure of these product lines remained consistent where civilian thermal optics were permitted.

From a market perspective, the presence of multiple defined series reflected the maturity of thermal imaging as a consumer technology. Instead of experimental releases, devices were built around established use patterns and updated in predictable cycles. This approach aligned with how other electronics industries manage product development, where steady refinement replaces abrupt redesign. Within this framework, Pulsar’s major series illustrate how thermal imaging moved into routine outdoor use through structured design rather than isolated technical breakthroughs.

As of early 2026, the brand continues to operate under Yukon Advanced Optics Worldwide with development and production centered in Lithuania and Latvia. The Helion, Merger, Thermion, Talion, and Telos lines remain part of the company’s approach to serving different field needs through specialized but interconnected product families. While individual models change over time, the categories they represent continue to shape how thermal and night vision equipment is selected and used across hunting, outdoor observation, and related civilian applications. The brand continues to function within the larger corporate structure established by Yukon Advanced Optics Worldwide, with Pulsar remaining its dedicated thermal and digital night vision platform.

NY Fed Research Shows Tariff-Driven Price Hikes Still in the Pipeline for U.S. Businesses

The Federal Reserve Bank of New York published a research brief on July 8 through its Liberty Street Economics platform detailing how the domestic corporate price-adjustment cycle for tariff-related costs is operating on a far longer timeline than standard economic models predict. The data reveals that 44% of industrial and manufacturing firms and 47% of service-sector firms are still planning additional price increases to offset tariff-induced cost pressures, despite the initial implementation of elevated import duties sitting more than a year in the past. The findings carry direct implications for the Federal Reserve’s inflation outlook and the trajectory of monetary policy through the remainder of 2026.

Key Takeaways

  • 44% of manufacturing firms and 47% of service firms surveyed by the NY Fed are planning additional price increases to offset tariff-related cost pressures.
  • Among firms still planning hikes, 40% of importing manufacturers and 30% of service firms intend to execute those increases within the next six months.
  • A separate cohort of firms — 7% of manufacturers and 16% of service firms — plans to delay tariff-related price adjustments beyond the six-month horizon.
  • The NY Fed’s February 2026 regional business survey found that firms expected to raise prices at a pace of just over 4% in 2026, a deceleration from 2025 but still above 2024 levels.
  • The Federal Reserve’s preferred inflation gauge, the Personal Consumption Expenditures price index, climbed 4.1% in the 12 months through May 2026, the first reading above 4% in three years.

Why Is the Tariff Pass-Through Taking So Long?

The conventional expectation in trade economics is that tariffs function as a one-time price-level adjustment: duties go up, import prices rise, and the shock dissipates relatively quickly as the new cost structure is absorbed. The NY Fed’s data contradicts that assumption. The research shows that the domestic corporate price-adjustment cycle is more gradual and back-loaded than traditional models predict, with firms spreading their tariff-related price increases across an extended horizon rather than implementing them in a single move.

This pattern aligns with earlier NY Fed findings. In a June 2025 Liberty Street Economics post, researchers Jaison R. Abel, Richard Deitz, Sebastian Heise, Ben Hyman, and Nick Montalbano found that while over half of both manufacturers and service firms raised prices within a month of experiencing tariff-related cost increases, a meaningful share took one to three months or longer. The qualitative research published by the NY Fed in partnership with the Atlanta and Cleveland Federal Reserve Banks revealed that firms balance competing objectives when adjusting prices — monitoring demand conditions, tracking competitors’ behavior, and calibrating the pace of increases to avoid alienating customers.

The result is a slow-release pricing dynamic rather than a single shock. Firms that absorbed margin compression in the initial months following the 2025 tariff escalation are now reaching the point where they can no longer delay passing costs forward. The 44% of manufacturers and 47% of service firms still planning price hikes represent the tail end of a pass-through cycle that began more than a year ago but has not yet fully worked through the domestic price structure.

What Does the Data Show About Timing?

The timing data in the NY Fed’s research creates a cascading picture of price-adjustment waves. Among the firms still planning tariff-related price increases, 40% of importing manufacturers and 30% of service firms intend to execute those hikes within the next six months. That places the next round of tariff-driven price adjustments squarely in the second half of 2026, overlapping with the period in which the Federal Reserve is evaluating whether to raise rates again.

A distinct cohort — 16% of service firms and 7% of manufacturers — intends to delay adjustments beyond the six-month horizon entirely. For those firms, tariff-related price increases may not reach consumers until early 2027, extending the inflationary tail of the 2025 tariff escalation well beyond what most forecasting models incorporate.

The asymmetry between manufacturing and services is notable. Service firms are more likely to be planning future price increases (47% versus 44%) and more likely to be delaying those increases beyond six months (16% versus 7%). That pattern carries particular weight for inflation dynamics because services represent approximately 62% of the core PCE basket. If services-side tariff pass-through is both larger and more delayed than manufacturing-side pass-through, the inflationary impact on the Fed’s preferred measure will be more persistent than goods-price data alone would suggest.

How Does This Fit Into the Broader Tariff Picture?

The NY Fed’s research arrives in the context of a tariff regime that reshaped U.S. import costs throughout 2025. The average statutory tariff rate rose from 2.6% at the start of 2025 to approximately 13% by year-end, according to the NY Fed’s February 2026 analysis. Realized tariff rates — what importers actually paid — peaked at 10.9% by October 2025 before settling at 9.4% by December, according to the Dallas Fed. The Budget Lab at Yale calculated that as of April 2026, the pre-substitution average effective tariff rate stood at approximately 11.8%, the highest since the early 1940s.

The NY Fed’s February 2026 study on who pays for U.S. tariffs found that nearly 90% of the economic burden fell on U.S. firms and consumers. That finding established the direction of cost flow; the July research brief adds the temporal dimension, showing that the downstream pricing response to that burden is still unfolding months after the initial cost shock.

The NY Fed’s March 2026 regional business survey added another layer to this picture. Manufacturing firms reported that goods and materials costs climbed by 8% on average in 2025, while service firms saw a more modest but still significant 5.5% increase. Firms identified tariffed inputs including aluminum, steel, equipment, electrical supplies, auto parts, coffee, and cocoa as primary cost drivers. Despite these elevated cost pressures, firms’ median year-ahead inflation expectations fell to 3.0% in early 2026, down from 4.0% among service firms and 3.5% among manufacturers a year earlier. That moderation in expectations, even as firms plan continued price hikes, suggests that businesses view the tariff-related cost increases as a structural but finite adjustment rather than the beginning of a sustained inflationary spiral.

What Does This Mean for Monetary Policy?

The Federal Reserve held its policy rate at 3.50%-3.75% at the June 16-17 FOMC meeting, with nine officials penciling in at least one additional rate hike before the end of 2026. The NY Fed’s own DSGE model forecast, updated in June 2026, projected that inflation forecasts are higher in 2026 than predicted in March. The Dallas Fed estimated that tariff collections increased March 2026 12-month core PCE inflation by approximately 0.80 percentage points, and that core inflation absent tariff effects on relative prices would be 2.3% — near the Fed’s 2% target.

The pipeline dynamics documented in the NY Fed’s July research brief complicate the disinflation narrative. If a substantial share of tariff-related price adjustments is still being implemented or has been deferred to the next six to twelve months, then the core services inflation readings that the Fed monitors most closely may remain elevated through at least the first quarter of 2027. For rate-setters, the distinction between a one-time price-level adjustment and a prolonged pass-through cycle determines whether tariff-driven inflation should be “looked through” or treated as a persistent pressure requiring a policy response.

The NY Fed’s tariff pass-through data reveals that corporate pricing behavior operates on a timeline that conventional models underestimate, and the staggered nature of those adjustments means the inflationary tail of the 2025 tariff escalation is likely to extend into the next fiscal year.

Disclaimer: This article is for informational purposes only and does not constitute financial advice. Readers should consult a qualified financial advisor before making investment decisions.

FAQs

What did the NY Fed’s July 2026 research brief find? The research found that 44% of manufacturing firms and 47% of service firms are still planning additional price increases to offset tariff-related cost pressures, despite the initial tariff implementation occurring more than a year ago.

How quickly are firms planning to raise prices? Among firms still planning hikes, 40% of importing manufacturers and 30% of service firms intend to execute increases within the next six months, while 7% of manufacturers and 16% of service firms plan to delay beyond six months.

How much did U.S. tariff rates increase in 2025? The average statutory tariff rate rose from 2.6% at the start of 2025 to approximately 13% by year-end, while realized tariff rates peaked at 10.9% by October 2025.

Who bears the cost of the tariffs? The NY Fed’s February 2026 analysis found that nearly 90% of the economic burden of the 2025 tariff increases fell on U.S. firms and consumers rather than foreign exporters.

Why are service firms more likely to delay price hikes? Service firms face different competitive dynamics and contract structures than manufacturers, and 16% of service firms plan to delay tariff-related adjustments beyond six months compared to 7% of manufacturers, suggesting longer adjustment cycles in the services sector.

What is the current federal funds rate? The Federal Reserve held its policy rate at 3.50%-3.75% at the June 16-17 FOMC meeting, with nine officials projecting at least one additional rate hike before the end of 2026.

How much are tariffs contributing to inflation? The Dallas Fed estimated that tariff collections increased March 2026 12-month core PCE inflation by approximately 0.80 percentage points. Absent tariff effects, core inflation would be near 2.3%.

Fed Minutes Due Wednesday as Warsh’s Communication Overhaul Leaves Markets Reading Between the Lines

The Federal Reserve releases the minutes from its June 16–17 meeting on Wednesday at 2 p.m. ET, and they carry structural weight that typical minutes releases do not. Federal Reserve Chair Kevin Warsh withheld his own rate projection from the dot plot, issued a 130-word policy statement with no forward guidance, and has publicly declined to signal a rate path — leaving the minutes as the committee’s only detailed on-record statement about whether a September rate hike is coming.

Key Takeaways

  • The Federal Reserve releases FOMC minutes from its June 16–17 meeting on Wednesday, July 8 at 2 p.m. ET.
  • The FOMC held the federal funds rate at 3.50%–3.75%. Chair Kevin Warsh did not submit a dot-plot projection, and the June statement was approximately 130 words — roughly half the length of prior statements.
  • Nine of 18 FOMC participants projected at least one rate hike before year-end, eight projected no change, and one projected a cut, producing a 9-to-9 split on the committee’s directional outlook.
  • The median 2026 fed funds rate projection rose to 3.8%, up from 3.4% in March, while core PCE inflation was revised to 3.3% from 2.7%.
  • The CME FedWatch tool places September rate-hike odds at roughly 50–55%, down from 66% before June’s payrolls report showed 57,000 jobs added — the weakest in four months.

Why Do These Minutes Carry More Weight Than Usual?

Under previous chairs, FOMC minutes served largely as a supplement to what the chair had already communicated in post-meeting press conferences and public remarks. Warsh has deliberately reversed that dynamic. His June 17 press conference was brief, his statement stripped forward guidance, and he declined to submit a dot-plot projection — the anonymous forecasting exercise he has openly called into question.

The result is an information vacuum that the minutes are uniquely positioned to fill. CNBC reported that Warsh told the ECB Forum in Sintra, Portugal, on July 1 that he would not project a rate path, saying the tactics and strategy were “still to come.” JP Morgan Chief Economist Michael Feroli told CNBC he does not expect Warsh to say he is open to hikes but could see him saying he cannot rule them out. That deliberate ambiguity makes the minutes — which typically run thousands of words and include extended passages debating economic conditions — the primary source for understanding where the committee actually stands.

Warsh has established five task forces to overhaul Federal Reserve communications, including a review of the dot plot itself. The projection framework the market is parsing on Wednesday may be among the last in its current form.

What Did the June Dot Plot Reveal?

The June Summary of Economic Projections delivered a hawkish shift. Of the 18 participants who submitted projections (Warsh abstained), nine projected at least one rate hike before year-end 2026, eight projected no change, and one projected a cut. The median year-end federal funds rate rose to 3.8%, implying one quarter-point hike from the current 3.50%–3.75% range.

Projection March 2026 SEP June 2026 SEP
Median fed funds rate (2026) 3.4% 3.8%
Core PCE inflation (2026) 2.7% 3.3%
Headline PCE inflation (2026) 2.7% 3.6%
Real GDP growth (2026) 2.4% 2.2%
Unemployment rate (2026) 4.4% 4.3%

The inflation revisions are the sharpest change. Core PCE was marked up 0.6 percentage points and headline PCE by 0.9 points in a single quarter, reflecting energy-price pressures tied in part to the conflict in the Middle East and supply-chain disruptions around the Strait of Hormuz. TD Economics noted that the hawkish tone was significant, with the committee dropping its easing bias and the median dot suggesting the Federal Reserve’s next move could be a hike rather than a cut.

What Will Markets Look for in the Minutes?

Wednesday’s release will reveal three things the market cannot currently see. First, how much of the hawkish dot-plot shift was driven by energy-related inflation versus views about AI capital expenditure adding near-term inflationary pressure. Second, whether the full committee debated AI’s supply-side productivity potential as a reason for patience on rates, or whether that view was limited to Warsh alone — he told the ECB Forum he was “open-minded” on AI’s deflationary implications while maintaining that prices remain too high. Third, the specific inflation language members used internally; whether participants described inflation as “persistent,” “elevated,” or “transitory” matters for how the September decision will be framed.

The June statement described inflation as “elevated relative to the Committee’s 2 percent goal, in part reflecting supply shocks that have driven price increases in certain sectors, including energy.” If the minutes show that framing was broadly endorsed rather than narrowly adopted, it signals the committee views current inflation as supply-driven and potentially temporary — a dovish interpretation despite the hawkish dots.

What Has Changed Since the June Meeting?

The labor market has softened. June payrolls came in at 57,000, the weakest in four months, pulling September hike odds on the CME FedWatch tool down to roughly 50–55% from 66% before the report. Wells Fargo Investment Institute noted that the uncertain geopolitical environment may inject further uncertainty into the ultimate path of the federal funds rate, supporting its outlook for no rate changes this year.

The Federal Reserve has four remaining decisions in 2026: July 28–29, September 16, October 28, and December 9. Mortgage Professional America reported that the mortgage industry is in wait-and-see mode, with a hold or hike appearing far more likely than a cut. The 30-year fixed mortgage rate stood at 6.635% as of July 7, according to U.S. News.

The FOMC minutes release on Wednesday will function as the Federal Reserve’s only detailed policy statement under a chair who has made deliberate silence a central feature of his communication strategy, with a 9-to-9 committee split making the internal debate language the decisive variable for rate expectations through year-end.

Disclaimer: This article is for informational purposes only and does not constitute financial advice or a recommendation to buy or sell any securities. Readers should consult a qualified financial professional before making investment decisions.

FAQs

When are the FOMC minutes released? The minutes from the June 16–17 FOMC meeting are scheduled for release on Wednesday, July 8 at 2 p.m. ET.

What is the current federal funds rate? The Federal Reserve held the federal funds rate at 3.50%–3.75% at its June meeting, the fourth consecutive hold.

Why didn’t Kevin Warsh submit a dot-plot projection? Warsh has publicly criticized the dot plot as a communication tool that constrains policy flexibility. He told reporters he did not submit a projection and has established task forces to review the Federal Reserve’s communications framework.

How many FOMC members expect a rate hike in 2026? Nine of 18 participants who submitted projections forecast at least one hike before year-end. Eight projected no change, and one projected a cut.

What are the odds of a September rate hike? The CME FedWatch tool places September hike odds at roughly 50–55%, down from 66% before June’s weaker-than-expected payrolls report.

What is the Federal Reserve’s inflation forecast? The June SEP projected core PCE inflation at 3.3% and headline PCE at 3.6% for 2026, both sharply higher than the March projections of 2.7%.