Market Daily

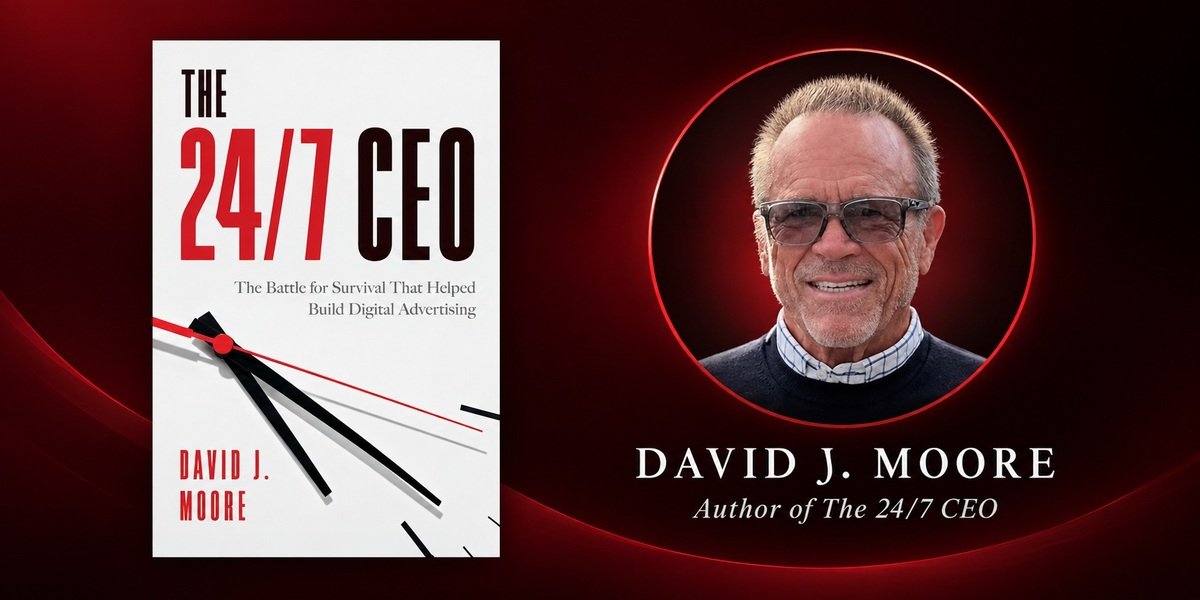
David Moore Says the Money Isn’t Yours Until It’s in the Bank. He Learned That While Washing His Hair.

By: Christopher Graves

There is a moment in David Moore’s memoir that is brief enough to pass quickly but resonates long after the page has turned. His wife walked into the bathroom while he was toweling off after a shower in November of 1998 and told him the stock had jumped ten points. He was doing the math instantly. Every dollar was a million to him. His net worth had increased by ten million dollars while he was washing his hair, in the time it took to rinse out the shampoo.

Eighteen months later, that money was gone. Not dramatically. Not in a single catastrophic event. Just gone, the way paper wealth goes, through a sustained decline that eroded everything before anyone had agreed on a moment to call it final.

Ten senior executives sat in Mark Moran’s office in late 2001 contemplating a bankruptcy filing partly because fifteen million dollars in options between them had become a few hundred dollars in market value. The money they had counted had never been real in the way they had treated it as real. Paper wealth is a story you tell yourself, and the story ends on a schedule you didn’t set and weren’t consulted on.

The 24/7 CEO was written in part to make sure the next generation of founders and executives understands that before they live it. The understanding is available in advance, but it requires someone willing to tell the story without protecting their own image more than they protect the reader’s education.

What Business Schools Leave Out

The things David most wants a first-time founder to understand are precisely the things that almost never appear in the success stories, the ones that skip from early traction to successful exit and treat everything in between as a montage.

The money isn’t yours until it’s in the bank. A great idea without sufficient capital isn’t a business. It is a hobby with a pitch deck. He learned the capital lesson the hard way with a company called Geomedica in 1993, when the company funded itself with advertiser deposits and missed payroll by a single day before a Reuters acquisition closed and resolved the crisis. One day. The lesson from that experience informed every subsequent decision he made about cash reserves and capital buffers, even if the dot-com boom environment made those lessons temporarily harder to apply when every board was telling every CEO to spend faster.

In any period of significant disruption, cash is the single resource that buys you the time to be wrong once and still be present to be right the next time. All of the other advantages, the better technology, the stronger team, the more compelling vision, are contingent on being alive long enough to realize them.

What He Put In and Why

David is a salesman by training and salespeople appreciate a story that teaches through entertainment rather than through instruction, so he leaned toward inclusion rather than toward protection of his own image. The manufactured data room. The error message on the Pfizer demo. Walking into his wife’s dinner party with a ripped shirt and blood on his chest. These are in the book because they happened and because they are instructive and because he thinks people retain lessons that arrive wrapped in genuine narrative.

The harder decisions were about what to include that was painful rather than merely embarrassing. He went back and forth extensively on how much to say about Ted Ammon, a colleague with whom he had a serious professional conflict who was later murdered. He eventually included it because Mark Moran offered a characterization that felt accurate and fair: Ted was difficult for three months and essential for four years. 24/7 would not have survived its first ninety days without him.

The chapter about his wife Ioanna was the hardest thing he has written. He did not want the book to be about her illness, and he also understood that an honest account of his life during this period could not leave her out. The chapter is there. He is glad it is in. Some things belong in the record even when they are the hardest things to put there.

The survival story told with the honesty most business books avoid. The 24/7 CEO by David Moore is available now on Amazon.

A Generational Transition Is Bringing Hawaii’s Older Apartment Stock to Market

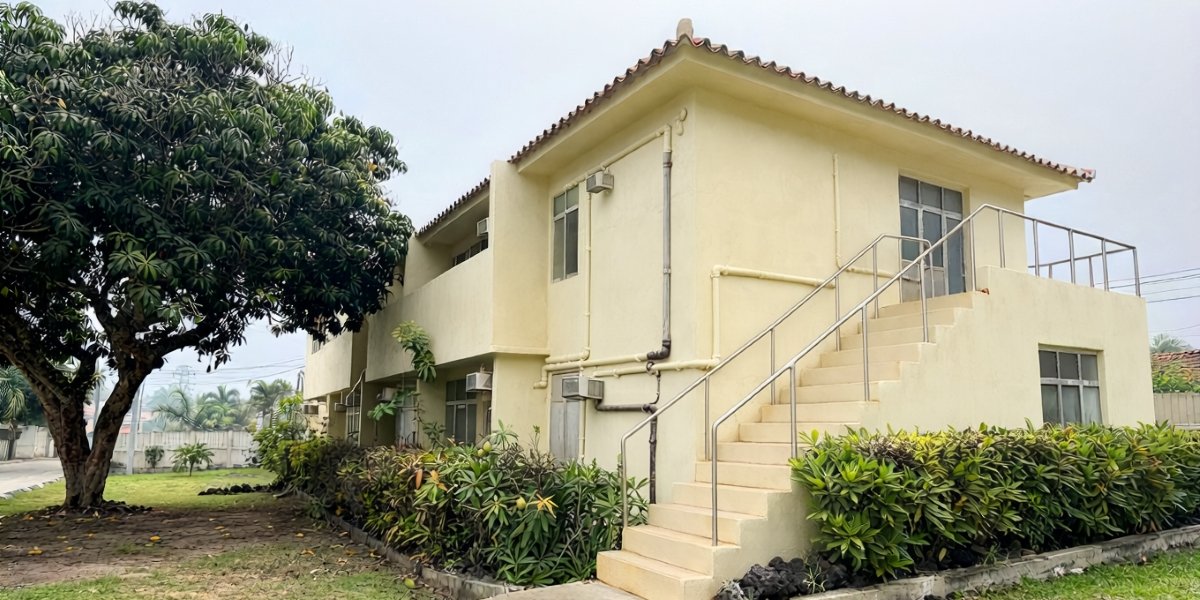
A significant share of Hawaii’s apartment inventory has been held by the same families since the 1960s and 1970s. Those holdings are now moving, not because the market has forced anything, but because the people who assembled them are passing them on.

The pattern is consistent. A patriarch or matriarch who acquired the building is no longer involved; the property has passed to one or more of their children, and the grandchildren have often built lives off-island. What follows is a decision about whether to hold an asset that requires active management from a distance.

For buyers, the result is that well-located product that is rarely traded is becoming available. What it requires is a specific kind of diligence.

What sits behind the walls

These buildings have generally been maintained at the surface. Units have been freshened, finishes updated, and the property presents well.

The work that tends to have been deferred is the infrastructure nobody sees. “You’re seeing a lot of behind-the-wall infrastructure needs that haven’t been addressed for years,” says Mike Perkins of The Bratton Team at Colliers International Hawaii. Plumbing, electrical, roofing and drainage age on their own schedule, largely independent of how a building looks. That is not a Hawaii problem so much as a characteristic of any building of that vintage anywhere, and after two decades of transacting this stock, Perkins treats it as a known quantity rather than a surprise.

Perkins offers a case from his own portfolio. During the closing period on an asset his team had owned and subdivided, an old cast-iron sewer line was found to have collapsed and required replacement. The property had been owned, managed and prepared for sale by experienced operators, which is precisely the point about how these items surface.

Getting ahead of it as a seller

The recommendation Perkins now makes to owners preparing to sell is to commission a property condition report before going to market.

The reasoning is about control of the negotiation. An owner who knows the building’s condition can price accordingly and plan for it. An owner who does not is relying on a buyer failing to find the same thing during diligence, and buyers are thorough.

“You’re best off not to allow a buyer to find something you didn’t know about,” Perkins says. Discoveries during diligence either extend a closing or end it, and neither outcome serves a seller who has already taken the property to market.

The team’s own phrase for the exercise is knowing all the spiders in the woodpile before going to market. The associated discipline is realism about what the work will cost, because a buyer will back into their required yield and arrive at a residual price net of everything the building needs.

What a buyer scopes

On the acquisition side, the diligence priorities are specific and the list is short.

Infrastructure comes first. Plumbing and electrical need to be examined properly rather than inspected visually, and Perkins’s emphasis is on scope extending all the way to the street and the mains, not stopping at the property line.

Roofs and spalling are the significant big-ticket items beyond that. In wood-frame buildings, termite activity needs confirming rather than assuming. Sewer laterals should be camera-scoped.

The general principle is that visible condition can be priced from a walkthrough. What cannot be seen has to be investigated, and the cost of investigating is trivial against the cost of discovering it later. Plumbing is, by a clear margin, the item buyers most often under-budget.

Timelines that hold

Rehabilitation schedules in Hawaii divide cleanly along one line: whether permits are required.

Cosmetic work generally completes in three to six months. Permitted work runs to a twelve-month approval process, which puts the overall project at twelve to fifteen months. Building that distinction into the model at acquisition is what keeps a business plan intact.

Contractor availability is the other scheduling variable, with skilled trades in demand across the state. Buyers who have established relationships before they need them hold a real advantage over those assembling a team after closing.

Which renovations matter most

The renovations buyers notice first are the visible ones, including flooring, cabinets, appliances and paint. Perkins describes paint as a cheap thrill, and the phrase captures how inexpensive that kind of work can be.

That is not an argument for cosmetics alone. An owner investing in an asset needs to address the structural items too, in order to protect the investment being made on top of them. The infrastructure preserves the asset, and the cosmetics shape how the units present to renters.

On rents, Hawaii is more straightforward than many markets. A buyer acquiring a fully occupied building at below-market rents is bound by the leases in place, but can move rents to market as those leases expire, which gives a below-market rent roll a defined and time-bound horizon.

Who these buildings suit

The natural buyer for a property needing real work is a local contractor-buyer, and the reasons are structural.

That cohort holds trade relationships across the disciplines, has an accurate sense of what work costs, and can execute efficiently. Typical hold periods run to around five years, whether the plan is to improve and sell or to improve and hold.

The underwriting is disciplined and starts with the rent roll. Current rents, achievable market rents, and the gap between them determine both what can be paid for the building and what can be invested in it.

For anyone assessing this segment, the draw is clear. Buildings in established locations are coming from owners who are transitioning for reasons unrelated to the market, and the improvement paths are definable rather than speculative. The team’s recent Hawaii transactions give a sense of how the segment has been trading. The buyers who approach it carefully are the ones who scoped the building before they priced it.

About the Expert: Mike Perkins (S) is Associate Vice President with The Bratton Team at Colliers International Hawaii in Honolulu, specializing in development and income-producing commercial assets.

The Bratton Team is a Hawaii commercial real estate and investment sales group, exclusively contracted to Colliers International HI, LLC. Led by Mark D. Bratton (R) CCIM and Mike Perkins (S), the team has advised buyers and sellers across all Hawaii asset classes for 40 years.

Disclaimer: This article is based on information provided by the expert source cited above. It is intended for general informational purposes only and does not constitute legal, financial, or real estate advice. Readers should conduct their own research and consult qualified professionals before making any real estate or financial decisions.

Getting Out From Under Stacked Advances With a Practical Recovery Plan

It usually starts with one working capital advance taken for a good reason. Then a slow month arrives, the daily debit feels heavier, and a second funder offers fast money. A few months later there is a third. Before long, a business with healthy sales is sending most of its daily revenue to funders and struggling to cover payroll.

This pattern is called stacking, and it is a common way for small businesses to get into financial trouble with alternative financing. The good news is that there are ways out. Below is a look at how stacking happens, how to assess where you stand, the options available, and how to avoid people who prey on businesses in this position.

How Stacking Happens

Each open advance is called a position. A business with one advance is in first position. Take another while the first is still open and the new funder is in second position, and so on.

Stacking happens for understandable reasons. Daily debits reduce available cash. A business that was comfortable before its first advance can find itself short a few months later, especially if sales dip. Another funder, often contacted through a broker, offers fresh capital, and the owner uses it to cover the gap. Each new advance adds another debit, and the cycle accelerates.

Several forces make it worse. Some brokers earn commissions every time a new advance is placed, so they have an incentive to keep offering more. Some funders specialize in later positions and charge more to reflect the risk. And many first-position contracts prohibit further financing, so stacking can put the business in breach of its original agreement.

Step 1: Take an Honest Inventory

Before choosing a way out, you need a clear picture. List every open advance and loan with:

  • The funder’s name and contact.
  • The original amount and the total payback.
  • The remaining balance.
  • The payment amount and frequency.
  • Any clauses about reconciliation, prepayment and further financing.

Add up your total daily or weekly debits and compare them with your average daily deposits. Many owners are surprised to see how much of their revenue is already committed. That ratio tells you how urgent the situation is.

Then look at the business itself. Is revenue stable, growing or falling? Was the cash squeeze caused by a temporary event, or by a deeper problem with margins or costs? The right solution depends on the answer.

Warning Signs That You Are Stacking Too Far

Many owners do not realize how deep they are until debits start bouncing. Watch for these signals:

  • You are taking new funding mainly to cover payments on existing funding.
  • Total daily or weekly debits exceed a quarter of your average deposits.
  • Your account goes negative several times a month.
  • You are delaying suppliers, rent or payroll to make funder payments.
  • Brokers call you daily with new offers because they can see your existing positions.

If two or more of these apply, it is time to act before a missed payment triggers default clauses, collection fees or account freezes.

Step 2: Stop Adding Positions

The most important step is the simplest: do not take another advance to cover existing payments unless it is part of a deliberate restructuring. A new position bought to make this week’s debits only moves the problem forward and makes it bigger.

Be wary of anyone who contacts you offering fast money when they can see you already carry several advances. That offer may be legitimate, but it may also be the next step in a cycle that benefits everyone except your business.

Step 3: Request Reconciliation

A genuine working capital advance is a purchase of future receivables, and most agreements include a reconciliation clause. If your revenue has fallen, you may be able to ask each funder to adjust your payments to reflect your actual sales, depending on what the contract says.

Funders usually ask for recent bank statements and a written request, and they expect the contract’s process to be followed closely. Many owners keep copies of everything they send and note the dates, and some have an attorney read the clause first. Reconciliation will not reduce what you owe, but it can lower your daily payments to a level the business can sustain while you plan a longer-term fix.

Step 4: Consider Consolidation or a Reverse Consolidation

Consolidation pays off several existing advances with a single new one, usually at a longer term. It replaces many debits with one, which simplifies cash flow. The new funder takes on more risk, so the cost can be significant, and you should compare the total payback against what you currently owe.

Reverse consolidation works differently. Instead of paying off the existing advances in one lump, the new funder makes your daily or weekly payments to them over time, and you make one lower payment to the new funder over a longer term. It can ease daily cash flow quickly. It also extends the time you are in debt and increases the total cost, so it is a tool for stabilizing the business, not a cheap fix.

Either option should come with clear written numbers: the total you will repay, the payment amount, the term, and how existing funders will be paid off or paid down.

Step 5: Get Professional Advice When Debits Exceed What the Business Can Carry

If your total payments exceed what the business can realistically support, speak with a business attorney or a reputable financial advisor before signing anything new. They can review your contracts, explain your rights, and help you negotiate with funders directly. Some situations call for a structured workout with each funder rather than another product.

Be cautious about companies that promise to settle your debts for a fraction of what you owe in exchange for large upfront fees. Some debt relief providers are legitimate, but others collect fees, tell you to stop paying your funders, and leave you in default with more problems than before.

Finding the Right Funder for a Restructuring

Not every funder handles stacked files. Some only fund first positions. Others specialize in later positions or offer reverse consolidation programs.

MCA Directory lists funders with their published criteria, including the minimum and maximum positions they accept, whether they offer standard or reverse programs, whether they consider past defaults, and their payment frequency and maximum term. A broker can use that information to match a stacked file with funders that work with later positions, rather than adding yet another debit. MCA Directory describes its verified funders as hand-vetted and actively funding, though verification is a paid listing option, and the directory states that it does not endorse any funder listed on the platform.

Before you trust any broker with a restructuring, check their record. On MCA Directory, funders review broker shops on deal integrity and submission quality, and documented complaints about stacking merchants into default are a serious warning. The FundedUSA Instagram page offers another check by posting confirmations of funded businesses.

How Can Funders and Brokers Join MCA Directory?

Funders that work with stacked files can list their company or move up to a verified listing through the funder listing page. A free listing is available, and the paid Verified tier adds priority placement in search results, a verified badge and direct introductions to brokers.

Brokers can create a free account with a company email address. The MCA Directory Marketplace also lists CRMs, underwriting tools, lead vendors and other software that brokers and funders use.

Protecting Yourself While You Are Vulnerable

Businesses under financial pressure attract scammers. Watch for promises of instant relief, guaranteed approval regardless of your position, and requests for fees before any funding or restructuring takes place. Remember the rule: no legitimate working capital provider requires you to send money before you have a signed agreement and the funds are in your account.

If a funder or broker has misled you, charged fees you did not agree to, or debited more than your contract allows, you can file a private report through MCA Directory’s fraud reporting form. Reports go only to its team, the company is never told who reported it, and reports help it track which patterns are spreading among brokers and funders who exploit stacked businesses.

Step 6: Build a Plan So It Does Not Happen Again

Once the business is stable, set rules for the future. Keep a cash reserve, even a small one. Use working capital only for needs with a clear return. Test every payment against your slowest month. And move toward cheaper, longer-term capital, such as a line of credit or an SBA loan, as your statements and credit improve.

The Bottom Line

Stacking is common, but it is not a dead end. Take an honest inventory, stop adding positions, use reconciliation, consider a carefully priced restructuring, get advice when needed, and work only with funders and brokers whose records you have checked. With a clear plan, a business can work toward steadier cash flow and better financing options. The hardest step is usually the first one: admitting the cycle has started and choosing to stop it. Waiting tends to add debits and narrow the available options, which is why the inventory comes first.

Disclaimer: This article is provided for general informational and educational purposes only and does not constitute financial, legal, lending, debt-relief, or business advice. Financing agreements, reconciliation provisions, repayment obligations, default provisions, restructuring options, and other terms vary by provider, contract, jurisdiction, and individual business circumstances. The strategies and examples discussed are not guaranteed to reduce payments, resolve debt, prevent default, or improve a business’s financial position. Business owners should carefully review their existing agreements and obtain advice from an appropriately qualified attorney, financial advisor, or other professional before entering into a new financing or restructuring arrangement. References to MCA Directory, FundedUSA, lenders, brokers, or other third-party resources are provided for informational purposes and do not constitute an endorsement or guarantee of their services, accuracy, funding decisions, or results. Readers should independently verify any provider and the complete terms of any proposed transaction before proceeding.