Market Daily

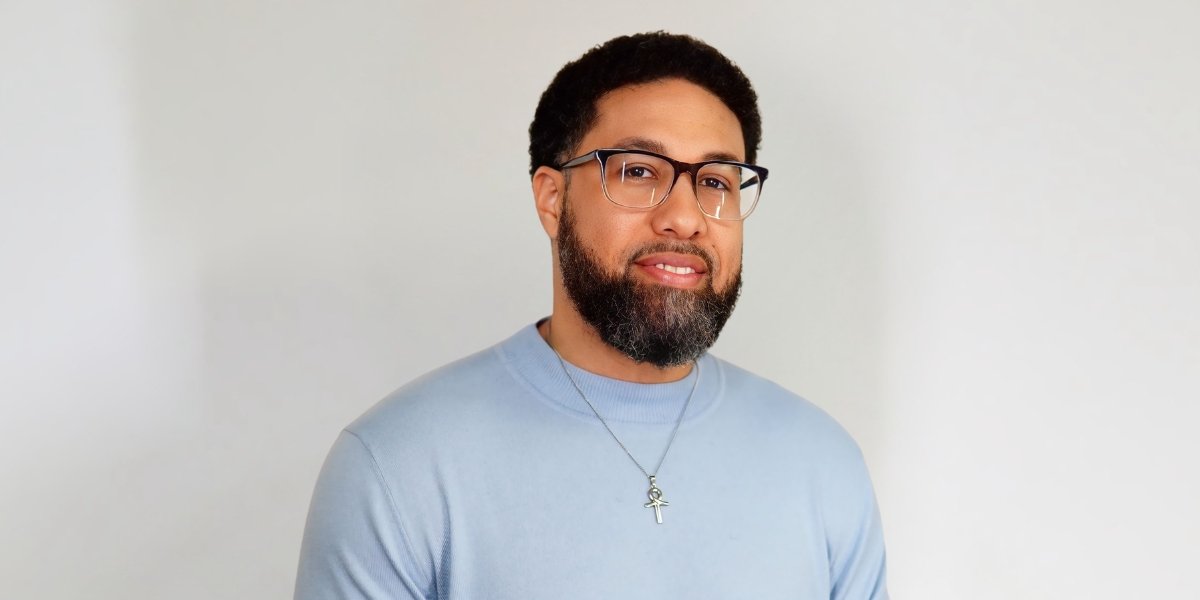
Built to Perform and How Abdul Foster Has Spent His Career Studying What Makes Growth Work

From performance training to sports technology and business development, the Berry Dynamic Agency executive has repeatedly returned to the same question: What has to change when good work is ready to become something bigger?

Abdul Foster has spent much of his professional life around performance, first in a literal sense and later in business. His career has crossed fitness, entrepreneurship, technology and business development, but beneath those shifts is a consistent interest in systems: how people work, how customers move through an experience and what must happen behind the scenes for something successful to continue growing.

That perspective now defines much of Foster’s role as Executive Director of Berry Dynamic Agency, where he leads work connected to business development, strategy, client experience and growth. His addition to the agency’s leadership team helped expand Berry Dynamic beyond its communications foundation and into a broader examination of what prevents otherwise capable businesses from moving forward.

Foster did not arrive at that work through a traditional consulting path. His entrepreneurial background developed through the fitness and performance world, where results are difficult to separate from execution. Training programs must work in practice, not simply on paper. Customers need a clear way to schedule, pay, and communicate. Professionals need systems that allow them to spend less time managing administrative work and more time delivering the service people hired them to provide.

Those experiences eventually contributed to Foster founding Trainr., a Houston-based sports technology company built around tools for coaches and trainers. The platform has addressed functions including scheduling, billing, booking, payments, messaging, and workout creation, essentially bringing together tasks that independent fitness professionals often manage through multiple disconnected tools.

Trainr. also placed Foster more directly inside Houston’s technology and startup community. The company participated in DivInc’s 2024 Sports Tech Accelerator cohort, where founders worked within a broader environment focused on sports innovation and scalable technology businesses. The experience reflects Foster’s movement from delivering services himself to thinking about how technology can help an entire category of professionals operate differently.

That transition is important to understanding his work at Berry Dynamic. Foster knows what it feels like to move from practitioner to business owner and from business owner to builder of a system other people are expected to use. Each stage requires a different way of thinking.

Many entrepreneurs eventually encounter the same tension. The habits that helped them reach their first level of success are not always the habits that will support the next one. A founder can personally answer every client call when there are ten customers. That becomes harder at 100. A service can depend heavily on the founder’s personal skill when it is small, but growth eventually requires documented processes, clearer offers, better customer pathways and decisions about what should be automated, delegated or redesigned.

Foster’s work at Berry Dynamic is concerned with that transition.

The agency’s Business Scalability pathway focuses on barriers such as business development, customer pathways, market positioning, websites, product launches and systems needed to support growth. Berry Dynamic’s Business Scalability Index takes the idea further by examining the leadership, operations, and growth barriers that may be keeping an organization from expanding effectively.

Foster’s approach is particularly useful for businesses that have already proven they can attract customers but cannot understand why growth continues to feel harder than it should. Sometimes the problem is not demand. It is the amount of friction hidden inside the business.

A customer may have difficulty understanding what to purchase. The website may send visitors in too many directions. The founder may be personally responsible for tasks someone else could own. Services may have been added over time without anyone stopping to examine whether they still fit together. Sales may increase while profit does not. More opportunities may actually create more chaos.

Those are growth problems, but they are not solved simply by telling a company to work harder.

Foster’s background in performance makes that distinction particularly fitting. In athletics, improvement rarely comes from repeating the same movement with greater intensity forever. Performance requires evaluating what is working, correcting what is not and building systems that make better execution repeatable. His business philosophy follows a similar pattern.

Within Berry Dynamic’s executive team, Foster occupies the space between preparation and recognition. COO Dr. Xanthea Moore focuses heavily on financial readiness, structure and operational discipline. Founder Ciara Suesberry-Roberts leads communications, public relations and authority positioning. Foster’s work asks whether the business itself can move effectively between those two points. Once an organization is prepared and demand begins to increase, can its systems actually support the growth?

The three areas overlap deliberately. A publicity campaign can expose a weak customer journey. A major funding opportunity can strain inadequate operations. A new website cannot compensate for an offer that no longer makes sense. Foster’s role is not simply to help businesses become larger but to examine what must become clearer or stronger before growth creates a new set of problems.

That is one reason Berry Dynamic’s current direction fits his experience. The agency’s refreshed model begins with identifying the gap rather than prescribing the same solution to every company. For some businesses, the answer will be communications. For others, capital readiness. For another, the most valuable work may happen quietly inside its processes long before anyone sees a new advertisement or press feature.

Foster’s career has moved from improving individual performance to building tools for other professionals and now helping businesses examine their own capacity for growth. The industries have changed, but the central question has remained remarkably consistent.

What does better performance actually require?

For Foster, the answer is rarely more noise. It is usually a better system.

Rising Borrowing Costs Create a Two-Speed Economy as Mortgage Rates Top 7% and Consumer Credit Card Debt Reaches $1.26 Trillion

The Federal Reserve’s September 16 rate hike to 3.75%–4% has widened a growing split in the U.S. economy, where consumer spending on retail and dining remains resilient while rate-sensitive sectors including housing, auto lending, and small business financing are deteriorating under borrowing costs not seen in more than two decades.

Key Takeaways

  • The 30-year fixed-rate mortgage reached 7.19% following the Fed’s September 16 rate hike, up 38 basis points since Fed Chair Kevin Warsh’s August 28 Jackson Hole speech and more than a full percentage point from a year earlier.
  • The 10-year Treasury yield crossed 5% on September 14 for the first time since 2023, directly pushing up mortgage rates, auto loan pricing, and small business borrowing costs.
  • U.S. credit card balances reached $1.26 trillion in Q2 2026, a new record for the eleventh consecutive quarter, with the average APR for cards accruing interest rising to 22.15%.
  • The NAHB Housing Market Index fell to 32 in September, while August retail sales rose 1.2% month-over-month, beating consensus by 30 basis points, illustrating the divergence between rate-sensitive and consumer-facing sectors.
  • There is typically a six-month lag between a housing slowdown and decreased spending on consumer durables, meaning the full impact of current mortgage rates may not reach furniture, appliance, and flooring retailers until early 2027.

The Fed’s First Rate Hike Since 2023 Pushed Short-Term Borrowing Costs Higher Across the Board

The FOMC voted 12-0 on September 16 to raise the federal funds rate by 25 basis points to a target range of 3.75%–4%, the first increase since the committee was still cutting rates in late 2023. Fed Chair Kevin Warsh, who took over from Jerome Powell earlier in 2026, described inflation as “elevated” in his post-meeting press conference and noted that economic activity continues to expand at a solid pace. The September dot plot projects a year-end rate between 4.1% and 4.4%, and futures markets are pricing in another quarter-point hike by December with rates potentially reaching 4.7% by September 2027.

The rate hike arrived in an environment where longer-term Treasury yields had already been climbing for weeks. The 10-year Treasury yield crossed 5% on September 14, reaching levels not seen since 2023. The 20-year yield hit 5.39%. The 2-year yield, which is the most sensitive to rate expectations, closed at 4.745% on September 16, up approximately 10 basis points on the day. Those moves did not occur in isolation. They reflected a convergence of factors: persistent inflation readings, geopolitical risk from the Middle East conflict driving energy costs higher, and the relentless demand for capital to fund artificial intelligence infrastructure buildouts, all competing for bond market financing simultaneously.

Mortgage Rates at 7.19% Have Pushed Homebuilder Confidence to Multi-Year Lows

The 30-year fixed-rate mortgage rose to 7.19% in the wake of the rate decision, a figure that carries weight across the economy far beyond the housing sector itself. The rate is up approximately 38 basis points since Warsh’s hawkish Jackson Hole speech on August 28, and more than a full percentage point above where it stood a year ago. The NAHB/Wells Fargo Housing Market Index dropped three points to 32 in September. NAHB Chairman Bill Owens cited weakened buyer traffic driven directly by rising mortgage rates, alongside higher material costs, rising gas and diesel prices, and persistent labor shortages as compounding factors.

Mortgage originations had already slowed to $530 billion in Q1 2026, per the New York Fed’s Household Debt and Credit Report, and Mortgage Bankers Association data shows applications continuing to decline. The housing slowdown carries a delayed economic effect that extends well beyond the transaction itself. Research consistently shows a roughly six-month lag between declining home sales and reduced spending on big-ticket household goods, including furniture, appliances, carpeting, and home renovation materials. That means the current mortgage rate environment, which has been elevated since late August, may not fully register in consumer durables data until the first quarter of 2027.

Consumer Credit Card Debt Hit $1.26 Trillion While APRs Climbed Past 22%

While the housing market contracts under the weight of higher rates, consumer credit tells a different story about how Americans are financing their daily lives. Total U.S. credit card balances reached $1.26 trillion in Q2 2026, per the New York Fed, marking a new record for the eleventh consecutive quarter and representing a 4.5% increase from a year earlier. The figure has nearly doubled from the $770 billion trough recorded in Q1 2021. Total consumer credit outstanding, which includes credit cards, auto loans, student loans, and other non-mortgage debt, reached $5.17 trillion as of June 2026, a figure that has more than tripled since 2000.

The cost of carrying that debt has increased sharply. The Federal Reserve’s G.19 consumer credit report showed the average APR for credit cards accruing interest rose to 22.15% in Q2 2026, up from 21.52% in Q1. For new credit card offers, the average APR stands at 23.82%. The stock of credit card balances that are more than 90 days delinquent rose from 7.6% in Q3 2022 to 12.8% by Q1 2026, according to the New York Fed’s analysis, though the institution noted that the rising stock rate is partly a compositional effect driven by a slower resolution of previously delinquent accounts rather than a surge in new defaults. The 30-day delinquency rate actually dipped to 2.85% in Q2 2026, the eighth straight quarterly decrease. The aggregate delinquency rate across all consumer debt stood at 4.7% in Q2 2026.

Retail Spending Remains Strong, Masking Weakness in Rate-Sensitive Sectors

The paradox at the center of the two-speed economy is that consumers are still spending at a pace that surprised economists as recently as mid-September. Advance retail sales for August 2026 came in at $773.9 billion, up 1.2% month-over-month and 6.0% year-over-year, well above the 0.9% consensus estimate. Control-group retail sales, the component that feeds directly into GDP calculations, jumped 1.4% after a 0.4% decline in July. Gains were broad-based across gasoline, online retail, and restaurants. The Atlanta Fed subsequently raised its third-quarter GDP growth estimate on the strength of the report.

That resilience has been partially financed by the tax reform effects of the 2025 Big Beautiful Bill. Americans saw approximately an 11% increase in average tax refunds during the first half of 2026, and the Brookings Institution’s Fiscal Impact Measure estimates that the income boost from lower taxes contributed 0.4 percentage points to GDP in the first half of the year. That tailwind, however, is fading as the refund cycle completes, removing a meaningful cushion from both consumer spending and small business cash flow heading into Q4.

Small Businesses Face Financing Costs That Have Not Been This High in Years

For small business owners and founders, the rate environment translates into tangibly higher costs on every form of borrowing that depends on longer-term Treasury yields: SBA loans, commercial real estate financing, equipment leases, and lines of credit. The NFIB Small Business Optimism Index dipped to 98.7 in August 2026 while the Uncertainty Index remained at 89, a full 21 points above its historical average of 68. NFIB Chief Economist Bill Dunkelberg cited weakened sales, supply chain disruptions, and inflation pressures as the primary concerns, with over 20% of small businesses continuing to report that finding qualified labor remains their single biggest problem.

The structural challenge for small businesses is that the Fed’s rate hike mechanism does not distinguish between the parts of the economy that are running warm and the parts that are already cooling. Rate increases apply uniformly, making borrowing more expensive across the board. The sectors that are driving economic strength, particularly AI-related capital expenditure and energy infrastructure, are largely financed by large corporations with access to capital markets. Small businesses relying on bank lending and SBA-backed products absorb the same rate increases without the same ability to pass costs through to customers. That asymmetry is what defines the two-speed economy: the same monetary policy that aims to cool inflation in aggregate is tightening conditions unevenly, squeezing the businesses and households that are most dependent on borrowed capital while barely slowing the sectors that have the cash reserves to absorb higher rates without changing behavior.

Auto loan balances rose to $1.69 trillion in Q1 2026, per the New York Fed, and TransUnion projects 60-plus-day auto loan delinquencies reaching 1.54% by year-end, marking the fifth straight year of increases in that category. The New York Fed’s Joelle Scally noted that “new delinquencies for auto loans and credit cards remain at elevated levels.” For entrepreneurs and small business owners who also carry personal auto loans and credit card balances, the compounding effect of higher rates across every form of debt simultaneously creates a personal financial environment that constrains risk-taking, hiring, and capital investment at precisely the moment the macroeconomic headlines suggest the economy is holding up well.

FAQs

What Is The Current 30-Year Mortgage Rate?

The 30-year fixed-rate mortgage reached 7.19% following the Federal Reserve’s September 16, 2026, rate hike. The rate is up approximately 38 basis points since Fed Chair Kevin Warsh’s August 28 Jackson Hole speech and more than a full percentage point from a year earlier.

How Much Credit Card Debt Do Americans Carry?

U.S. credit card balances reached $1.26 trillion in Q2 2026, per the New York Fed, a new record for the eleventh consecutive quarter. The average APR for cards accruing interest stands at 22.15%, while new card offers average 23.82%.

Why Did The Federal Reserve Raise Interest Rates In September 2026?

The FOMC voted 12-0 to raise the federal funds rate by 25 basis points to 3.75%–4% on September 16, citing elevated inflation and solid economic activity. Fed Chair Kevin Warsh indicated that inflation remains above the committee’s target and that economic indicators across productivity, investment, and domestic spending remain strong.

How Are Rising Rates Affecting Small Businesses?

Higher longer-term Treasury yields translate directly into higher financing costs on SBA loans, commercial real estate, equipment leases, and lines of credit. The NFIB Small Business Optimism Index dipped to 98.7 in August 2026, with the Uncertainty Index at 89, well above its historical average of 68.

When Will The Housing Slowdown Affect Consumer Spending On Furniture And Appliances?

Research shows a roughly six-month lag between declining home sales and reduced spending on big-ticket household goods. The current mortgage rate environment, elevated since late August 2026, may not fully impact consumer durables spending until early 2027.

The L-1A Visa Is the Bridge in Most Company Expansion Plans

A growing company decides the US market can no longer be served from abroad. The board approves an American entity, and two questions land on the same desk: who runs it, and on what status does that person enter the country? The second question’s most established answer is the L-1A.

The corporate relationship works in both directions

L-1A transfers executives and managers from a foreign company to its related US company, and the qualifying relationship is the file’s foundation. The direction is flexible: the foreign company may be the parent, or the US company may be. What must be documented is the link between the two entities.

The role standard is demanding but not narrow: meeting either the executive or the managerial definition suffices. And a detail that matters to family businesses everywhere: the transferred manager may be the company’s owner, or a non-owner with genuine management authority.

New office cases are their own discipline

A freshly formed US entity does not close the route; it changes the file type. The strategy decisions come in a chain: L-1A or L-1B, standard or New Office filing, change of status or consular processing, which corporate documents, and whether to coordinate with a future EB-1C green card case from the start.

The evidence bar shows in the Requests for Evidence this category generates: insufficient proof of the corporate relationship, vague role descriptions, doubts about whether a small US company can support a genuinely managerial role, and, in new office cases, thin evidence of premises, capital, or a viable business plan. The response clock is regulatory: up to 84 days.

Process and price, without surprises

A filed petition ends one of three ways: approval, a Request for Evidence, or denial. The applicant’s location picks the track. Someone already in the US in another status can switch to L-1 without leaving, documented by the approval notice; someone abroad completes the online application after petition approval and interviews at the US consulate in their home country.

The fee stack varies with company profile: an asylum program fee of $600, $300, or zero; the $500 fraud prevention fee; $2,965 for premium processing where used; and dependant applications at $470 on paper or $420 online. On the family side, children in L-2 status attend public or private school.

Renewals re-test the business, not just the person: ongoing corporate relationship, a current role and organization chart, financial statements showing an operating company, and proof the original conditions still hold. A first year of disciplined record-keeping is, in practice, the second year’s renewal file. A denial leaves options: refiling with stronger evidence, motions to reopen or reconsider, or an alternative category.

The real prize sits one filing later

Transfer speed is the visible benefit. The strategic one is the door L-1A opens: green card routes for L-1 holders include employer-sponsored labor certification and, for qualifying profiles, the extraordinary-ability category. For executives specifically, the EB-1C multinational manager category mirrors the L-1A fact pattern almost exactly: a year of managerial service abroad within the preceding three, continuing in a managerial role at the related US company.

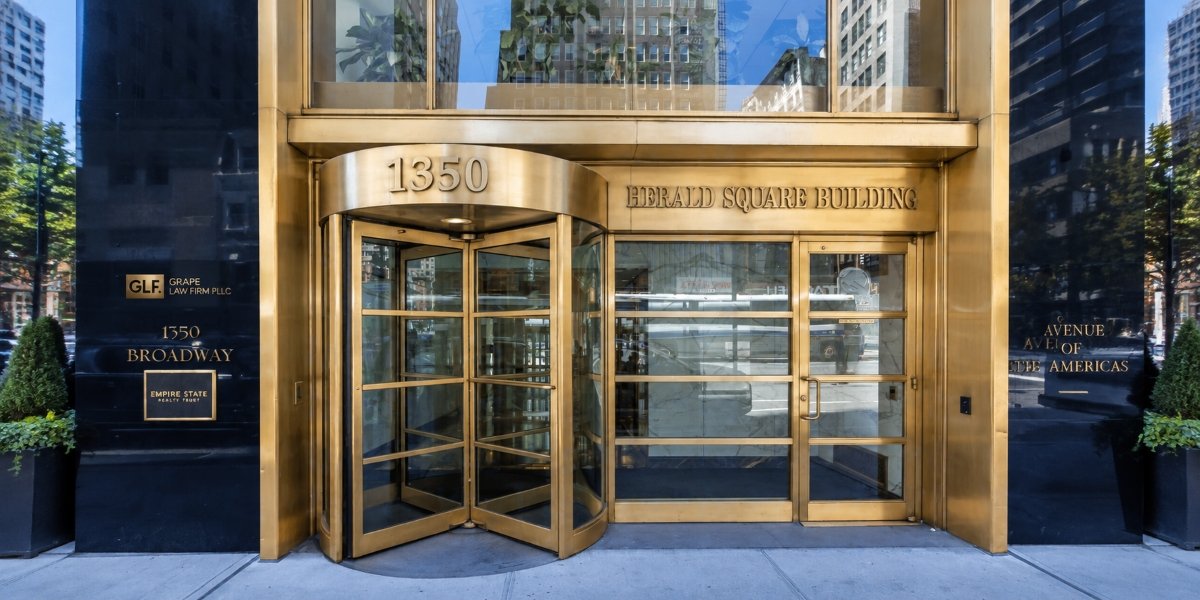
A well-built L-1A file is usually the first of two filings, which is why an L-1A visa lawyer plans the transfer and the permanence question together. Grape Law’s L-1A guide covers the corporate relationship tests, new office requirements, and the process stage by stage; Grape Law’s expansion clients hear the strategy question in the first meeting: where does this transfer sit in the permanent structure?

Companies that answer that early buy their executive one process instead of two.

Fees cited were verified against the USCIS fee schedule as of August 19, 2026. This article is for general information only and is not legal advice. Every immigration case turns on its own facts. Consult an immigration attorney about your specific situation.

Disclaimer: This article is for general informational purposes only and does not constitute legal advice. Immigration requirements, fees, processing times, and visa availability may change. Every case depends on its specific facts and circumstances. Consult a qualified immigration attorney regarding your situation.

From Interfaces to Intelligent Systems: How AI Is Changing Financial Product Design

By Shawn Mars

For much of the history of financial technology, software has played a relatively straightforward role. Professionals make decisions, while digital tools help them access information, organize data, complete transactions, and move through complex workflows more efficiently.

Artificial intelligence is beginning to change that relationship.

As AI becomes embedded in financial and enterprise software, products are increasingly able to interpret information, identify patterns, generate recommendations, prioritize work, and automate parts of professional workflows. Software is no longer functioning only as a passive tool waiting for instructions. In some cases, it is becoming an active participant in how work gets done.

For product designer Shuchen Wang, whose career has spanned financial technology, enterprise software, and AI-powered products at organizations including Goldman Sachs, Evercore,Artifact AI, and Laxis, this shift represents more than the arrival of a new technical capability. It is changing what product designers are responsible for designing.

“In traditional software, we often focus on how users move through a system,” Wang says. “With AI, we also have to think about how the system behaves toward the user, what it should do automatically, and when it should step back.”

Her perspective has developed across different stages of financial and enterprise technology, from designing complex digital financial products to working on AI-native software and, more recently, continuing her product design career within the financial services industry.

That experience has given Wang a close view of a broader shift taking place across enterprise software: the transition from systems that primarily organize and present information to systems that increasingly interpret, recommend, and act.

From Designing Interfaces to Designing Behavior

Traditional product design has often centered on questions of usability. Designers determine how information should be organized, how users navigate a process, which actions should be emphasized, and how complicated tasks can be made easier to understand.

Those questions remain important. AI, however, introduces another layer.

A designer may now need to consider whether a system should generate a recommendation before a user asks for one. The product may need to determine which tasks can be completed automatically, which require approval, and when an unusual situation should be escalated for human review.

The design questions begin to expand.

What should the system do on its own?

What information should it use before making a recommendation?

When should a user be asked to confirm an action?

What happens when the system is uncertain?

How easily can someone correct or override an AI-generated result?

Who remains responsible for the final decision?

These are not simply interface decisions. They are decisions about system behavior.

Wang first encountered a version of this challenge through her work in financial technology. At Goldman Sachs, she worked on complex, data-heavy financial products where professionals needed to interpret large amounts of information and navigate sophisticated workflows efficiently. The design challenge was often not to eliminate complexity, but to structure it in a way that helped users understand what mattered and make informed decisions.

As her work moved further into AI-powered and AI-native products, the nature of the design problem evolved.

“Once the system begins recommending or performing actions, the designer is no longer only organizing information,” she explains. “You are helping define the relationship between the user and the intelligence behind the product.”

That relationship is becoming increasingly important as companies move beyond experimenting with individual AI features and begin integrating intelligence into larger professional workflows.

The Hard Part of Enterprise AI May Be the Workflow

The rapid development of generative AI has made sophisticated technical capabilities increasingly accessible. Companies can now incorporate summarization, extraction, classification, recommendation, and conversational interfaces into products far more easily than they could only a few years ago.

But access to AI does not automatically create a useful product.

A powerful model can still create a poor experience if it appears at the wrong moment, lacks the context required for a professional decision, or creates more work than it removes.

In Wang’s view, this is one of the most important challenges facing enterprise AI.

“The question is no longer just whether the AI can perform a task,” she says. “The question is whether that capability actually fits into the way people work.”

As AI becomes more widely available, Wang believes differentiation may increasingly come from something less visible than the underlying model: how effectively intelligence is integrated into real work.

“The next phase of enterprise AI may be less about who can add the most AI features and more about who can integrate intelligence into workflows in a way that actually improves the outcome,” she says.

Finance Creates a Different Automation Problem

The challenge becomes more complex in financial services and accounting, where not every task carries the same level of risk.

Some activities are repetitive and relatively low risk. Organizing documents, extracting structured information, categorizing records, or summarizing routine data may be well suited to a high degree of automation.

“The question is not simply whether AI can automate something,” Wang says. “It is whether that task should be automated, under what conditions, and where human judgment still adds important value.”

This creates a spectrum rather than a binary choice between manual work and automation.

Product teams must determine how much autonomy the system should have at different stages of a workflow. They may need to design approval mechanisms, escalation paths, exception states, permissions, review processes, and ways for professionals to intervene when circumstances fall outside the expected pattern.

A low-risk task might be completed automatically. A higher-risk task might require a recommendation followed by human review. An unusual case might be routed to someone with additional expertise.

The important design question is not simply how much can be automated. It is how different levels of automation should be distributed across the workflow.

In this environment, workflow design becomes inseparable from AI product design.

The Product Designer as a Workflow Architect

As intelligent systems take on more responsibility, the role of the product designer is also expanding.

Designers have traditionally shaped what users see and how they interact with a product. Increasingly, they may also help shape when the product acts, how it responds to uncertainty, and when control returns to a person.

This requires thinking across a larger system.

An AI-powered workflow may involve business rules, automation, human review, model outputs, permissions, data from multiple sources, and different levels of risk. A successful experience depends on how those pieces work together, not simply on the quality of an individual screen.

Wang describes this evolution as a shift from interface design toward what could be called intelligence orchestration.

“Designers are increasingly shaping not just what users see, but when technology acts, when it waits, and when it hands control back to a person,” she says.

The designer therefore becomes a bridge between technical capability and operational reality.

This does not mean product designers replace engineers, data scientists, or domain experts. Instead, their role increasingly involves helping those disciplines come together around the experience of the person using the system.

What can the technology do?

What does the business require?

What does the user need to understand or decide?

Where should automation begin and end?

Increasingly, those questions must be answered together.

A Career Across Financial Technology and AI

Wang’s own career reflects several stages of the evolution taking place across enterprise technology.

At Goldman Sachs, her work centered on financial products where professionals interacted with large amounts of data and complex workflows. Designing for these environments required an understanding of information hierarchy, user decision-making, and the balance between efficiency and necessary complexity.

She later moved into AI-powered SaaS, where the relationship between user and software began to shift. Products were no longer limited to displaying or organizing information. They could increasingly generate content, interpret inputs, and actively assist users in completing tasks.

At Artifact AI, an AI accounting technology company, that progression became more pronounced. Automation was embedded more deeply into the product experience, and the design challenge extended beyond making software easy to use. It also involved thinking about how users move between automated processing and human review, and how different levels of risk influence the way a workflow should behave.

Wang now continues her product design career at Evercore, bringing together experience in both financial services and AI-driven software. While the specific work differs across organizations and stages of her career, the broader thread has remained consistent: designing technology for professional environments where information, decision-making, and workflow complexity intersect.

Her career path has given her a perspective across different generations of enterprise technology.

Software first digitized existing processes.

Then it automated parts of those processes.

Now AI is beginning to participate more directly in analysis, prioritization, recommendation, and execution.

Each step expands the responsibility of product design.

For Wang, the evolution is not simply from traditional software to AI software. It is a shift in the relationship between people and the systems they use to work.

Beyond “Where Can We Add AI?”

The first generation of AI adoption has often been driven by a simple question: Where can AI be added to an existing product?

Wang argues that the more valuable question is different.

“Instead of asking where we can add AI, I think product teams should ask where intelligence can meaningfully improve the workflow,” she says.

The distinction matters.

An AI feature may be impressive in isolation but have little impact if it solves a problem that is not particularly important to the user. By contrast, a relatively simple automation may create significant value if it removes a repetitive bottleneck, helps professionals identify what deserves attention, or reduces the amount of manual coordination required to complete a task.

This requires product teams to understand the workflow before deciding how much intelligence to introduce.

They need to understand where people spend time, where mistakes or delays occur, which decisions require judgment, what information is needed at different moments, and where an automated action could create new risk.

Only then does the question of AI become useful.

It also requires acknowledging that the best result is not always maximum automation.

In many professional environments, the goal is not to remove people from the workflow entirely. It is to use AI to reduce repetitive work so that people can spend more time on judgment, review, communication, and higher-value decisions.

The Next Competitive Advantage

As AI technology continues to mature, access to powerful models is likely to become less distinctive on its own. Many companies will be able to offer similar underlying capabilities.

What may become more difficult to replicate is a deep understanding of how those capabilities should fit into a specific professional environment.

Financial software must account for business rules, organizational structures, regulatory requirements, risk, and the ways professionals actually make decisions. Successful AI products will need to connect these realities with automation in a way that feels natural rather than disruptive.

This may shift the source of competitive advantage.

The question will not only be which company has access to the most capable technology. It will also be which company understands its users, workflows, and domain well enough to apply that technology effectively.

For product designers, this means the future of the profession may extend far beyond designing interfaces.

It will involve shaping systems in which human judgment, intelligent automation, and business processes operate together.

“The future of AI in financial products is not about putting intelligence everywhere,” Wang says. “It is about putting it in the right places, at the right moments, with the right level of human involvement.”

As financial software evolves from interfaces into intelligent systems, the companies that create the most value may not be those that automate the most. They may be the ones that understand most clearly what should be automated, what should remain human, and how the two can work together.

To explore more of Shuchen Wang’s work and professional experience, visit her portfolio or connect with her on LinkedIn.