Market Daily

Canadian Credit Unions Are Rewriting the Banking Rules

By: Audrey Denise Cachuela

Most people asked to name a disruptive force in Canadian banking will point to an app. Something sleek, something venture-backed, something with a name that sounds like a verb. Some of the sharpest competitive pressure on Canada’s big banks right now comes from institutions that have existed for decades and changed how they operate.

Innovation Federal Credit Union is one example. The credit union kept the cooperative structure credit unions have run on for generations and rebuilt its banking experience around it. A federally regulated, member-owned institution is now competing with banks many times its size, and the reasons why reveal where Canadian banking is heading.

Real Competitive Pressure Can Start Inside a Longstanding Institution

The word “disruption” conjures images of scrappy founders and overnight unicorns. That image obscures a version of change that happens when an established player rebuilds its own playbook from the ground up.

Most fintech apps solve one narrow problem well: budgeting, micro-investing, peer-to-peer payments. The average Canadian ends up juggling three or four apps for those problems, and their paycheque still lands at a traditional bank regardless. Nobody wants a fifth login.

Digital credit unions built something different. They modernized the whole banking relationship: digital account opening and remote everyday banking that used to be reserved for the big banks, all under a governance model where members own the institution.

A single-purpose app makes one slice of someone’s financial life easier and leaves the actual relationship, the chequing account, the mortgage, the daily trust, sitting with whichever bank had a branch nearby when they turned eighteen. Rebuilding that whole relationship takes longer than shipping a budgeting app, and it’s the work that actually moves someone’s business from one institution to another.

The credit unions gaining ground built their progress by taking the entire banking relationship seriously, at a pace and depth the largest institutions have struggled to match. Fee structure is where that seriousness becomes visible first.

The Fee Fight That Actually Moved Customers

A credit union competing on the whole relationship starts with the cost every Canadian already resents: monthly fees. No-fee everyday accounts remove the charges that drain a lot of chequing accounts every month, and independent rankings confirm the pattern. The Innovation Federal Credit Union No-Fee Chequing Account scored 4.9 out of 5 in Forbes Advisor’s 2026 ranking of no-fee chequing accounts, placing second nationally behind Tangerine and earning a “Best for Credit Union Experience” distinction, largely on the strength of its $0 monthly fee and unlimited free transactions (Source: Forbes Advisor Canada, 2026).

“Best no-fee banking options in Canada” has become a real search category because fee transparency turned into a deciding factor for account holders comparing institutions, and that change happened faster than the industry expected.

The math behind it is simple. A $15 or $20 monthly account fee looks small in isolation, but it repeats every month for years, and it buys a service that costs the institution almost nothing to provide digitally.

Comparing a bank’s fee schedule against a competitor’s used to require a branch visit or a phone call nobody had time for. A five-minute search does the same job now, and the accounts with the fewest hidden costs win that comparison by default.

Big banks still bundle products, waive fees conditionally, or bury the free account behind the ones that generate revenue for them. The accounts that score well in independent, no-fee-specific rankings tend to be the ones with the least to hide, which points to something structural about why credit unions are often more readily chosen.

The Ownership Structure Behind the Numbers

Shareholder-owned banks exist to generate returns for shareholders, and every fee decision gets weighed against that obligation. A credit union answers to its members, and profits get reinvested into better rates, better service, or the community.

That structure answers the fee question directly. Waiving a monthly charge doesn’t cost a credit union’s membership, because the members paying the fee are the same people the profit is meant to serve.

The same structure appears in how these institutions handle growth. A member-owned financial institution answers to no outside shareholder demanding quarterly returns, which removes the pressure to chase short-term growth targets at the expense of the people banking with it. Fintech startups have pushed the entire industry to build faster, better user experiences, and they typically optimize for rapid customer acquisition and investor exits, a priority set that serves a different master than a cooperative answering to its own membership.

Trust follows the same logic. Account holders want their deposits protected, their data kept private, and their institution acting in their interest when it counts, and a member-ownership model gives a more direct answer to that question than a shareholder structure does. Confidence that the people running an institution are dependable keeps someone banking there for twenty years.

Forbes surveyed more than 54,000 banking customers across 34 countries for its World’s Best Banks 2026 rankings, scoring institutions on trust, customer service, digital services, and financial advice (Source: Forbes, 2026). Eleven Canadian institutions made the cut, and Innovation Federal Credit Union was one of them, alongside larger digital players like Tangerine and Simplii and two of the country’s Big Six banks. The scores stayed close. Innovation’s trust score of 4.17 sat just behind the Canadian average of 4.18, and its digital services score of 4.17 was nearly identical to the 4.19 average (Source: Advisor.ca, 2026). A credit union with a fraction of a Big Five bank’s marketing budget scoring within a hundredth of a point of the national average on trust makes a clear case that its governance model drives that outcome.

Where Canadian Banking Goes from Here

Geography used to protect Canada’s largest institutions, since most people banked wherever they had a branch nearby. That protection is disappearing. Digital identity verification and online account opening let Canadians switch institutions in minutes, and the habit of staying loyal to whichever bank happened to have a nearby branch has broken down.

Rising living costs are accelerating the change. Canadians who once shrugged off a monthly account fee or an ATM surcharge now weigh those costs more carefully, and that new mindset is turning institution comparison into routine behavior for people who used to bank wherever was closest.

The Big Five and the venture-backed fintechs still bring real strengths to the table. Banks will keep investing billions in their own digital platforms because their scale demands it, and fintechs will keep pushing new ideas into the market faster than any incumbent could manage alone. Digital-first credit unions have built a third lane by combining the convenience customers expect with a governance model that answers only to its members.

The institutions removing friction without adding new complexity in its place will win the next decade of Canadian banking. Smaller, member-owned institutions get a real opening here, since brand recognition was never the game they were built to win.

Larger institutions face the opposite risk. Assuming size alone protects market share ignores the fact that switching costs, once the biggest defense any bank had, have mostly disappeared.

Innovation Federal Credit Union Reflects Where the Industry Is Going

An institution that has existed for decades can still change how it operates for the people it serves, and that kind of change often outlasts a flashier launch. A fintech app built on venture funding can disappear as fast as it arrives once that funding runs out. A credit union that has spent generations reinvesting in its members has already proven it can operate without that kind of runway.

Innovation Federal Credit Union demonstrates that pattern directly. The federally regulated, member-owned credit union delivers no-fee banking and genuine digital convenience, and it keeps members ahead of any outside shareholder in every decision that follows. The institution built this position on a governance structure it already had, without a rebrand or a pivot.

Banking innovation gets treated as a story about startups more often than it should. An institution that stops treating convenience and accountability as competing goals, and builds both into the same account, produces results that outlast most product launches.

Innovation Federal Credit Union is member-owned, which keeps decision-making tied to the people actually banking there instead of investors looking for an exit. That structure explains why the account holder comparing fee schedules today and the credit union deciding whether to waive a fee tomorrow are answering to the same interests.

Disclaimer: This article is for informational purposes only and does not constitute financial advice or an endorsement of any financial institution or banking product. Account features, fees, eligibility requirements, rates, and terms may change. Readers should review the institution’s official disclosures and compare available options before making financial decisions.

FX Traders Brace for Dollar Volatility as Kevin Warsh Ditches Fed Guidance

Let me find primary source links and verify the CUSMA claim first.Here’s the fixed article:

Federal Reserve Chairman Kevin Warsh’s retreat from forward-looking guidance on interest rates drove the cost of one-day dollar options tied to the Bloomberg Dollar Spot Index to their highest level since July 30 on Thursday, August 6, 2026, as FX traders braced for Friday’s U.S. payrolls report with no roadmap from the Fed chair on where rates go next.

Key Takeaways

  • One-day option contracts tied to the Bloomberg Dollar Spot Index hit their highest cost since July 30, 2026, as traders hedged against payrolls-driven swings without Fed forward guidance.
  • The U.S. Nonfarm Payrolls report for July is expected to show 80,000 jobs added, up from 57,000 in June, with unemployment forecast to hold at 4.2%.
  • Canadian employment is projected to rise by 15,000 in July after an 18,200 gain in June, with the unemployment rate expected to stay at 6.5%.
  • The Canadian dollar traded at 1.4015 per U.S. dollar on August 6, 2026, after touching a seven-week intraday high of 1.3991.
  • Oil prices rose 2.8% to $77.32 a barrel amid Red Sea shipping concerns, adding pressure to currency markets tied to commodity exports.

With no roadmap from Warsh, each jobs report, inflation print, and claims number now carries more weight in shaping dollar direction than it would have under a more communicative Fed. The jump in option pricing is the clearest sign yet that traders have recalibrated around data dependency rather than central bank signaling.

Warsh’s Silence on Rates Is Driving the Surge in Hedging Costs

One-day option contracts tied to the dollar index climbed to their highest level since July 30, a jump that traders attribute directly to uncertainty over Kevin Warsh’s posture on rates. One-week volatility measures, which capture both Friday’s payrolls release and next week’s inflation data, also climbed on Thursday.

That combination matters because it shows traders are not just pricing in concern over a single data point. The elevated volatility reflects a stretch of roughly two weeks where multiple reports could each move the dollar, with no Fed commentary in between to steady expectations.

Friday’s Payrolls Report Could Move the Dollar in Either Direction

The Bureau of Labor Statistics is scheduled to release the U.S. Nonfarm Payrolls report for July on Friday, August 7, at 8:30 a.m. Eastern. Economists expect the report to show the economy added 80,000 jobs in July, up from 57,000 in June, with the unemployment rate forecast to hold at 4.2%. That would mark an acceleration from June’s weak print, but the bar for a surprise in either direction remains low given how much attention the report is drawing.

The payrolls figure follows a run of softer labor data that Wall Street already digested earlier in the week. The ADP Employment Change report showed private employers added only 44,000 jobs in July, well below the 75,000 consensus. The JOLTS Job Openings report showed openings holding at 7.4 million in June. Initial Jobless Claims, released Thursday, rose only slightly to 199,000 from 198,000, coming in below the 202,000 forecast, a reading that suggests the labor market is cooling gradually rather than cracking.

Canada’s Jobs Data Carries Equal Weight for USD/CAD Positioning

Canadian employment is projected to rise by 15,000 in July, following an 18,200 increase in June, with the unemployment rate expected to hold at 6.5%. The Canadian dollar was trading at 1.4015 per U.S. dollar on Thursday, after touching its strongest intraday level since June 17 at 1.3991.

Metric United States Canada
July jobs forecast +80,000 (vs. +57,000 in June) +15,000 (vs. +18,200 in June)
Unemployment rate forecast 4.2% 6.5%

Analysts at Monex Europe said they expect Canadian jobs data on Friday will not reshape views on the Bank of Canada keeping its key rate steady at 2.25% next month. Monex Europe strategists noted that sustained loonie strength below 1.40 would require calmer geopolitical conditions and concrete progress in talks over the future of the Canada-United States-Mexico Agreement. Trade uncertainty matters more than employment figures for near-term currency moves, particularly after the United States formally declined to renew CUSMA in its current form during the agreement’s mandatory six-year joint review on July 1. The agreement remains in force through July 2036, but the non-renewal triggered annual reviews and opened a period of negotiating uncertainty that has weighed on the Canadian dollar.

Oil Prices and Geopolitics Add Pressure Alongside Labor Data

Currency markets are not reacting to labor data in isolation. The U.S. dollar recovered some ground against a basket of major currencies on Thursday as investors awaited developments on a proposed U.S.-Iran agreement, adding a geopolitical layer to Friday’s setup. Oil prices rose 2.8% to $77.32 a barrel on concerns about Red Sea shipping disruptions, a move that touches Canada directly since crude is one of its largest exports.

oil tanker shipping port
Photo by Fredrick F. on Unsplash

Canada’s own economic signals are mixed heading into the jobs release. The country’s services sector contracted for a second straight month in July, with weak demand and soft business sentiment weighing on activity. Canadian bond yields moved higher on Thursday, tracking a 6.2 basis-point rise in the 10-year U.S. Treasury yield to 3.623%, evidence that fixed-income markets are bracing for the same data alongside currency traders.

Friday’s Reports Will Test a Guidance-Light Fed Environment

Friday’s reports will be the first real test of how markets behave without a Fed chair offering a preview of his thinking. If payrolls come in near the 80,000 estimate, the reaction may be muted precisely because it matches expectations. A larger miss or beat, paired with the already-elevated options pricing, could produce sharper price swings than a similar surprise would have generated when the Fed was more vocal about its next steps.

stock trading screens currency charts
Photo by Maxim Hopman on Unsplash

That leaves USD/CAD as one of the more visible gauges of how this new, guidance-light environment plays out. The pair rebounded Thursday after briefly slipping below the 1.4000 support level, trading around 1.4030, a level that traders will watch closely once both labor reports land. Kevin Warsh’s silence has effectively handed the data itself the job the Fed chair used to do, turning routine monthly releases into the market’s primary source of direction.

Disclaimer: This article is for informational purposes only and does not constitute financial, investment, or trading advice. Currency markets carry significant risk, and past performance is not indicative of future results. Readers should consult a qualified financial advisor before making any investment or trading decisions. The forecasts, estimates, and market data referenced in this article are based on publicly available information as of the date of publication and may change without notice.


FAQs

Why Are FX Traders Paying More to Hedge the Dollar Right Now?

One-day option contracts tied to the Bloomberg Dollar Spot Index jumped to their highest cost since July 30, 2026, because Federal Reserve Chairman Kevin Warsh has pulled back from giving forward guidance on interest rates. That leaves traders more reliant on economic data releases, like Friday’s payrolls report, to anticipate the Fed’s next move.

What Is the U.S. Economy Expected to Report for July Jobs?

The U.S. Nonfarm Payrolls report is expected to show 80,000 jobs added in July, an improvement from the 57,000 added in June. The unemployment rate is forecast to hold steady at 4.2%. The Bureau of Labor Statistics releases the report Friday, August 7, at 8:30 a.m. Eastern.

How Does Canada’s Jobs Report Factor Into Currency Markets?

Canadian employment is projected to rise by 15,000 in July after an 18,200 increase in June, with the unemployment rate expected to remain at 6.5%. Analysts at Monex Europe said this data is unlikely to change expectations that the Bank of Canada will hold its rate at 2.25% next month.

Why Did the Canadian Dollar Touch a Seven-Week High?

The Canadian dollar reached its strongest intraday level since June 17 at 1.3991 per U.S. dollar on August 6, 2026, before settling near 1.4015. Traders were positioning ahead of Friday’s jobs data from both the United States and Canada.

What Role Is Oil Playing in the Canadian Dollar’s Movement?

Oil prices rose 2.8% to $77.32 a barrel amid concerns about Red Sea shipping disruptions, which matters because crude is one of Canada’s largest exports. Higher oil prices tend to support the Canadian dollar, though geopolitical uncertainty is adding volatility.

What Is CUSMA’s Current Status and Why Does It Matter Here?

The United States formally declined to renew the Canada-United States-Mexico Agreement during its mandatory joint review on July 1, 2026. The agreement remains in force through July 2036, but the non-renewal triggered annual reviews and opened a period of negotiating uncertainty that has weighed on the Canadian dollar and cross-border trade sentiment.

Did Other Recent U.S. Labor Data Already Hint at Friday’s Report?

The ADP Employment Change report showed only 44,000 private-sector jobs added in July, well below the 75,000 consensus. JOLTS Job Openings held at 7.4 million in June. Initial Jobless Claims released Thursday rose only slightly to 199,000 from 198,000, below the 202,000 forecast, suggesting a gradual rather than sharp labor market slowdown.

Jordan Reynolds on How to Batch a Week of Content in One Hour

By: Editorial Staff, STAGE IIX

Social media strategist Jordan Reynolds shares the content batching system she uses to help entrepreneurs create consistent, authority-building content without spending hours online every day.

For many entrepreneurs, social media isn’t difficult because they lack ideas. It’s difficult because they approach content as a daily task instead of a repeatable business system.

Every morning begins the same way.

“What should I post today?”

That single question costs more time than most business owners realize. It interrupts client work, pulls attention away from revenue-generating activities, and turns content creation into a constant mental drain.

According to Jordan Reynolds, that’s the wrong way to think about content entirely.

A social media strategist and content systems expert, Jordan Reynolds helps entrepreneurs, coaches, speakers, authors, founders, and service-based business owners build sustainable marketing systems that make consistency possible without requiring them to live on social media. Rather than teaching people to post more, her methodology focuses on creating decision-free content systems that simplify the creative process while strengthening brand authority.

Her work spans one-on-one coaching, self-paced courses, content retreats, and done-for-you social media management.

The result isn’t simply saving time. It’s building a marketing system that supports the business instead of competing with it.

“Most entrepreneurs don’t have a content problem. They have a systems problem.”

Why Content Feels Harder Than It Should

Many business owners assume they struggle with content because they aren’t creative enough.

Jordan Reynolds believes the opposite.

Most entrepreneurs have years of experience, countless client conversations, and valuable expertise to share. The problem isn’t a lack of knowledge. It’s the number of decisions they’re forced to make every time they create content.

They need to decide what topic to cover.

Then what format to use.

Then whether it should be educational, personal, or promotional.

Then what to say in the first three seconds.

Then what call to action to include.

Then how to edit it.

Then when to publish it.

By the time those decisions are made, creating content feels exhausting before the camera is even turned on.

Decision fatigue doesn’t just slow content creation. It reduces consistency.

Reynolds argues that consistency isn’t created through more discipline. It’s created by removing unnecessary decisions before the creative process begins.

“The goal isn’t to become more creative. The goal is to make creativity easier to access.”

Content Systems Beat Content Hustle

The social media industry often rewards volume.

Post every day.

Follow every trend.

Film more.

Publish more.

While Jordan Reynolds agrees that consistent content matters, she believes volume only works when it’s supported by a strong foundation.

Without clear messaging, repeatable workflows, and systems behind the scenes, posting more simply creates more work.

Volume is an amplifier.

If the strategy is clear, volume accelerates growth.

If the strategy is confusing, volume simply amplifies confusion.

That’s why Reynolds teaches clients to build content systems before increasing output.

A content system removes guesswork from the process. Instead of reinventing content every morning, business owners follow the same repeatable workflow each week.

The system stays the same.

Only the ideas change.

The Four Foundations Every Content System Needs

Before Jordan Reynolds teaches clients how to batch content, she focuses on four foundational elements. Without them, even the fastest batching session produces inconsistent marketing.

1. Know Your Content Pillars

The first step is deciding what your business should become known for.

These are your content pillars, the core conversations your audience should consistently associate with your brand.

For a business coach, those topics might include leadership, sales, operations, and team building.

For a wellness coach, they could be nutrition, habits, movement, and mindset.

For a social media strategist like Jordan Reynolds, the pillars include content systems, social media strategy, personal branding, authority marketing, and content planning.

When your pillars are clearly defined, content creation can feel less demanding because you’re no longer searching for random ideas. You’re simply exploring new angles within topics you already own.

Repetition builds recognition.

Recognition builds authority.

2. Every Piece of Content Has One Job

One of the defining principles of Jordan Reynolds’ methodology is simple. Every piece of content has a job.

Many creators expect one Reel to educate, entertain, build trust, generate leads, and sell an offer all at the same time.

That rarely works.

Instead, Reynolds encourages entrepreneurs to assign each post one primary objective.

Some posts exist to attract new people.

Some establish expertise.

Some deepen relationships with an existing audience.

Others invite people into an offer.

When every post has a purpose, planning becomes easier because the creator understands exactly what success looks like for that piece of content.

“Content performs better when every piece knows its job.”

3. Your Profile Should Finish What Your Content Starts

Great content creates curiosity.

Your profile should create clarity.

After someone watches a Reel or reads a carousel, they almost always visit the creator’s profile before deciding whether to follow, subscribe, or purchase.

If the profile doesn’t clearly explain who the business helps, what it offers, and what someone should do next, valuable attention disappears. Reynolds applies the same standard to her own Instagram profile.

Strong content deserves an equally strong destination.

4. Build Systems That Capture Attention

Content creates traffic.

Systems create customers.

Reynolds encourages business owners to think beyond the post itself. What happens after someone comments, clicks, or requests a resource matters as much as the post that prompted it.

Without these systems, attention often stops at the post.

With them, attention becomes momentum.

The One-Hour Content System

Once those foundations are in place, batching becomes surprisingly simple.

Jordan Reynolds’ One-Hour Content System isn’t about rushing through content.

It’s about organizing decisions so creativity can happen without interruption.

Minutes 0–10: Plan the Week

The first ten minutes are dedicated to planning.

Instead of deciding what to post each day, Reynolds recommends choosing all of the week’s topics at once.

She begins with content pillars and selects one idea for each planned post.

For many entrepreneurs, a five-post week provides the right balance between consistency and sustainability.

A typical week might include:

• One educational insight

• One personal story

• One common mistake

• One client example or behind-the-scenes moment

• One offer or invitation

Notice that the focus isn’t on formats. It’s on purpose.

By the end of the first ten minutes, every post already has a direction before a single video is recorded.

Minutes 10–20: Write the Hook and the Call to Action

The next ten minutes focus on two of the most important parts of every post, the beginning and the end.

Jordan Reynolds encourages creators to avoid scripting every sentence.

Instead, she identifies the hook first.

A strong hook creates curiosity, challenges a common belief, or immediately identifies a problem the audience recognizes.

Examples include:

“You’re not inconsistent because you’re lazy.”

“Posting more won’t fix unclear messaging.”

“Here’s why content feels harder than it should.”

Once the hook is written, the creator decides how the audience should respond.

Should they save it, share it, comment a keyword, or download a resource?

Every call to action should match the job of the content.

By the twenty-minute mark, the week has direction, structure, and intentionality.

The remaining forty minutes become execution instead of decision-making.

Minutes 20–40: Record All of Your Content in One Sitting

With the strategy complete, it’s time to hit record.

This is where most people expect content creation to take the longest, but Jordan Reynolds has found the opposite. Recording tends to move faster because the thinking has already been done.

Rather than scripting every word, Reynolds recommends using a simple three-part framework for every video:

• Start with the hook.

• Teach one clear idea.

• End with one next step.

This approach keeps videos conversational while ensuring they stay focused.

Many entrepreneurs try to create five different versions of themselves in a single week. Educational one day, funny the next, then inspirational, then highly polished.

Consistency doesn’t come from changing your personality.

It comes from consistently communicating your expertise.

By recording several videos in one sitting, creators stay in the same mental state, maintain a consistent message, and reduce the time spent setting up lights, adjusting cameras, or getting comfortable on screen.

“The camera shouldn’t decide what you teach. Your strategy should.”

Minutes 40–50: Capture B-Roll You Can Reuse

Not every piece of content requires talking to the camera.

Some of the highest-performing posts rely on simple supporting footage paired with valuable insights.

During the next ten minutes, Reynolds recommends capturing everyday moments that naturally reflect your business.

This might include:

• Working at your desk.

• Preparing for a client call.

• Writing in a notebook.

• Packing for a speaking event.

• Reviewing analytics.

The goal isn’t to manufacture a perfect lifestyle.

It’s to build a library of authentic footage that can support future voiceovers, educational captions, Stories, and text-based Reels.

Instead of filming every day, entrepreneurs create assets they can reuse for weeks.

The message changes.

The footage doesn’t always have to.

Minutes 50–60: Prepare the Business Behind the Content

The final ten minutes are often overlooked, but Jordan Reynolds believes they determine whether content generates attention or actual business results.

Publishing isn’t the finish line.

It’s the beginning of the customer journey.

Before scheduling content, Reynolds encourages business owners to ask a few simple questions.

If someone discovers this post, what happens next?

If they visit the profile, is it immediately clear who the business serves?

If they comment on a keyword, does an automated system deliver the promised resource?

Tools like ManyChat can automatically deliver a guide, checklist, training, or free resource through Instagram direct messages after someone comments on a post.

Email automation can continue educating new subscribers.

A well-designed landing page can move interested followers toward a consultation, digital product, or membership.

Content creates awareness.

Systems capture opportunity.

“Your content should create attention. Your systems should know what to do with it.”

Why Content Systems Matter More Than Ever

As search continues to evolve, consistency has become more valuable than constant visibility.

Search engines and AI-powered platforms increasingly recognize expertise through repeated, well-organized information across a specific subject.

High-volume publishing works when messaging is clear, content pillars are well defined, every post has one primary job, and the systems behind the scenes are prepared to capture demand. Without those elements, more content rarely creates better results. It simply creates more activity.

Jordan Reynolds encourages entrepreneurs to think less like content creators and more like category leaders.

The objective isn’t to talk about everything.

It’s to become known for something.

Authority isn’t built in one viral Reel.

It’s built through hundreds of intentional moments that communicate the same expertise from different angles.

“People don’t remember everything you post. They remember what you consistently stand for.”

A Better Way to Think About Content

The promise of batching a week’s worth of content in one hour isn’t really about the hour.

It’s about what that hour makes possible.

Instead of interrupting every workday to think about social media, entrepreneurs regain the freedom to focus on serving clients, developing offers, leading teams, or simply creating space to think strategically.

Content stops feeling reactive.

It becomes operational.

That’s the difference between a creator constantly trying to stay visible and a business owner building an authority brand.

The businesses that grow consistently aren’t always creating the most content.

They’re creating the clearest systems.

Key Takeaways

• A repeatable content system is more valuable than relying on daily inspiration.

• Define clear content pillars so your audience consistently associates you with your areas of expertise.

• Every piece of content should have one primary job: discovery, authority, connection, or conversion.

• Batch strategy before production. When the decisions are made first, creating content can become faster.

• Strong profiles, clear offers, and systems like ManyChat are designed to keep content working after it publishes.

• Volume works best when it amplifies a clear strategy, not when it compensates for the lack of one.

About Jordan Reynolds

Jordan Reynolds is a social media strategist, content systems expert, and personal brand educator who helps entrepreneurs, coaches, speakers, authors, founders, and service-based business owners build authority through sustainable content marketing. Known for her systems-first approach, Reynolds specializes in content batching, content strategy, personal branding, profile optimization, and marketing systems that help businesses create consistent content without spending hours online every day. Her methodology focuses on helping business owners simplify their marketing, strengthen their authority, and build brands through clarity, consistency, and strategic content systems.

She also hosts Rewrite the Rules, a weekly podcast for women redefining success on their own terms.

Alex Mayer Discusses Recent Price Cuts in Rochester, Minnesota, and What Buyers Should Consider

By: KeyCrew Media

Showing volume in Rochester, Minnesota has dropped to roughly one-fifth of what it was two months ago, according to Alex Mayer, a real estate professional in the market. That pace is forcing sellers to cut prices faster than most expected.

80 New Listings, 66 Price Cuts

In a single seven-day snapshot of Rochester’s single-family home market, Mayer counted 80 new or coming-soon listings alongside 66 price reductions. That combination, roughly one price cut for every 1.2 new listings, indicates sellers who priced confidently two months ago are now being forced to recalibrate.

“If we see one good showing a week right now, you are hitting par,” Mayer says. For sellers still operating with a hot-market mindset, the gap between expectation and reality is proving costly.

Mayer argues that the market has already shifted, but consumer behavior hasn’t caught up. He says the news cycle typically lags real market conditions by six to eight weeks. In his view, buyers who move before the media narrative shifts encounter less competition and more negotiating leverage than they would once the story is widely reported.

“All the buyers will come flooding back into the market,” Mayer says, describing what he expects once consumer confidence catches up to conditions. “Not saying that’s what’s gonna happen. What I’m saying is there seems to be this kind of pendulum that happens within these things.”

Strategy Depends on the Specific Situation

Mayer’s central argument is that the right strategy depends entirely on the specific situation a client occupies at this specific moment, and that most consumers are working from information that is either too general, too old, or too disconnected from local conditions to be useful.

“The short answer to almost every question in real estate is it depends,” Mayer says. “My job as the real estate professional is to explain to them what it depends on.”

He draws a sharp distinction between two buyer scenarios in the current Rochester market. A buyer looking at a day-one listing priced 5 to 10 percent below market value (a deliberate strategy some listing agents use to generate multiple offers) faces a completely different calculus than a buyer looking at a property that has been sitting for three or more weeks with no offers. Treating both situations the same way, Mayer argues, is how buyers either overpay or miss opportunities.

For sellers, the calculus has also shifted. Mayer says he is now advising active sellers who haven’t received an offer within three weeks to consider a price reduction immediately, and to be prepared to seriously evaluate offers that come in below even that reduced price.

The Contingent Purchase Problem

One of the more complex scenarios Mayer describes involves sellers who need to sell their current home before they can financially close on a new one. In a slowing market, this creates compounding risk. The buyer is emotionally invested in a new property while carrying uncertainty about whether their existing home will sell in time.

Mayer’s approach in these situations involves pre-loading the marketing materials, including professional photography, video, and a documented pricing strategy, before making an offer on the target property. He then presents that preparation directly to the listing agent on the other side as evidence of commitment and marketability.

“Listing agents and sellers love to see that,” Mayer says, “because it’s showing things are more likely to sell and sell fast, and that you are committed to selling fast.”

He also outlines a scenario where a buyer can financially close on a new home without first selling the existing one, then execute a mortgage recast after the sale closes, reducing the monthly payment by applying the sale proceeds as a lump-sum principal reduction. These are the kinds of situation-specific options, Mayer argues, that only emerge from a genuine strategic conversation rather than a generic market briefing.

Where AI Falls Short

Mayer points to AI tools as a useful starting point but warns that the errors tend to involve exactly the kind of neighborhood-level nuance that matters most to buyers making location decisions.

“Artificial intelligence is great 80% of the time,” Mayer says. “The 20% of the time that they are wrong, they are really wrong.”

His example: a relocating buyer searching near the Mayo Clinic in Rochester might receive accurate median price data from an AI tool but miss entirely the pricing differences between Pill Hill, Northwest Rochester, Bamber Valley, and Slatterly Park, neighborhoods that carry meaningfully different price points. A buyer told that everything in Rochester is within a 15-minute drive might not realize that walkability to the Mayo Clinic narrows options to a specific, higher-priced area.

In a market where conditions are shifting faster than published data can track, Mayer says buyers and sellers who rely on general information rather than current, local strategy risk acting on a version of the market that no longer exists.

Alex Mayer is a full-time Rochester, MN real estate agent, a 4X winner of Best Real Estate Agent in Rochester, MN, with hundreds of five-star reviews. His core values are Education, Communication, and Responsiveness, which guide every part of his business. He has a “Direct Representation Model,” meaning his clients work directly with him, not a large team with junior agent handoffs. He focuses on making sure clients understand what to expect, how to operate, and what the Rochester, MN real estate market requires. He specializes in first-time homebuyers, Mayo Clinic and other relocating buyers, and Rochester MN sellers, including move-up, downsizing, and estate sales. Alex is also known for his Alaskan malamute dogs, Atlas and Kaia, who are featured in much of his local branding.

Disclaimer: This article is based on information provided by the expert source cited above. It is intended for general informational purposes only and does not constitute legal, financial, or real estate advice. Readers should conduct their own research and consult qualified professionals before making any real estate or financial decisions.

The Business of Self-Publishing and How Authors Are Turning Books Into Long-Term Assets

For independent authors, publishing is no longer only a creative milestone. It is becoming a business decision shaped by positioning, distribution, marketing, and long-term reader engagement.

Self-publishing has changed the economics of authorship. A book is no longer treated only as a personal accomplishment or a one-time release. For many writers, entrepreneurs, coaches, consultants, and subject-matter experts, it has become a product, a credibility asset, and a long-term marketing tool that can support a wider professional ecosystem.

This shift has made the author more business-minded. Writers consider audience demand, category positioning, production quality, launch strategy, and post-publication visibility before the manuscript reaches the final stage. The authors who treat publishing as a complete business process tend to approach their books differently from those who focus only on uploading a file and waiting for sales to happen.

Self-Publishing Has Become a Market Entry Strategy

The rise of self-publishing has opened the door for more authors to enter the market without waiting for traditional gatekeepers. That access, however, has also increased competition. Readers now compare independently published books with traditionally published titles in the same digital storefronts, search results, and recommendation feeds. The gap between a book that looks professional and one that feels unfinished can directly affect reader trust.

This is why many authors are investing in book publishing services that help them move beyond basic publication. Formatting, cover design, ISBN guidance, distribution setup, platform readiness, and metadata all contribute to how a book appears in the marketplace. A strong publishing process gives the book a foundation to compete, while weak execution can limit its potential before marketing even begins.

Book Writing House works in this space by supporting authors through key stages of the publishing journey, from manuscript preparation and editing to design, publishing, and visibility planning. For authors who view their work as a business asset, that structured support can be valuable because it connects the creative side of authorship with the commercial realities of release.

Monetization Starts Before the Book Is Published

Many authors think monetization begins after the book is live. In reality, revenue potential is shaped much earlier. The topic, audience, title, cover direction, category selection, pricing model, and launch positioning all influence whether a book can attract attention and convert interest into sales.

For entrepreneurs and professionals, a book may create value beyond royalties. It can help support speaking opportunities, consulting inquiries, course enrollments, podcast invitations, media visibility, and lead generation. For fiction and genre authors, it may become the beginning of a series, a reader community, or a catalog strategy. In both cases, the book can work more effectively when it is connected to a larger author brand rather than treated as a standalone product.

This is where the business of self-publishing becomes more strategic. Authors need to identify what the book is meant to do. Is it designed to sell directly to readers, build authority, support a business offer, create long-term brand recognition, or open new professional doors? The answer affects how the book should be produced, positioned, and promoted.

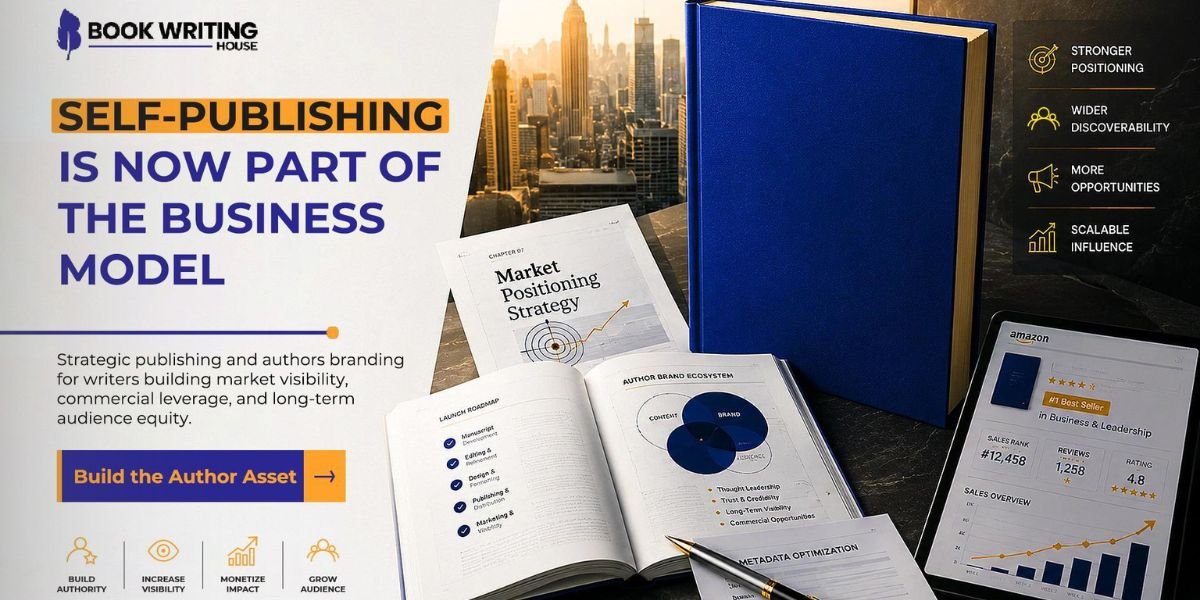
Photo Courtesy: Book Writing House

Marketing Is No Longer Optional for Independent Authors

Publishing makes a book available. Marketing helps make it discoverable. That difference matters because availability alone does not create demand. A book may be live on major platforms, but without awareness, reviews, audience targeting, and consistent visibility, it can easily get lost among thousands of competing titles.

Professional book marketing services can help authors think through the channels that matter most for their goals. These may include social media campaigns, Amazon visibility, reader outreach, review building, author branding, website traffic, press opportunities, and content-driven promotion. The strongest campaigns are not only about creating noise. They are about placing the book in front of the right audience with the right message.

Independent authors are increasingly learning that marketing should not be treated as a last-minute add-on. It should be planned alongside publication. A business book, for example, may need visibility on LinkedIn and in professional media. A memoir may rely on emotional storytelling and community engagement. A self-help book may need content that builds trust and reader testimonials. A children’s book may depend on parent-focused channels, educators, and visual presentation.

Each category has its own market behavior. Understanding that behavior can help authors avoid generic promotion and focus on strategies that fit their audience.

The Author Brand Is Part of the Revenue Model

In the current publishing environment, readers often buy into more than a title. They buy into the author’s voice, story, expertise, and credibility. This is especially true for business authors, coaches, consultants, health professionals, educators, and public figures whose books are tied to their professional identity.

An author brand can make future books easier to launch, improve reader retention, strengthen media opportunities, and support additional income streams. It gives the book a context. Without that context, even a well-written title may struggle to build momentum beyond its initial release.

For this reason, many authors are now thinking like founders. They are building websites, email lists, social proof, media profiles, speaking platforms, and content ecosystems around their books. The book becomes the central product, while the author’s brand serves as the structure that keeps the audience engaged.

A Professional Publishing Partner Can Help Authors Build for Longevity

The self-publishing market rewards independence, but independence does not mean authors must handle every technical and strategic decision alone. Many writers have strong ideas, personal stories, or professional knowledge, but they may not understand how to prepare a book for a competitive marketplace. That is where experienced publishing and marketing support can reduce friction.

Book Writing House positions itself as a full-service support system for authors seeking guidance throughout the publishing lifecycle. Its services include writing, editing, formatting, cover design, publishing, and marketing support. For authors focused on monetization, the value is not only in completing the book but in building a release that looks professional, reaches readers, and supports a broader author identity.

As the publishing market continues to evolve, the authors who benefit most will likely be those who think beyond the manuscript. They will treat their books as assets that require planning, packaging, distribution, and promotion. They will understand that sales are influenced by trust, visibility, presentation, and consistency. Most importantly, they will see publishing as the beginning of a business journey rather than the end of a writing project.

The Bottom Line

Self-publishing has given authors more control than ever, but it has also made the author more responsible for business outcomes. A well-written book that is poorly positioned may not reach its audience. A book that is available but not marketed may not generate momentum. A book that is launched without a brand behind it may struggle to create lasting value.

For modern authors, the opportunity is clear: publish with intention, market with strategy, and build an author brand that can keep working long after launch. In that model, the book is more than a product on a digital shelf. It can become a revenue asset, a credibility tool, and a long-term growth platform.

Multi-Generational Buyers Are Driving Demand for Large Properties in Connecticut’s Tri-State Region

By: KeyCrew Media

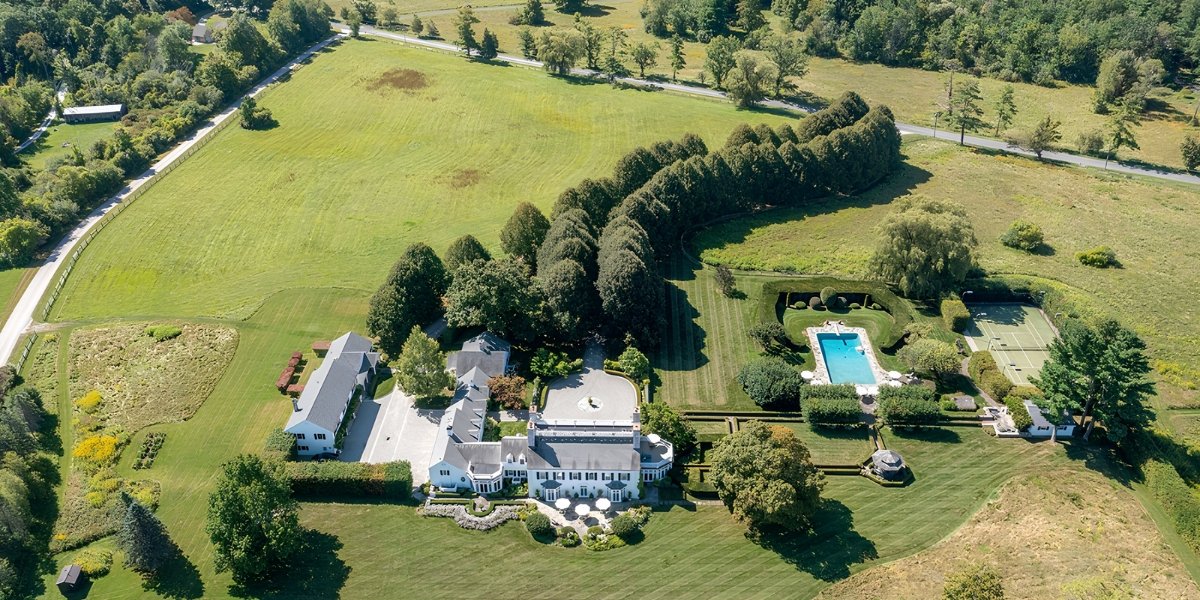
Families spanning three generations are purchasing 100-acre properties in northwest Connecticut, the Hudson Valley, and the Southern Berkshires, not as investments or trophy assets, but as shared living arrangements designed around privacy and proximity. According to Elyse Harney Morris, a principal broker at Elyse Harney Real Estate, this buyer profile has grown substantially since the pandemic and now accounts for some of the largest transactions in her market.

A New Motivation for Large-Acreage Purchases

Harney says the multi-generational buyer emerged in her market during the pandemic, when families began rethinking how they wanted to live together. These buyers want a single property large enough to accommodate grandparents, parents, and grandchildren while preserving individual space.

“This is a newer phenomenon for us, and it really came about since the pandemic, where I think people are making a lifestyle choice and wanting to bring grandparents, parents, and the grandkids, and to be able to have that privacy, to have land to explore, to teach your kids how to fish or raise bees,” Harney says.

The scale is significant. Harney points to two recent transactions in the Berkshires, both currently under agreement, each involving approximately 100 acres and each completed within a two-week window. One buyer came from Boston, the other from New York. Harney says these deals represent a pattern she is seeing with increasing regularity.

Why This Market Attracts Multi-Generational Buyers

The tri-state region offers large parcels with rolling hills, water features, and agricultural history in a way that markets closer to major cities cannot. Strict zoning and active land conservation protect the surrounding landscape from rapid development, a quality that matters to families planning to hold a property across decades.

Harney also points to the region’s four-season lifestyle as a draw for families creating a shared anchor. Winter skiing at Catamount (which recently invested heavily in a new lodge, additional runs, and improved snowmaking), summer hiking on the Appalachian Trail, and year-round cultural programming at venues like Tanglewood give a large property genuine utility beyond a single season.

“Those really special, unique properties that are on a lake with tremendous views, multi-generational properties, those are still pulling off strong, strong numbers,” Harney says. While the $2 million to $3 million range represents the most active segment of the broader market, multi-generational buyers are operating above that threshold and are less price-sensitive.

The Value Equation at the Upper End

Harney argues that large-acreage properties in this region offer compelling value compared to alternative luxury markets. The Hamptons, Jackson Hole, and comparable destinations command higher prices for properties with less land and less privacy. The tri-state market offers 100-acre parcels within two and a half hours of New York City.

“When you compare us to the Hamptons, when you compare us to Jackson Hole, it’s a home that you can get to every week,” Harney says. She identifies the two-and-a-half-hour drive as a practical ceiling for families with children, and the Salisbury area falls within that radius from both New York and Boston.

For multi-generational buyers, accessibility functions differently than it does for weekend visitors. When a property must work for grandparents who may not travel frequently and grandchildren who need to return to school on Monday, reaching it in under three hours from a major city is a prerequisite rather than a convenience.

California buyers also represent a growing segment. Harney says they tend to seek more modern contemporary architecture, a style less common in Litchfield County but increasingly available through new construction on the New York side in the Hudson Valley. She describes one couple displaced by the California fires who are building a contemporary home in the region and plan to live there full-time.

How the Firm Serves Cross-Border Buyers

Harney’s firm operates across all three states (Connecticut, New York, and Massachusetts), a structure built by her mother, who founded Elyse Harney Real Estate and was among the first agents in the area to hold licenses in all three states. That tri-state capability matters for multi-generational buyers evaluating properties across state lines.

“We are able to not be pigeonholed into one state, several towns,” Harney says. “Ever since COVID, we are seeing more and more people who really do not care where. They’re looking for that lifestyle, that property that is going to work for their family.”

Each town in the region has a distinct character. Harney describes Salisbury, Connecticut, as a walkable community where families choose to live in town so children can reach restaurants, the lake, and tennis courts on foot. The Hudson Valley offers more acreage and a farm-to-table culture built around local agriculture. The Southern Berkshires provide cultural institutions and mountain access. For buyers who have not yet chosen a specific location, Harney recommends renting for six months before purchasing, a trial period that reveals what daily life looks like on a Tuesday, not just a weekend.

For families making a multi-generational purchase, the ability to compare a 100-acre parcel in the Berkshires with a comparable property in Litchfield County or the Hudson Valley through a single firm reduces the complexity of the decision. As more families who made pandemic-era lifestyle changes seek permanent arrangements rather than weekend retreats, demand for large protected parcels within commuting distance of major cities may hold steady, even as the broader market correction suggests otherwise.

About The Author

Elyse Harney Morris is a principal broker at Elyse Harney Real Estate, an independent brokerage founded in 1987 and operating across Connecticut, New York, and Massachusetts. She specializes in significant country estates, historic farms, and conservation properties across the Litchfield Hills, Hudson Valley, and Southern Berkshires.

Manhattan Office Availability Falls to Six-Year Low as 2026 Leasing Volume Tracks Toward a Level Not Seen Since 2000

Manhattan’s commercial office market absorbed 3.87 million square feet of space in July 2026, pushing year-to-date leasing volume to 26.66 million square feet and putting the borough on pace for its strongest annual total in more than a quarter century, according to Colliers’ latest monthly report released August 3. Available office inventory dropped to 66.24 million square feet, the lowest level since September 2020, while sublease supply hit a mark not seen since August 2019. For investors, landlords, and corporate tenants tracking the trajectory of one of the world’s most closely watched commercial real estate markets, the data points to a structural tightening that has moved well past early-stage recovery.

  • July leasing velocity rose 22% over June and 28.4% year-over-year, led by commitments from Anthropic, NBCUniversal, and Aon.
  • Available office space has declined 32% from the post-pandemic peak of 98 million square feet in February 2024, compressing at a rate that has accelerated in each of the past three quarters.
  • Sublease inventory shrank by 700,000 square feet in a single month, removing a pricing lever that tenants used to negotiate below-market deals during the 2021 to 2024 recovery period.
  • Average asking rents reached $78.03 per square foot, within 1.8% of the $79.47 recorded in March 2020, the last data point before pandemic-era disruptions reshaped the market.
  • AI companies leased 670,000 square feet in Q1 2026 alone, more than a third of all technology-sector activity, with Q2 volume climbing further to 800,000 square feet.
  • Approximately 5.5 million square feet of positive absorption was recorded during the first half of 2026; if that pace holds, pre-pandemic occupancy levels could be restored within two years.

The Supply Picture Has Shifted Faster Than Most Forecasts Predicted

The headline number, 66.24 million square feet of available space, represents a market that has compressed by nearly a third in just over two years. At the post-pandemic peak in February 2024, Manhattan’s office inventory overhang stood at 98 million square feet, a figure that led some analysts to project a decade-long recovery timeline. That projection has not held. The current availability rate is declining across all three major submarkets that Colliers tracks: Midtown, Midtown South, and Lower Manhattan. Each has shed roughly a third of its surplus since its respective post-pandemic high, a convergence that Frank Wallach, executive managing director of research at Colliers, described as remarkable given how differently the three markets operate.

Midtown’s overall availability now sits just 1.6 percentage points above its March 2020 level. Midtown South has tightened more aggressively, with availability dropping by about half a percentage point in July alone to 12.2%. That kind of single-month compression is atypical for any submarket and suggests that demand is absorbing space faster than new inventory or sublet returns can replenish it.

The drivers behind the compression are threefold. Healthy tenant demand, particularly from technology and AI firms, accounts for the largest share. Office-to-residential conversions have physically removed some buildings from the commercial pipeline, though that trend has slowed in recent months amid increased city regulatory scrutiny. And the sublease market, once a flood of discounted space that undercut direct landlord offerings, is draining rapidly. July’s 700,000-square-foot reduction in sublease inventory was partly driven by Snap’s 199,000-square-foot sublease at Vornado’s Penn 2, which absorbed one of the more prominent blocks sitting on the market.

AI Firms Have Become a Structural Force in Tenant Demand

Artificial intelligence companies are no longer a novelty footnote in Manhattan leasing reports. AI tenants accounted for more than a third of all technology-sector leasing in Q1 2026, absorbing 670,000 square feet, according to Colliers. That figure jumped from a 12% share in 2025. By Q2, AI leasing volume climbed to 800,000 square feet, surpassing the combined total for all AI deals across Manhattan in the whole of 2025.

July’s largest single transaction reflected this trend. Anthropic’s 465,630-square-foot lease for the entirety of AEW Capital Management’s 330 Hudson Street building in Hudson Square anchored Midtown South’s outsized share of the month’s activity. The AI company, which builds the Claude chatbot, plans to double its New York workforce to approximately 1,000 employees by year-end 2026, with the 16-story building capable of housing 1,700 workers at full occupancy.

Anthropic’s deal is part of a broader pattern. OpenAI leased 90,000 square feet at the Puck Building in SoHo. EliseAI signed a 109,000-square-foot lease at 401 Fifth Avenue near Grand Central. Legal AI startup Harvey committed to 185,000 square feet at One Madison Avenue. These firms tend to lease large, contiguous blocks of Class A space with long-term commitments, which tightens the premium end of the market and pushes other tenants into Class B and Class A-minus buildings that had previously struggled to attract demand. First-half 2026 data from Colliers and Avison Young confirms a notable rebound in Class B leasing, a spillover effect that is broadening the recovery beyond trophy towers.

The comparison to historical precedent is instructive but also carries limits. During the dot-com era’s peak in early 2000, internet companies captured roughly a quarter of all Manhattan office leasing and briefly overtook financial services as the city’s largest tenant category. AI firms currently represent only 2% to 3% of total Manhattan leasing by volume, even as their growth rate commands disproportionate attention. The question for the market is whether AI demand continues scaling or plateaus as the sector matures and capital deployment normalizes.

Rent Recovery and the Disappearing Tenant Leverage

Average asking rents at $78.03 per square foot in July place the market within striking distance of the $79.47 recorded in March 2020. Midtown South has already surpassed its pre-pandemic rent levels, driven by constrained supply and premium demand from AI and technology tenants competing for a shrinking pool of quality space.

The sublease market’s contraction is a key factor in the rent dynamic. Sublease space, typically offered at significant discounts to direct asking rents, gave tenants pricing leverage throughout the pandemic recovery. At its peak in late 2022, Manhattan’s sublease inventory exceeded 22 million square feet. It has since been cut by more than half, and all three major submarkets recorded sublease reductions in July. As that inventory drains, one of the primary mechanisms tenants used to negotiate below-market deals is disappearing, shifting pricing power back toward landlords.

For investors evaluating Manhattan commercial real estate exposure, the rent trajectory carries direct implications for net operating income and cap rate compression. Publicly traded REITs with significant Manhattan office portfolios, including SL Green Realty and Vornado Realty Trust, have seen leasing activity data feed into revised earnings outlooks. SL Green projected over 900,000 square feet of leasing in Q1 2026 alone, a company record, with AI tenants accounting for a growing share of major transactions.

Absorption Pace Faces a Sustainability Test

Manhattan absorbed approximately 5.5 million square feet of office space during the first half of 2026, according to Colliers. If demand continues at that rate, the market could return to March 2020 occupancy levels within two years. But sustaining this pace presents challenges. The large-block leases that drove 2025 and early 2026 activity, transactions in the 200,000-to-500,000-square-foot range from firms like Anthropic, NBCUniversal, and Bank of America, are not easily replicated quarter after quarter. The pool of tenants seeking that scale of space is finite, and many of the most active firms have now committed to long-term deals.

Year-to-date leasing volume through July is running 12.8% ahead of the same period in 2025. The full-year 2025 figure was already the strongest since 2019, supported by 15 million square feet of positive absorption. Matching or exceeding that level in 2026 would require continued momentum in the mid-market segment, where leases between 10,000 and 50,000 square feet have quietly kept the pipeline moving even as headline deals capture most of the attention.

Wallach characterized the market as “on solid footing” and “moving in the right direction” but stopped short of declaring a full recovery. The data supports that measured read. With availability still above pre-pandemic norms in two of the three major submarkets, and with conversion projects and economic uncertainty as variables, the trajectory is favorable but not guaranteed.

FAQs

What Is Driving Manhattan’s Office Leasing Recovery in 2026?

Three forces are converging: strong tenant demand led by AI and technology firms, a shrinking sublease market that has removed below-market pricing options, and office-to-residential conversions that have physically reduced available commercial inventory. AI companies leased 800,000 square feet in Q2 2026 alone, more than all AI deals in Manhattan throughout 2025.

How Close Are Manhattan Office Rents to Pre-Pandemic Levels?

Average asking rents reached $78.03 per square foot in July 2026, within 1.8% of the $79.47 recorded in March 2020. Midtown South has already exceeded its pre-pandemic rent levels. The sublease market’s contraction is accelerating the rent recovery by reducing the pool of discounted space available to tenants.

What Does the Manhattan Office Market Recovery Mean for REIT Investors?

Tightening availability and rising rents have direct implications for net operating income at publicly traded landlords with Manhattan exposure. SL Green Realty reported a record 900,000 square feet of leasing in Q1 2026. As sublease leverage disappears and occupancy rates climb, cap rate compression and improved NOI could support revised earnings outlooks for Manhattan-focused office REITs.

Is the Current Leasing Pace Sustainable Through the Rest of 2026?

Year-to-date volume is running 12.8% ahead of 2025, which was already the strongest year since 2019. Sustaining the pace will depend on continued mid-market leasing activity in the 10,000 to 50,000 square foot range, as the supply of large-block transactions available to anchor quarterly numbers is finite. Colliers estimates that if absorption continues at its first-half rate, pre-pandemic occupancy levels could be restored within two years.

Understanding Your Rights When Dealing With Debt Collectors

By: Audrey Denise B. Cachuela

An unknown number flashes on the screen, and before a single word gets exchanged, the caller already holds most of the power in that conversation. They know the account balance. They know whatever version of the history they were handed when the debt got sold to them… and they know which phrases tend to make people say yes faster. The person picking up, meanwhile, might be hearing about this specific balance for the first time in months, sometimes years, with no real idea whether the number being quoted is even correct.

That imbalance is the real engine behind debt collection anxiety, and it explains why understanding your debt collection rights can flip an entire phone call on its head. Federal law hands consumers specific protections the moment a third-party collector makes contact, protections most people never learn until they are already mid-conversation and rattled.

This information is rarely taught anywhere, in school or otherwise, so most people build their understanding of debt collection from instinct and secondhand stories instead of anything grounded in consumer protection laws. That missing piece of practical knowledge is exactly why so many people make quick decisions during a call that they later regret, simply because nobody explained the rules of the game beforehand.

Amber Duncan has spent more than 17 years working inside that exact situation. She filed for bankruptcy in 2008 during the mortgage industry collapse, rebuilt from there, and has since helped negotiate and settle more than $100 million in consumer debt, primarily by working through debt settlement options for credit card balances, through Life After Debt, the company she founded.

The protections outlined here cover what a collector legally has to disclose as part of the debt collection process, how urgency gets used as a pressure tactic, and how to respond to a debt collection call without panic, starting with the specific rights every consumer already has under federal law.

Why Debt Collection Rights Change The Whole Conversation

FDCPA rights come from the Fair Debt Collection Practices Act, the federal law that makes it illegal for debt collectors to use abusive, deceptive, or unfair tactics when pursuing a balance, and that caps how often and when a collector can contact someone about the same debt (Source: FTC, 2025).

These debt collector laws exist precisely because a call landing on your phone does not confirm that every detail on the other end is accurate: accounts get sold and resold between collection agencies, balances pick up interest and fees a consumer never agreed to, and paperwork gets duplicated or lost somewhere along that chain. The company calling might even carry a name nobody in the household recognizes, simply because it bought the account three agencies down the line, and that same confusion shows up in the complaint data. Complaints about being pursued for debts consumers say they never owed have remained the most common complaint category in federal debt collection data since tracking began in 2013 (Source: CFPB, 2026).

Debt collection complaints climbed sharply again last year too, jumping 86 percent to roughly 387,400 total (Source: CFPB, 2026). That kind of volume says something simple: this confusion is widespread among people dealing with collectors, and it rarely has anything to do with whether the underlying debt is real.

Federal rules require a collector to send a debt validation notice either during that first conversation or within five days of it, which answers the exact question of what information a debt collector must provide: the name of the creditor, the amount claimed, and instructions for disputing the account (Source: CFPB, 2024).

That single document turns a phone call into a paper trail, and it is the clearest way to verify a debt collection account before agreeing to anything. A consumer holding debt validation information can check who currently owns the debt, compare it against their own records, and confirm whether the amount matches anything they recognize. Requesting it in writing within the 30 day window after first contact also pauses collection activity on the disputed portion, since a debt collector cannot keep collecting without validation once that dispute is filed (Source: FTC, 2025).

Requesting this information keeps a consumer inside their legal rights while still moving toward resolving the account, and it works as the practical first step in learning how to dispute a debt that turns out to be wrong. A debt validation letter costs nothing to send and takes a few minutes to draft, and it changes the entire footing of the conversation from that point forward.

How Urgency Gets Used Against You

These protections only help if a consumer gets the chance to use them, and collection calls are built to move fast enough that most people never stop to check. A caller pushes for payment today, a letter carries a tight deadline, or an offer gets framed as available for a limited window only, even when nothing about the underlying account actually expires that fast. For someone already dealing with financial anxiety and debt, that pressure can read as proof that immediate action is required, and it can push people into handing over bank details or agreeing to payments their budget cannot actually support.

Slowing down at that exact moment changes the whole experience of dealing with debt collectors. A caller who wants the discomfort to end tends to agree to whatever gets said first, while a few minutes spent reviewing documents first turns the same call into a decision worth researching, phone still in hand and nothing signed yet.

Verifying a debt before paying it counts as ordinary due diligence and a basic exercise of consumer debt rights, the same instinct that makes someone double-check a medical bill or a repair estimate before writing a check.

Ignoring a legitimate debt carries its own consequences, since unresolved balances can get reported to credit bureaus, and depending on the type of debt and the state involved, a collector may have legal options for pursuing it further (Source: FTC, 2025). Consumers weighing a payment or a written acknowledgment on an older account should also know that state statute of limitations rules vary widely, and in some states a payment can reset the clock on how long a debt stays legally collectible. Anyone facing a lawsuit, wage garnishment, or real uncertainty about those timelines benefits from a conversation with a qualified attorney.

That responsibility works in both directions: a consumer who verifies an account and still owes the money is in a stronger position for creditor negotiation than someone who never checked at all, while a collector who cannot substantiate the debt loses whatever advantage the call started with.

The Real Advantage Behind Every Collection Call

Disclosure rules only go so far if people never get the chance to put them into practice within the debt collection process, and that distance between having a right and actually using one is where collectors keep their edge: they handle these calls constantly and know exactly how far the rules let them push, while a consumer, even one holding a validation notice, is usually working through the process for the first time, with no real script of their own to fall back on. That difference in repeated practice, as much as any difference in information, is what keeps so many people from pushing back even when they already know their rights.

Shame keeps a lot of people from asking for anything at all when dealing with debt collectors, since many worry that requesting an itemized balance or a validation letter will make them look difficult or make the situation worse somehow. Asking a collector to document what they are claiming is a completely ordinary part of resolving a serious financial matter, the same as asking a mechanic for a written estimate before authorizing repairs.

Different callers pursuing the same overdue balance can fall under very different sets of consumer protection laws. Federal protections under the FDCPA apply specifically to third-party debt collectors, companies collecting on behalf of a creditor or another business, and they cover personal debts such as credit card balances, medical bills, auto loans, student loans, and mortgages (Source: FTC, 2025). A creditor collecting its own debt directly, generally referred to as a first-party collector, falls outside those specific protections, and business debts are excluded from FDCPA coverage entirely (Source: CFPB, 2026). Many states add their own layer of protection through separate debt collection laws (Source: FTC, 2025). Knowing which category a caller falls into is often the first practical question worth asking, since it shapes exactly which protections are already in place before the conversation even starts.

A consumer does not need to raise their voice to change the tone of a collection call. The real advantage comes from knowing what to ask a debt collector before paying anything, starting with a plain statement that the account is under review and a request for validation information in writing, which accomplishes more than any argument would. Useful follow-up questions include the name of the current creditor, the name of the original creditor, an itemized breakdown of the balance, and confirmation that any proposed terms will arrive in writing before a payment gets authorized.

Once the account checks out, the conversation can move toward debt settlement options. Some collectors offer structured payment plans, and some negotiate a credit card debt settlement for less than the full balance. Settling for less than what is owed can still affect a credit report even after the debt itself is resolved (Source: FTC, 2025). The right path depends on income, the type and age of the debt, and a consumer’s broader financial picture, which is why a first call with a collector should begin with questions and a careful review of the details.

Turning Debt Collection Rights Into An Actual Plan

Understanding your rights under the FDCPA does not erase a balance overnight, and no honest conversation about debt collection rights that it will. It does change how a call gets handled, replacing panic with a short list of concrete questions and giving a consumer room to make a decision they can actually stand behind six months later.

A collector who ignores these rules faces real consequences. Consumers can report violations to their state attorney general, the FTC, or the CFPB, and federal law also allows a consumer to sue a collector directly within one year of the violation, with statutory damages up to $1,000 available even when actual financial harm is hard to prove (Source: FTC, 2025).

This kind of financial literacy compounds over time, since a consumer who understands their consumer debt rights during one call carries that same footing into the next conversation, whether it involves the same account, a completely different creditor, or a family member facing a similar situation down the road.

Life After Debt, the company Amber Duncan founded, offers a free 15-minute Clarity Call for anyone who wants a second set of eyes on a specific account, a chance to ask what a collector can and cannot legally do, and time to think through creditor negotiation and next steps before making any commitment.

The next unknown number does not have to feel the way this one did. Reviewing the account, requesting documentation, and understanding these protections ahead of time changes what dealing with debt collectors looks like, long before any payment gets discussed.

Disclaimer: This article is for informational purposes only and does not constitute legal or financial advice. Laws and individual circumstances vary. Consult a qualified professional before making debt-related decisions. Results are not guaranteed.

Paul Davis Restoration of Orlando Provides Restoration Services for Time-Sensitive Properties

By: Olivia Hughes

Property damage is disruptive under any circumstances. But when a water loss, fire event, storm intrusion, or microbial concern impacts an occupied building, the consequences extend far beyond the affected materials. In healthcare, senior living, hospitality, and multifamily communities, downtime can mean interrupted care, displaced residents, closed rooms, lost revenue, and increased stress for everyone involved.

Paul Davis Restoration of Orlando is building its approach around a clear priority: restoring property while minimizing operational disruption. The company’s model emphasizes rapid response, disciplined containment, clear communication, and the ability to manage projects from emergency mitigation through reconstruction, with a process designed to keep spaces safe, clean, and functional whenever possible.

Downtime-Critical Restoration For Occupied And Regulated Environments

Central Florida’s humidity and frequent storm patterns can turn small intrusions into major damage quickly, especially when a facility cannot simply shut down and wait. Paul Davis Restoration of Orlando focuses on “occupied-first” restoration protocols that protect the people inside the building while recovery work progresses.

Built For Healthcare, Senior Living, Hospitality, And Multifamily Properties

For regulated or sensitive environments, the difference is in the details: controlled work zones, HEPA filtration where appropriate, and procedures that reflect infection-control awareness and privacy considerations. In practical terms, that can include contained drying, dust-minimizing methods, and jobsite habits that prioritize discretion and safety, especially in settings where residents, patients, staff, or guests are present.

In hospitality and short-term stay environments, that same discipline supports phased work plans and scheduling strategies that reduce guest-facing impact. For multifamily and HOA-managed properties, it can also mean clear notices, orderly daily cleanup, and predictable progress updates that help residents feel informed rather than surprised.

One Team From Mitigation To Reconstruction

Many property damage events become more complicated when multiple vendors are required. One company handles mitigation, another manages contents, and a third handles reconstruction. Every handoff introduces delays, inconsistent documentation, and communication gaps.

Paul Davis Restoration of Orlando offers a single-team approach that can carry a project from initial stabilization through the rebuild. That includes water mitigation and structural drying, fire and smoke restoration support, reconstruction, and coordinated handling of contents when needed. With one team overseeing the full lifecycle, property owners and managers can reduce timeline friction and keep decisions moving under a consistent plan.

A Streamlined Approach That Reduces Delays And Handoffs

Instead of restarting the conversation at each phase, the project stays under one coordinated scope. That continuity can be especially valuable for buildings that need portions of the site reopened quickly or for owners who want a clear plan from day one.

Rapid Response And Communication When Minutes Matter

The first hours after property damage often decide how large the final impact becomes. Paul Davis Restoration of Orlando reports an average arrival time of 60 to 90 minutes in core areas and a commitment to be on site within four hours for emergency calls, excluding declared catastrophe events or unsafe conditions.

Response speed matters, but clarity matters just as much. The team emphasizes structured communication, including timely updates, defined milestones, and on-site documentation to support fast decision-making.

A Document-First Workflow That Supports Faster Decisions

From the beginning of a project, documentation can include photos, moisture readings, moisture mapping, and notes that clarify what happened and what is required next. That record supports more confident scoping and helps reduce confusion across stakeholders, including owners, managers, and insurance professionals.

Insurance Coordination Designed To Reduce Stress

Insurance is often the most stressful part of a restoration project, particularly when a property owner is juggling multiple responsibilities or trying to keep occupants informed. Paul Davis Restoration of Orlando positions insurance coordination as a core service: supporting claim initiation, communicating with adjusters once a claim number is established, and building carrier-ready documentation from the start.

Clear Scopes, Carrier-Ready Files, And Fewer Surprises

The company highlights detailed estimating practices and an emphasis on transparency, including written scopes and documented changes when conditions require supplements. The goal is to reduce avoidable friction: fewer surprises, fewer stalled approvals, and fewer situations where a property owner feels caught between contractors and carriers.

Training, Certifications, And Technology That Raise The Standard

Outcomes in restoration rely on both skilled professionals and the right tools. Paul Davis Restoration of Orlando emphasizes extensive training and industry-recognized certifications across its teams, including IICRC certifications, paired with equipment and methods designed to speed recovery while keeping occupied spaces cleaner and safer.

Equipment And Processes Designed For Cleaner, Faster Recovery

Depending on the project, the team may use resources such as HEPA air filtration, negative air containment, thermal imaging, and advanced documentation tools that support clearer reporting. For urgent or larger-scale needs, the company also notes readiness strategies that can include specialized drying capabilities and power solutions, supporting faster stabilization during time-sensitive events.

In addition to emergency restoration, the company offers free on-site assessments for many mitigation and rebuild projects in Greater Orlando, providing a practical starting point for owners and managers who need guidance without pressure.

Serving Greater Orlando With Accessibility And Language Support

Paul Davis Restoration of Orlando serves Greater Orlando, including Orlando, Winter Garden, and Windermere, with coverage emphasis in ZIP codes such as 32801, 34787, and 34786.

The company also notes accessibility accommodations such as wheelchair-accessible entrance, parking, restrooms, and seating, along with a gender-neutral restroom. Language assistance is available in English, Spanish, and Portuguese, supporting clearer communication for residents, guests, and stakeholders during high-stress events.

What Clients Notice Most: Professionalism, Thoroughness, And Care

When restoration is handled well, clients tend to remember the steady professionalism, not just the finished surfaces. That includes responsiveness, clear communication, and crews that respect the property and the people living or working inside it.

Customer feedback reflects that same emphasis on communication and professionalism. Eddy Quiroz shared, “I had the pleasure of collaborating with the Paul Davis company for a project, and I couldn’t be happier with the experience. From the start, the team was incredibly communicative and easy to work with. They took a proactive approach to ensure long-term solutions, not just a quick fix. The entire team was professional, respectful, and dedicated to getting the job done right.”

The Orlando team’s public-facing work also includes education and community involvement. Multiple local professionals have highlighted continuing education classes hosted through the company, describing the sessions as engaging and practical, with a tone that supports real-world application.

Where To Learn More

For restoration support, emergency service, and information about services and assessments, visit the Paul Davis Restoration of Orlando website. To see additional educational resources and updates, the company shares content on its YouTube channel and posts community and service updates on its Facebook page.

July Payrolls Report Looms as the Federal Reserve’s Final Labor Market Signal Before September

The Bureau of Labor Statistics will release the July 2026 Employment Situation report on Friday, August 7, at 8:30 a.m. ET, delivering the final major labor market reading before the Federal Reserve’s September 16 policy meeting. The report arrives after June’s payrolls figure came in at just 57,000 new jobs, the weakest monthly gain in four months, and after the Fed voted 9-3 on July 29 to hold the federal funds rate steady at 3.5% to 3.75%. The combination of softening employment data and a divided central bank has turned this week’s jobs number into one of the more consequential data releases of the year for rate-path expectations.

  • The Bureau of Labor Statistics reported June nonfarm payrolls of 57,000, well below the 110,000-115,000 consensus and roughly in line with the 12-month average of 36,000 jobs per month
  • April and May payrolls were revised downward by a combined 74,000 jobs, bringing April to 148,000 and May to 129,000
  • The June unemployment rate edged down to 4.2%, but labor force participation fell 0.3 percentage points to 61.5%, its lowest reading since March 2021
  • The Federal Reserve held rates at 3.5%-3.75% on July 29 in a 9-3 vote, with Chairman Warsh noting that “economic activity is expanding at a solid pace despite elevated uncertainty”
  • The July payrolls and August CPI reports are the two primary data inputs the FOMC will evaluate ahead of its September 16 rate decision

June’s Employment Data in Detail

The Bureau of Labor Statistics’ June Employment Situation report painted a mixed picture of the U.S. labor market. The headline nonfarm payrolls figure of 57,000 fell short of expectations, but the composition of the gains offered context that the topline number alone does not capture. Professional and business services added 36,000 jobs, continuing an upward trend that has produced 172,000 positions in the sector since October 2025. Social assistance contributed 25,000 jobs, driven primarily by individual and family services. Health care added 22,000 positions, though at a slower pace than the 38,000-per-month average over the prior year.

Leisure and hospitality, however, shed 61,000 jobs in June, reflecting weaker-than-usual seasonal hiring patterns. The BLS noted that employment in the industry has shown little net change so far in 2026. The sector’s contraction accounted for a significant drag on the headline figure and underscored the uneven nature of the current labor market expansion, where gains in professional services and health care are being partially offset by softness in consumer-facing industries.

The downward revisions to April and May were equally notable. April’s payrolls were revised from 179,000 to 148,000, and May’s from 172,000 to 129,000, a combined reduction of 74,000 jobs. Revisions of that magnitude can reshape the narrative around labor market momentum, and in this case, they suggest that the spring hiring pace was softer than initially reported.

The Household Survey and Participation Decline

The household survey, which measures unemployment and labor force participation through a separate methodology from the establishment payrolls survey, showed the unemployment rate at 4.2%, little changed from the prior month. The number of unemployed people held at 7.1 million. Among major worker groups, adult men posted a 3.9% unemployment rate, adult women 3.7%, and teenagers 14.6%.

The more concerning signal came from labor force participation. The rate fell 0.3 percentage points to 61.5%, the lowest level since March 2021, and the employment-population ratio edged down 0.2 percentage points to 59.0%. Long-term unemployment (27 weeks or more) held at 1.9 million but has risen by 286,000 over the past year, now accounting for 27.3% of all unemployed workers. The number of people working part-time for economic reasons, those who would prefer full-time work but had their hours cut or could not find full-time positions, held at 4.7 million.

The participation decline complicates the rate picture. A falling unemployment rate driven by fewer people looking for work carries different implications for the Fed than one driven by strong hiring. The July report will reveal whether June’s participation drop was an anomaly or the beginning of a trend.

The Federal Reserve’s July Decision and September Outlook

The Federal Open Market Committee voted 9-3 on July 29 to maintain the federal funds rate target range at 3.5% to 3.75%. The statement noted that economic activity continues to expand at a “solid pace” despite elevated uncertainty, that productivity growth and capital investment remain strong, and that job gains have “kept pace with the workforce.” On inflation, the committee acknowledged that price pressures remain “elevated relative to the Committee’s 2 percent goal,” driven in part by supply shocks in sectors including energy.

The 9-3 vote marked a notable division. Three dissenting members voted against holding, suggesting internal disagreement about whether current policy is appropriately calibrated to the economic data. Chairman Warsh’s press conference reinforced that the committee is data-dependent heading into September, with the July employment report and the August CPI release serving as the two most consequential inputs.

Wage data from the June report added another variable. Average hourly earnings for all private-sector employees rose 0.3% in June to $37.64, with year-over-year growth at 3.5%. Wage growth at that pace remains above levels consistent with the Fed’s 2% inflation target, and a repeat or acceleration in the July data could reinforce the case for holding rates steady through September. A soft payrolls number paired with cooling wages, on the other hand, could build the argument for a rate cut.

The Week Ahead and Data Landscape

The July payrolls report does not arrive in isolation. Tuesday, August 5, brings the ADP National Employment Report for July, which tracks private-sector hiring through payroll data from ADP’s client base. The same day, the Institute for Supply Management releases its Services PMI for July, and S&P Global publishes the final reading of its Services PMI. Each of these data points feeds into the broader picture of labor market health and economic activity that the Fed will evaluate before September.

The BLS has also scheduled a preliminary benchmark revision to establishment survey data for August 28, 2026. That revision, which benchmarks payrolls estimates to comprehensive employment counts from the Quarterly Census of Employment and Wages, could result in significant adjustments to the reported job gains over the past year. Benchmark revisions have, in prior years, shifted the labor market narrative substantially, and market participants will be watching for any large discrepancies between the current estimates and the QCEW-based counts.

For the week ahead, the July payrolls number will set the tone. A rebound toward the 100,000-plus range could ease concerns about labor market deterioration and reduce pressure on the Fed to act in September. A second consecutive miss below expectations would sharpen the debate over whether the current rate stance is too restrictive for an economy where hiring is slowing, participation is falling, and long-term unemployment is rising.

Disclaimer: This article is for informational purposes only and does not constitute financial, investment, or trading advice. Market Daily does not recommend the purchase or sale of any securities. Readers should consult a qualified financial advisor before making investment decisions based on economic data or Federal Reserve policy expectations.

FAQs

When is the July 2026 jobs report released?

The Bureau of Labor Statistics will publish the July 2026 Employment Situation report on Friday, August 7, 2026, at 8:30 a.m. ET.

What did the June 2026 jobs report show?

June nonfarm payrolls came in at 57,000 new jobs, well below consensus estimates. The unemployment rate was 4.2%, and labor force participation fell to 61.5%. April and May payrolls were revised downward by a combined 74,000.

What is the current federal funds rate?

The Federal Reserve held the federal funds rate target range at 3.5% to 3.75% at its July 28-29, 2026 meeting, in a 9-3 vote.

When is the next Federal Reserve rate decision?

The next FOMC meeting is scheduled for September 16, 2026. The July payrolls report and the August CPI release are the primary data inputs the committee will evaluate ahead of that decision.